

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts MCU Market to Nearly Double from USD 39.48B in 2025 to USD 72.2B by 2032 at an 8.6% CAGR — Asia-Pacific Leads with USD 23.42B

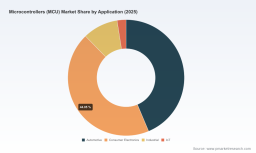
Microcontrollers (MCU) Market: Strategic Imperatives for 2026 — PW Consulting Snapshot
PW Consulting’s new Microcontrollers (MCU) Market report (base year 2025, historical 2020–2025, forecast 2026–2032) reframes executive decision-making for 2026 by combining rigorous market-sizing with pragmatic, execution‑oriented playbooks. Our analysis shows the global MCU market expanding from an assessed USD 39.48 Billion in 2025 and tracking to roughly USD 72.2 Billion by 2032 under a central scenario (compound annual growth rate of 8.6% across the forecast window). That trajectory is not uniform: it reflects accelerating demand for edge AI, safety‑critical automotive electronics, and power‑efficient IoT endpoints, intersecting with structurally tighter supply and episodic policy disruptions.
Microcontrollers (MCU) Market
Why this matters for corporate strategy in 2026
-
Growth with friction. Fast‑growing end markets are colliding with supply constraints, pricing pressure and regulatory change. The result is a higher probability of design‑win volatility and cost shocks that can materially alter product economics within a 6–18 month horizon.
Microcontrollers (MCU) Market -
Concentration and leverage. Market concentration remains meaningful: the top three players account for a substantial share of industry revenues, while the top five expand that footprint further. This dynamic shapes negotiation leverage with OEMs, foundries and subcontractors.
Microcontrollers (MCU) Market -
Technology inflection points. Integration of AI acceleration into MCU platforms, combined with a renewed emphasis on functional safety and secure elements, is shifting differentiation from raw silicon to system‑level software, reference IP and validated ecosystems.
-
Policy and supply‑chain risk. New tariffs, rare‑materials licensing and parts lead times have become permanent variables in risk models. Procurement, design and strategy teams must transform from reactive to scenario‑driven planning to maintain margins and time‑to‑market.
What the report delivers — practical, actionable content
-
Market sizing and forward scenarios: audited global totals (2020–2025 historical), a base‑year calibration (2025), and three forward scenarios across 2026–2032 that separate demand drivers (edge AI, automotive electrification, industrial automation) from supply contingencies.
-
Provider benchmarking and capability maps: multi‑dimensional supplier profiles focused on architectural strengths (core types, integrated analog, security fabrics), go‑to‑market positioning and ecosystem maturity.
-
Product and design playbooks: decision templates for choosing MCU families by use‑case, migration pathways for legacy architectures, and code‑level strategies to maximise portability and reduce redesign costs.
-
Procurement and supply‑chain playbooks: contracting templates, dual‑sourcing blueprints, long‑lead part hedging strategies and inventory optimisation routines designed for 6–24 month operational cycles.
-
Regulatory and commodity risk matrix: scenario models quantifying the potential impact of tariffs, export controls and rare‑material constraints on unit economics and lead times — including contingency actions.
-
M&A and partnership scorecards: screening criteria and integration plans for capability buys (software stacks, IP, foundry relationships) and strategic partnerships to accelerate time‑to‑market.
Methodology and data integrity
-
Empirical foundation. Our base‑year (2025) calibration reconciles company disclosures, proprietary shipment telemetry, foundry utilization data and end‑market build plans. Historical series cover 2020–2025 and underpin the forecast window 2026–2032.
-
Scenario architecture. Forecasts use a three‑track scenario set — Base, Upside and Stress — that isolate demand acceleration (edge AI adoption, EVs and automation) from supply shocks (tariffs, material restrictions and foundry capacity shifts).
-
Concentration metrics. We include market concentration analysis to help clients model bargaining power and supplier risk. Our headline concentration metrics indicate that a small group of suppliers capture a disproportionate share of market revenue, reinforcing the need for tailored supplier strategies.
Competitive landscape — reading the leaders and fast followers
The competitive map is evolving from pure silicon leadership to solution orchestration. Firms that pair system‑level software, security, and analog integration with stable supply chains will capture the most lucrative design wins. Below we highlight key players whose moves are most consequential for 2026 planning.
-
Texas Instruments Incorporated (Dallas, Texas): TI’s MSP family and ARM Cortex‑M0+ offerings have historically anchored industrial and mixed‑signal use cases. Recent portfolio expansions that embed NPUs for edge AI underscore a strategic pivot from microcontroller incumbency to hybrid MCU+accelerator platforms — a development that shifts product roadmaps for OEMs targeting on‑device inference.
-
NXP Semiconductors (Eindhoven): NXP’s emphasis on high‑performance Kinetis/i.MX‑adjacent architectures positions it strongly in automotive and industrial edge compute. NXP’s pricing actions and capacity allocation choices will be a focal input into tier‑1 supplier sourcing scenarios.
-
STMicroelectronics (Geneva): STM32 and STSAFE continue to be go‑to options for developers requiring broad ecosystem support and advanced security. Notably long lead times in some product families have created execution risk for automotive OEMs and industrial integrators.
-
Renesas Electronics (Tokyo): Renesas’ RA and RX lines provide real‑time control and connectivity building blocks for safety‑critical systems. Their product portfolio is a natural bedrock for developers migrating from 16/32‑bit controls to more integrated solutions.
-
Microchip Technology (Chandler): Microchip’s PIC and AVR family strengths in cost‑sensitive segments are complemented by strategic partnerships, including recent work on radiation‑hardened spaceflight MCUs — an example of product diversification to adjacent high‑value niches.
-
Infineon Technologies (Munich): With safety‑centric AURIX and XMC families, Infineon is a leading supplier for automotive and industrial domains where power management and functional safety converge.
-
Toshiba Electronic Devices & Storage (Kawasaki): Toshiba’s motor‑control centric families are being extended into integrated driver+MCU modules — recent sample shipments for automotive motor control demonstrate time‑to‑market acceleration for integrated solutions.
-
Silicon Labs (Austin): Energy‑efficient cores with strong IoT connectivity position Silicon Labs as a preferred partner for constrained, battery‑sensitive endpoints.
Recent market signals that should inform 2026 plans
-
Product and capability moves: several vendors have launched or sampled MCUs with integrated NPUs and motor‑control drivers in 2026, signaling faster on‑device AI adoption and tighter system integration.
-
Pricing and capacity pressures: selected vendors have announced broad price increases driven by elevated foundry costs; concurrent reports of extended lead times for key automotive parts create immediate procurement friction for OEMs.
-
Policy and materials: tariff measures, licensing regimes for specialty materials and spikes in certain commodity prices (tungsten, gallium and other critical inputs) can rapidly change landed costs and availability for specific architectures.
Strategic implications and recommended actions for 2026
We translate analysis into a concise set of priorities for executives who must make decisions now that will still matter in 2028.
-
Operationalize scenario planning: embed three supply‑shock scenarios in product planning and financial forecasts. Use them to set procurement triggers, design freeze deadlines and buffer inventory policies.
-
Diversify architectural exposure: prioritize software portability and abstraction layers so products can switch between MCU families with minimal rework. This reduces design‑win risk when supplier allocations tighten.
-
Secure long‑lead capacity selectively: for safety‑critical or high‑value product lines, negotiate multi‑year allocations and co‑development agreements with preferred vendors to lock in supply and roadmap influence.
-
Reprice and renegotiate: recalculate product economics assuming elevated ASPs for MCUs; update OEM contracts and channel incentives accordingly to preserve margin.
-
Invest in ecosystem play: for semiconductor companies, prioritize software stacks, reference designs and developer tooling that speed adoption of new MCU capabilities (security, AI, motor control).
-
Explore targeted M&A and partnerships: focus on assets that plug immediate gaps — secure elements, AI inference IP, and specialty analog — rather than broad product roll‑ups.
Decision playbook — an executive checklist
-
1) Recalibrate P&L models using the report’s base growth assumptions and stress cases (use 2025 as the calibration year).
-
2) Run a supplier criticality map: identify top‑quartile revenue drivers and the critical MCUs that expose your product roadmap to supplier concentration risk.
-
3) Execute dual‑sourcing or design abstraction for at least two flagship platforms within 12 months.
-
4) Implement contractual clauses for price pass‑through or shared cost‑inflation mechanisms where possible to contain margin erosion.
-
5) Track five leading indicators monthly: foundry utilization, announced lead times for critical MCU families, ASP movement, tariff developments and critical material availability.
Closing — how PW Consulting helps
The PW Consulting MCU report is engineered as both intelligence and instrument. It provides validated market sizing from 2020–2025, a transparent base‑year (2025) calibration, and a forward view (2026–2032) with a central CAGR of 8.6%, while pairing that analysis with playbooks and templates that leaders can deploy within 30 to 120 days. We intentionally refrain from publishing certain granular segment tables in this summary so decision‑makers visit the full report for validated split‑level intelligence and downloadable tools that operationalize these insights.
For boards, product chiefs and procurement heads preparing 2026 budgets and roadmaps, the decisive value is not just knowing that the market is growing — it is understanding which exposures to hedge, which architectural bets to double down on, and how to convert macro insights into executable actions. PW Consulting’s full report contains the detailed splits, scenario files and implementation templates that make those decisions both defensible and executable.
To access the complete report, scenario models and executable playbooks, visit the PW Consulting research portal or contact our lead analysts for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com