

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.45% CAGR for Marine Internal Combustion Engine Market (2026–2032)

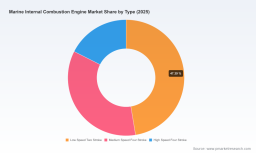
Marine Internal Combustion Engine Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest Marine Internal Combustion Engine Market study—anchored on a 2025 base year and a historical window spanning 2020–2025—offers a forward-looking playbook for executives making capital, product and regulatory-compliance decisions in 2026. The market demonstrated steady expansion through the first half of the decade and reached approximately USD 190.34 Million (revenue unit: Million) in 2025. Our forecast for 2026–2032 projects the market will continue to grow at a compound annual growth rate (CAGR) of 5.45%, culminating in an estimated market size of roughly USD 272.45 Million by 2032. These macro dynamics—when combined with accelerating regulatory change and fuel-technology disruption—create a narrow window for value capture in the next 12–36 months.
Marine Internal Combustion Engine Market
Why this report matters for 2026 decision-making
-
Timing capital expenditure: The combination of steady market expansion and tightening emissions requirements means that propulsion and auxiliary engine investments made in 2026 will set total cost of ownership (TCO) and compliance trajectories for the following decade. The 5.45% CAGR underpins revenue and fleet-replacement assumptions used in CAPEX models.
Marine Internal Combustion Engine Market -
Fuel and technology transitions: OEMs and shipowners face competing pressures to adopt methanol-, ammonia- and hybrid-ready systems while preserving operational reliability. The report isolates the decision gates where switching to fuel-flexible technology yields the highest risk-adjusted returns.
Marine Internal Combustion Engine Market -
M&A and supply-chain prioritization: Moderate market concentration—where the top three and top five suppliers account for a meaningful share of industry sales—creates opportunities for niche consolidation, strategic partnerships, and aftermarket service plays. Our competitive analysis highlights where scale matters and where specialization creates defensible margins.
-
Regulatory compliance planning: With IMO amendments and class approvals accelerating, engines procured in 2026 must be evaluated against rules that enter into force in the near term. The report maps compliance timelines to procurement and retrofit pathways.
Market dynamics shaping near-term strategy
The engine market’s steady historical growth has been driven by persistent global shipping demand, replacement cycles, and the evolution of propulsion architectures that balance efficiency and emissions. Key systematic forces for 2026 include:
-
Regulatory tightening and certification timelines. Recent amendments to the Energy Efficiency Design Index (EEDI) framework were adopted in 2025 and will materially affect certification and survey paths beginning shortly thereafter. This compresses the timeframe for shipowners to validate new engine types and retrofit solutions.
-
Rapid emergence of alternative fuel-ready platforms. Major OEM announcements and testing programs during 2024–2026 have moved candidate fuel pathways from concept to commercial demonstration. Approvals-in-principle and full testing of methanol- and ammonia-capable engines are lowering technical barriers, but fuel logistics and lifecycle-carbon accounting remain decisive for deployment.
-
Technological convergence around hybridization and digitalization. Medium-speed four-stroke and low-speed two-stroke architectures are increasingly integrated with electric-hybrid systems, energy-storage, and advanced controls to optimize fuel consumption across operational profiles.
-
Service and aftermarket economics. As OEMs diversify propulsion portfolios, aftermarket revenue and localized service networks become critical competitive differentiators—especially for owners with mixed fleets or vessels operating in fuel-constrained regions.
What the report contains (practical, execution-oriented)
-
Market sizing and forecasting model (2020–2032) with transparent assumptions and scenario sensitivity to fuel prices, retrofit rates, and regulatory milestones.
-
Technology diffusion curves that compare adoption pathways for conventional diesel, methanol, ammonia, and hybrid propulsion across plausible operational scenarios.
-
Regulatory impact matrix linking IMO rule changes and class approvals to procurement and retrofit decision points—complete with recommended compliance timelines for newbuilds and in-service fleets.
-
Supplier benchmarking and procurement playbooks: a methodical framework to evaluate OEM offers (capability, fuel flexibility, lifecycle cost, service footprint) and negotiate risk-sharing contracts.
-
CapEx / OpEx modeling templates and TCO calculators tailored to commercial shipping, fishing, and harbour craft use cases—designed for immediate incorporation into 2026 budgeting cycles.
-
Scenario-based M&A and partnership scorecards that highlight targets by strategic intent—geographic reach, aftermarket strength, technology IP, and fuel-readiness.
Competitive landscape: where incumbents and challengers are placing their bets
The market structure is moderately concentrated—our analysis indicates a top-3 share and top-5 share that reflect significant lead players while leaving room for specialized or regional challengers. Leading global OEMs are differentiating by fuel-flexibility, hybrid integration, and service ecosystems:
-
Wärtsilä (Finland) is pushing medium-speed four-stroke main engines and hybrid propulsion systems, positioning itself as a systems integrator for energy-efficiency upgrades and hybridization.
-
MAN Energy Solutions (Germany) continues to anchor demand for large two-stroke, low-speed installations while advancing dual-fuel solutions—most notably ammonia-capable ME-LGIA variants—targeting long-haul commercial tonnage.
-
Rolls-Royce (United Kingdom) is leveraging high-speed mtu platforms and has validated methanol-only operation through recent testing—an important proof point for operators seeking lower-carbon high-speed options.
-
Cummins Inc. (United States) is expanding its marine portfolio with the K50 and QSB/QSK series and has secured class approvals for methanol-ready variants—an example of a tier-one supplier converting emissions-regulatory momentum into near-term product wins.
-
AB Volvo (Volvo Penta), Caterpillar, Daihatsu, Hyundai Heavy Industries and Yanmar continue to consolidate positions across propulsion and auxiliary segments, focusing on reliability, service networks and regional market access.
-
Everllence (Germany) is notable among smaller OEMs for publishing a comprehensive 2025 engine programme and emphasizing compliance with current emission tiers—demonstrating that product transparency can accelerate commercial adoption.
Recent developments underscore these strategic moves: Cummins showcased the K50 at Asia Pacific Maritime 2026, Rolls‑Royce completed successful methanol-engine testing in late 2025, and class approvals and IMO amendments in 2025 have tightened the practical compliance timeline for new equipment.
Strategic recommendations for 2026
Based on the interplay of market growth, regulatory change, and supplier positioning, PW Consulting recommends a phased set of actions for operators, OEMs and investors planning in 2026:
- Immediate (0–12 months): Prioritize fuel-flexibility in procurement specs and embed retrofit pathways in contract terms. Lock in conditional supply agreements with OEMs that include performance guarantees and retrofit options. Use our TCO templates to stress-test CAPEX with fuel-price and carbon-cost sensitivities.
- Near term (12–36 months): Deploy pilot programmes for methanol or hybrid integration on select vessels with measurable KPIs (fuel consumption, emissions, downtime). Strengthen local service partnerships to reduce time-to-repair risk for novel fuel systems.
- Strategic (3–7 years): Build or acquire aftermarket capabilities that monetize predictive maintenance and component remanufacture. For OEMs, invest in modular platform architectures enabling rapid swapping of fuel-system modules to preserve product relevance across uncertain fuel pathways.
- Financial discipline: Use scenario-based valuation for M&A to reflect both stranded-asset risks and aftermarket upside. The market’s projected CAGR should be treated as a baseline scenario; downside and upside cases must be stress-tested against regulatory accelerants and fuel-supply shocks.
How PW Consulting’s report enables execution
We designed this work as an operational guide rather than a high-level overview. Subscribers receive executable assets: raw model files, procurement scorecards, retrofit decision matrices, and regionally configurable TCO tools. While this briefing highlights the macro trajectory and thematic imperatives, our full deliverable provides the granular datasets, supplier scorecards and region/application splits required to operationalize 2026 strategies.
Call to action
For executives who must decide where to allocate capital, which propulsion partners to select, or how to sequence fleet retrofit programs, the choices made in 2026 will determine competitive positioning through 2032. PW Consulting’s Marine Internal Combustion Engine Market report equips teams with the data, scenarios and negotiation frameworks to make those choices confidently. Access the full report for detailed regional and segment-level analytics, unit-level pricing, and supplier scoring that we intentionally omit from this preview to preserve the report’s strategic value.
PW Consulting—advanced industry insight to convert market forecasts into winning strategy.
For detailed analysis of this topic, please visit the official page: Marine Internal Combustion Engine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com