

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HPL Boards Market to Expand at a 4.4% CAGR Through 2032 as Asia Pacific Drives Demand

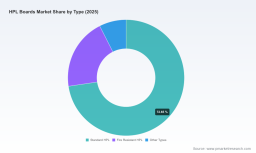
HPL Boards Market 2026 Strategic Brief: Key Imperatives from PW Consulting's New Report
Executive summary
PW Consulting's HPL Boards Market report (base year 2025; historical 2020–2025; forecast 2026–2032) identifies a market in steady expansion and structural transition. Total industry revenue rose from USD 4,087.0 Million in 2020 to USD 5,127.0 Million in 2025. Our 2026 outlook projects USD 5,451.7 Million, with a continued trajectory to USD 6,863.0 Million by 2032 — representing a compound annual growth rate (CAGR) of 4.4% over the 2026–2032 forecast window. Market concentration is moderate: CR3 at 28.5% and CR5 at 34.2%, signaling meaningful room for consolidation, differentiation, and new entrants focused on niche performance and sustainability attributes.
HPL Boards Market
Why 2026 is a strategic inflection point
A confluence of regulatory updates, raw-material volatility, and design-driven demand is reshaping the competitive equation for HPL producers and buyers in 2026. Two regulatory milestones — updates to EN 438 guidance for exterior compact façade panels and the introduction of EN 438-9:2026 classification criteria for alternative-core HPL — are tightening technical requirements around flexural strength, ignitability and fire classification. Concurrently, the market experienced an 8–12% rise in HPL laminate prices between early and mid‑2026, driven by higher shipping and resin costs. These two dynamics combine to elevate both the cost of compliance and the cost of goods sold for manufacturers, while creating an opening for suppliers that can credibly demonstrate certified performance and supply-chain resilience.
HPL Boards Market
What the report delivers — practical, decision-ready intelligence
- Transparent market sizing and forward scenarios: Full revenue models from 2020 through 2032 (historical and projected), including base-case, upside and downside scenarios calibrated to raw-material price trajectories, trade-shock scenarios, and demand elasticity assumptions.
- Diagnostic demand analysis: Root-cause drivers of growth across interior, exterior and specialty applications, with buyer persona mapping (architects, distributors, large contract purchasers, retail channels) and purchase criteria prioritized by segment.
- Cost and margin models: Bottom-up cost components (resins, kraft papers, decorative papers, energy, labour, logistics) and their sensitivity to fluctuating resin and freight prices — built to support procurement negotiations and price‑adjustment mechanisms.
- Regulatory and certification playbook: Step-by-step compliance roadmaps for EN 438-9:2026 and EN 13501-1 fire classification, plus pathways to voluntary credentials (including Cradle to Cradle Bronze v4.0) and how these affect premium positioning and spec adoption.
- Supply-chain risk map: Supplier concentration, geographic sourcing risks, lead-time matrices and mitigation levers (dual sourcing, resin substitution scenarios, on-shore compounding options).
- Product and go-to-market toolkits: New product concept prioritization (fire-resistant HPL, compact exterior HPL, extreme-weather ranges), pricing guidance, channel strategies and a turnkey launch checklist for 12–18 month initiatives.
- Competition playbooks and M&A targets: Strategic profiles of incumbent and emerging players, capability gaps, inorganic opportunities and valuation guardrails for bolt-ons or brownfield expansion.
- Practical annexes and models: Downloadable Excel models, RFx templates, and an actionable vendor-selection scorecard calibrated for 2026 procurement cycles.
Competitive landscape — positioning and strategic moves
The HPL market reflects a mix of global incumbents, regional specialists and vertically integrated panel producers. The landscape is shifting from purely scale-driven advantage to a hybrid model where certified sustainability claims, specialized product collections and rapid product refresh cycles confer premium access to specification-driven channels.
HPL Boards Market
- Global incumbents and broad-surface players: Companies such as Wilsonart International (Texas, United States) and Formica Group (United States) remain influential through deep channel relationships, broad commercial portfolios and investment in surface aesthetics. Wilsonart’s commercial product launch and Woodgrains™ options (Dec 2025) underline a continued strategy of design-led differentiation and spec outreach. (See: https://www.wilsonart.com/)
- European design and performance specialists: Pfleiderer (Germany), Trespa (Netherlands), Arpa Industriale (Italy), FunderMax (Austria) and Unilin Panels (Belgium) position on certified quality, architectural performance and sustainability. Recent product collection releases from Pfleiderer and trend-focused portfolios emphasize certified sustainability and performance credentials that architects and façade specifiers increasingly demand.
- Scale and cost-competitive suppliers: Kronospan (Luxembourg) and several Asian producers continue to compete on value and availability for furniture, interiors and mass-market applications. Changzhou Panels New Materials (China) exemplifies the manufacturing cost-leverage and rapid SKU expansion model targeting kitchen and furniture segments. (See: https://www.czpanels.com/)
- Regional-growth innovators: Greenlam Industries (India) has accelerated its market presence through consecutive collection releases (notably the 2025–2027 collection for extreme-weather applications) and expanded sizing capabilities — signaling a push into higher-durability and climate-resilient specifications. (See: https://www.greenlam.com/)
Collectively, recent product launches and collection refreshes (Wilsonart, Greenlam, Pfleiderer) demonstrate a clear market tilt: design-led differentiation, certified sustainability and productized performance (fire-rated, weather-resistant compacts) are now core competitive vectors.
Practical strategic priorities for 2026 decision-makers
- Price‑and-procurement agility: Lock in medium-term resin contracts, institute pass-through clauses, and stress-test supplier agreements against a +10% price shock scenario. Tactical inventory buffers for critical resin grades have high ROI in the current environment.
- Certify to compete: Prioritize certification routes that unlock specification channels — EN 438 compliance, EN 438-9 for alternative cores, and Cradle to Cradle Bronze where feasible. These credentials materially affect bid success rates in institutional and architectural tenders.
- Product segmentation and SKU rationalization: Reallocate R&D spend toward high-margin, specification-sensitive SKUs (fire-resistant and extreme-weather HPLs) while optimizing SKU counts in lower-margin commodity lines to improve working capital and forecasting accuracy.
- Channel partnerships and specification influence: Invest in specification teams, digital sample systems, and architect/designer programs to shorten time-to-spec and capture premium pricing windows on new collections.
- Operational resilience: Consider regionalized compounding and selected onshore extrusion/lamination capabilities to reduce freight exposure and lead times for priority markets.
- M&A and alliances: Pursue bolt-on acquisitions that fill capability gaps (compact HPL, fire-rated formulations, certified decorative papers) where valuation aligns with synergy potential; prioritize targets that enhance specification credentials or secure critical raw-material flows.
How buyers and sellers should use this report in 2026
For C-suite leaders, procurement heads, product managers and corporate development teams, the report is a decisioning tool — not an academic exercise. Use it to:
- Inform three-year capex and footprint decisions with scenario-based cash-flow models;
- Negotiate supplier contracts armed with granular cost and margin analytics;
- Prioritize product roadmaps and certification investments to maximize share in specification-led segments;
- Identify M&A targets and define integration playbooks for rapid capability capture.
Closing perspective
The HPL boards market in 2026 is neither a commodity race to the bottom nor a closed club reserved for scale incumbents. It is a market where technically credible performance, certified sustainability, and supply-chain dexterity enable outsized returns. With an expected CAGR of 4.4% through 2032 and a moderate concentration profile, strategic clarity — combined with tactical procurement, certification, and product plays — will separate winners from the field. PW Consulting’s HPL Boards Market report is designed to convert that clarity into executable plans: detailed models, regulatory playbooks, and go-to-market tools that arm leaders to make confident decisions in 2026 and beyond.
Access the full intelligence
This release outlines the strategic framing and executive takeaways. The report contains the underlying segmented datasets, competitive profiles, and downloadable decision tools referenced above. To access the full dataset and the practical annexes required for 2026 planning, please visit the report page on PW Consulting’s website or contact our industry practice leads for a licensed copy.
For detailed analysis of this topic, please visit the official page: HPL Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com