

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PCM Market Analysis: Why 17.4% CAGR and $662M Size Redefine the Industry

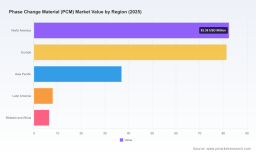
The Phase Change Material Market: Strategic Trends and Commercial Opportunities Through 2032
The phase change material market has entered a decisive growth cycle. Valued at approximately $215 million in 2025 and projected to exceed $660 million by 2032, the sector is expanding at a compound annual growth rate of 17.42 percent. This trajectory reflects a structural shift rather than a cyclical upturn. Phase change materials are moving from niche thermal management applications into mainstream commercial deployment across buildings, healthcare logistics, energy storage, and industrial cooling. The acceleration is being driven by converging pressures: stricter energy efficiency mandates, rising cold chain complexity, and a corporate push toward passive thermal solutions that reduce operational energy consumption.
Yet growth alone does not guarantee commercial success. Companies operating in this space face a market that is simultaneously expanding and fragmenting. Demand is broadening across multiple application verticals, but each vertical carries distinct performance requirements, regulatory expectations, and procurement cycles. The result is a landscape where material science, application engineering, and compliance capability often matter more than raw production capacity. Understanding where the market is heading—and where the bottlenecks lie—requires looking beyond headline growth figures and examining the forces reshaping competitive positioning.
Market Reality and the Core Challenges Ahead
The current market structure reflects both momentum and friction. Growth is anchored by a broad base of end-use sectors, but the pace of adoption varies significantly depending on how readily phase change materials can be integrated into existing systems. In mature applications, performance validation and lifecycle economics are well understood. In emerging use cases, the burden of proof remains high, and procurement teams are often cautious about switching from established thermal management approaches.
Three challenges define the current inflection point:
Performance Standardization and Validation Gaps
Despite rapid commercial interest, the industry still lacks universally accepted testing protocols and performance benchmarks across different material chemistries and operating conditions. Buyers in construction, healthcare, and energy storage frequently encounter inconsistent data on thermal conductivity, cycling durability, and long-term stability. This creates hesitation among engineering-led procurement teams and lengthens qualification cycles. Companies that can provide independent validation, repeatable performance data, and transparent degradation profiles gain a meaningful advantage in markets where trust is still being built.
Cost Structure and Scalability Tension
Phase change materials are increasingly expected to deliver both thermal performance and economic efficiency. However, high-performance formulations often require precise synthesis, specialized encapsulation, or advanced stabilization techniques that raise production costs. At the same time, price-sensitive segments such as large-scale building integration and consumer-adjacent applications exert downward pressure on unit economics. The tension between performance differentiation and cost competitiveness is forcing manufacturers to make deliberate choices about where to position their products. Broad commoditization risks eroding margins, while overly specialized solutions can limit addressable volume.
Regulatory and Application-Specific Compliance Burdens
Regulatory expectations are becoming a more decisive factor in market access, particularly in pharmaceuticals, medical devices, and building materials. In healthcare logistics, temperature-controlled shipping must meet stringent handling and safety requirements. In construction and energy applications, material classification, fire performance, and environmental compliance can influence specification decisions. These requirements are not uniform across regions or verticals, which means companies must navigate a patchwork of standards rather than a single global framework. Compliance capability is therefore evolving from a backend obligation into a front-line differentiator.
Core Drivers Reshaping the Market
The expansion of the phase change material market is not being pulled by a single force. It is being reshaped by four interconnected drivers that reinforce one another and create distinct strategic implications for participants.
Worldwide Paraffin Phase Change Material (PCM) Market
Technological Innovation and Material-Level Breakthroughs
Material innovation remains the most direct lever for market expansion. Advances in organic, inorganic, and bio-based formulations are widening the range of usable temperature windows and improving stability under repeated thermal cycling. Equally important is the development of shape-stable and composite systems that reduce leakage risk and simplify integration into walls, panels, packaging, and storage units. These improvements lower the engineering barrier for adoption and make phase change materials more compatible with existing manufacturing and construction processes.
Recent product activity illustrates this trajectory. In April 2024, Pluss Advanced Technologies introduced a form-stable organic PCM designed for pharmaceutical cold chain logistics in the 2°C to 8°C range. That launch signaled a focus on application-specific thermal precision rather than generic cooling capacity. More recently, in June 2025, Cryopak expanded its cold chain portfolio with a flexible high-performance universal packaging solution featuring integrated PCM. These moves reflect a broader industry shift: the value proposition is moving from raw material supply toward engineered, application-ready thermal systems.
PCM Metal Sheet Market
Policy and Regulatory Environment as a Deployment Accelerant
Policy momentum is strengthening the economic case for passive thermal management. Energy efficiency targets in buildings, decarbonization goals in industrial operations, and reliability requirements in healthcare logistics all create indirect pressure to adopt materials that reduce active cooling loads or improve temperature stability. Where regulations or procurement standards begin to reward lower energy consumption, longer service life, or reduced dependency on continuous refrigeration, phase change materials become more attractive in feasibility studies and specification lists.
PW Consulting
Regulatory dynamics are also shaping product design. In medical and pharmaceutical applications, compatibility and safety expectations increasingly influence material selection. Patents and technical approvals are becoming relevant commercial signals. For example, Microtek Laboratories secured a U.S. patent in April 2025 for radiation-curable shape-stable thermoset PCM gels designed for medical cold packs, a development that underscores how intellectual property and regulatory-aligned formulation work are converging. In parallel, companies such as Modus Advanced must ensure that PCM systems intended for patient-contact medical devices meet FDA biocompatibility standards, reinforcing the need for early-stage compliance planning rather than retrospective adaptation.
Demand-Side Shifts in Cold Chain, Healthcare, and Building Operations
Demand is being reshaped by operational risk tolerance and total-cost thinking. In pharmaceutical and biologics transport, the consequences of temperature excursions have made thermal reliability a strategic priority rather than a logistics detail. This is driving interest in PCM-based containers, packs, and shippers that can maintain narrow temperature bands with less reliance on active refrigeration. In building and construction, operators and developers are increasingly evaluating thermal mass and temperature-regulation materials as part of broader energy-reduction strategies. The shift is not simply about acquiring a new material; it is about reducing vulnerability in fragile supply chains and lowering long-term energy exposure in built environments.
Supply Chain and Cost Dynamics
Supply chain factors are becoming more central to competitive positioning. Material availability, encapsulation capacity, packaging integration, and regional manufacturing footprints all influence responsiveness and margin structure. While some components remain subject to broader chemical and raw material cost fluctuations, companies are also finding advantage in localized production, application-tailored packaging, and closer collaboration with end-users. Pricing transparency is rising in certain segments, and customers are increasingly comparing solutions on installed performance rather than unit price alone. For example, in pharmaceutical applications, pricing for PCM cooling solutions has been positioned in a range that reflects both performance specificity and volume considerations, reminding manufacturers that price leadership without differentiated performance is difficult to sustain.
Competitive Landscape and Leading Strategies
The competitive environment is defined by moderate concentration and high application specialization. The market does not yet belong to a small group of dominant incumbents controlling the entire value chain. Instead, it features a mix of specialized material developers, packaging-focused solution providers, and application engineers that operate across healthcare, construction, energy, and industrial segments. This structure favors companies that can combine material knowledge with vertical-specific go-to-market capability.
Strategic Positioning Among Leading Participants
Several companies illustrate the different ways value is being captured in the current market:
-
Pluss Advanced Technologies has built a presence around PCM solutions for pharmaceutical cold chain and medical temperature-controlled packaging, with product development that emphasizes form-stable organic systems for narrow temperature ranges. Its recent launches highlight a strategy centered on application-specific precision and cold chain reliability.
-
Cryopak continues to focus on temperature-sensitive medical and pharmaceutical shipping, expanding into flexible high-performance packaging with integrated PCM. Its approach demonstrates how packaging design and material integration can be combined to simplify deployment for end users.
-
Cold Chain Technologies and Pelican BioThermal both address biologics and medical device transport through temperature-controlled packaging with PCM-based solutions. Their positioning reflects the importance of trusted supply chains, validation support, and compliance-aware product design in healthcare logistics.
-
PureTemp LLC has focused on bio-based PCMs for medical temperature-sensitive applications and cold chain use, showing how sustainability-oriented materials can align with performance requirements in regulated environments.
-
Rubitherm Technologies and Climator Sweden AB represent European expertise in high-performance PCMs for healthcare and pharmaceutical cold chain, indicating that regional technical reputations can support international commercialization when paired with consistent quality and application support.
-
va-Q-tec AG combines vacuum insulation panel and PCM solutions for temperature-controlled medical transport, an example of hybrid system design that aims to improve overall thermal efficiency rather than relying on PCM alone.
-
Companies such as Microtek Laboratories, Modus Advanced, RGEES, and Sonoco ThermoSafe illustrate the breadth of specialized work occurring across shape-stable gels, medical device integration, custom pharmaceutical packs, and pharmaceutical-grade shipping solutions. Together, they show that differentiation frequently comes from solving a narrow, high-value problem exceptionally well.
Market Evolution Trends
The competitive landscape is likely to evolve along three lines. First, application-led consolidation may accelerate as customers prefer suppliers that can provide integrated solutions rather than standalone materials. Second, vertical specialization will remain powerful because performance, compliance, and service requirements differ so sharply between healthcare logistics, building construction, thermal energy storage, and electronics. Third, new entrants may find opportunity not by competing head-on in established segments, but by targeting underserved temperature windows, novel encapsulation methods, or regional manufacturing advantages. The market is broad enough to reward focused strategies, but unforgiving to undifferentiated ones.
Forward Outlook: Three Trends to Watch
Looking across current data and commercial signals, three trends are likely to shape the market over the next three to five years.
Trend 1: Application-Engineered PCM Systems Will Outperform Standalone Material Sales
The commercial center of gravity is shifting toward engineered systems that combine PCM with packaging, panels, containers, or building components. This matters because end users increasingly evaluate thermal solutions based on installed performance, integration complexity, and operational risk reduction. Companies that design for specific temperature bands, durability requirements, and deployment conditions will be better positioned to capture premium value than those offering generalized materials. The opportunity lies in building repeatable application architectures that can scale across customers without sacrificing performance integrity.
Trend 2: Healthcare and Pharmaceutical Cold Chain Will Remain a High-Value Battleground
Temperature-sensitive medical transport continues to be one of the most demanding and lucrative segments. Biologics, vaccines, diagnostics, and medical devices require reliable temperature control with limited tolerance for deviation. As logistics networks become more complex and product portfolios expand, demand for PCM-based containers, packs, and shipping systems is likely to remain strong. The commercial prize is significant, but so is the scrutiny. Success in this segment will depend on validation documentation, biocompatibility awareness, packaging reliability, and the ability to support customers through qualification and auditing processes.
Trend 3: Energy-Connected Applications Will Grow as Passive Thermal Strategies Gain Traction
In buildings, thermal energy storage, and industrial cooling, phase change materials are increasingly viewed as part of broader energy-management strategies. Where operators seek to reduce peak cooling loads, improve temperature stability, or lower dependency on active systems, PCM can offer a complementary lever. Growth in this direction will depend on proving lifecycle value, streamlining integration, and aligning with evolving energy codes and sustainability expectations. The opportunity is scalable, but it requires credible performance narratives and practical installation pathways.
Risks and Sources of Uncertainty
These trends do not imply smooth expansion. Several sources of uncertainty remain. If performance data remains inconsistent across suppliers, qualification bottlenecks could slow adoption in conservative sectors. If raw material or manufacturing costs rise faster than customers are willing to absorb, price pressure may compress margins in commoditizing segments. If regulatory expectations diverge further across regions or application categories, compliance complexity could raise the barrier to scale. Finally, technology substitution remains a constant risk, particularly if alternative thermal management approaches improve rapidly in cost or convenience. Companies that monitor these risks early and design strategies around them will be better positioned than those that assume growth alone will resolve structural challenges.
Strategic Actions for Decision Makers
The market’s direction is becoming clearer, but the right move depends on where a company sits in the value chain. The following actions are most relevant for the three groups most directly affected.
For Manufacturers and Solution Providers
-
Focus product development on application-ready systems rather than broad material portfolios. Narrow temperature targets, shape stability, encapsulation durability, and integration simplicity often create stronger commercial traction than incremental chemistry improvements alone.
-
Invest in validation, documentation, and compliance readiness early. In regulated segments, the ability to supply repeatable performance data and meet safety or biocompatibility expectations can shorten sales cycles and improve win rates.
-
Build pricing strategy around total installed value, not unit cost. Where PCM reduces energy use, lowers excursion risk, or simplifies logistics, customers are more likely to justify premium pricing when the value case is made explicit.
For Investors and Strategic Backers
-
Evaluate companies on application depth, not just material technology. The most durable advantages often come from combining formulation capability with vertical-specific engineering, regulatory understanding, and customer support.
-
Watch for consolidation patterns in high-stakes segments such as pharmaceutical cold chain and medical transport, where trust, validation, and service networks create natural barriers and acquisition appeal.
-
Assess exposure to regulatory and compliance shifts. Companies that treat compliance as a strategic capability rather than an administrative cost are better positioned to scale across regions and application categories.
For Procurement and End-User Decision Makers
-
Evaluate PCM solutions against operational risk and total cost, not only purchase price. In applications where temperature excursions, energy costs, or system downtime carry significant consequences, performance reliability may outweigh modest upfront savings.
-
Require transparent testing data, degradation expectations, and application-specific qualification support before committing to scale. Incomplete performance evidence is one of the most common sources of project delay.
-
Prioritize suppliers that can support integration, training, and ongoing technical service. Phase change materials often succeed or fail based on how well they are deployed in real systems, not just how they perform in isolation.
Closing Perspective
The phase change material market is no longer defined solely by laboratory promise or narrow specialty use. It is entering a phase where commercial outcomes will be decided by application engineering, compliance capability, validation credibility, and cost-performance balance. Growth to 2032 is likely to be substantial, but the companies and buyers that benefit most will be those who treat PCM as a system-level decision rather than a commodity purchase.
For organizations that need a sharper view of segment-specific sizing, regional dynamics, pricing structures, competitive positioning, and technical requirements, deeper market intelligence can materially improve planning quality. A more detailed research report can help translate these strategic trends into segment-level assumptions, scenario planning, and actionable go-to-market choices. If the objective is to move from broad opportunity to executable strategy, the next step is to ground decisions in granular data tailored to the relevant application, region, and business model.
For detailed analysis of this topic, please visit the official page: Phase Change Material (PCM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com