

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
The Nerve Repair Biomaterial Market: Why 8.2% CAGR Signals 1.4B Shift

The Nerve Repair Biomaterial Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Resilience Meets Complexity
The global nerve repair biomaterial market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $557.7 million in 2020 to an estimated $827.0 million in 2025. This trajectory reflects a compound annual growth rate of 8.2 percent, positioning the sector for continued expansion through 2032 when revenue is projected to reach $1.44 billion. Growth has been underpinned by steady adoption of bioengineered conduits, structured wraps, and advanced connector systems that support peripheral nerve reconstruction following trauma, oncologic resection, and degenerative conditions.
Behind the headline figures lies a more nuanced picture. The market is characterized by moderate concentration, with the top three players accounting for roughly 55 percent of total revenue and the top five capturing close to 72 percent. This structure suggests that scale advantages and proprietary product portfolios remain meaningful barriers to entry, while simultaneously leaving room for specialized innovators who can address specific clinical gaps. The mid-2020s have also brought a period of recalibration, as manufacturers navigate evolving regulatory expectations, reimbursement scrutiny, and surgical workflow integration across diverse procedural settings.
Several structural challenges define the current inflection point. First, clinical heterogeneity across indication types—ranging from sensory nerve gaps to motor nerve discontinuities—creates variability in device performance expectations and complicates head-to-head evidence generation. Second, the regulatory and reimbursement landscape is tightening even as innovation accelerates, placing a premium on robust biocompatibility documentation, ISO 13485 quality systems, and clearly mapped coverage pathways. Third, supply chain maturity for specialized biomaterials remains uneven, with certain polymer and processing components requiring tightly controlled manufacturing environments that can constrain volume scalability.
PW Consulting
Key Growth Drivers: Technology, Policy, Demand, and Cost Structures
Technological progress continues to be the most visible catalyst. Recent clearances highlight a shift from passive scaffolding toward active, workflow-optimized repair systems. In December 2025, regulators approved an expanded biologics license application for an acellular nerve allograft, broadening indications to include sensory, mixed, and motor peripheral nerve discontinuities. That same year, an atraumatic sutureless polymer-based repair system received De Novo authorization for gaps up to 1 cm, signaling growing acceptance of devices that reduce operative time and technical variability. These developments point to a market that increasingly values not only regeneration potential but also ease of use, predictable handling characteristics, and compatibility with minimally invasive surgical practices.
Policy and regulatory dynamics are creating both opportunity and friction. In situ polymerizing peripheral nerve repair devices operate under Class II classification pathways, while biocompatibility evaluation follows established biological evaluation standards. Commercialization typically requires ISO 13485 certification alongside 510(k) clearance or De Novo authorization, which raises the bar for new entrants but also reinforces confidence among operating room teams and procurement committees. Reimbursement structures are aligning with specific procedural codes that cover nerve repair using synthetic conduits or vein allografts for both commercial and Medicare populations. Together, these frameworks create a clearer route to market for well-documented devices, while also demanding disciplined evidence generation and health economic positioning.
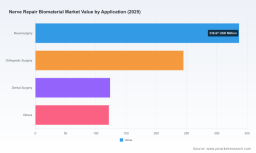
Demand-side changes are reshaping utilization patterns across surgical disciplines. Neurosurgery remains a dominant application area, supported by increasing procedural volume in peripheral nerve reconstruction and a growing willingness to intervene earlier in cases of compressive or traumatic neuropathy. Orthopedic surgery continues to drive meaningful volume through nerve injury management associated with joint and soft tissue procedures. Dental surgery and other specialized procedural areas contribute additional growth, often benefiting from smaller-diameter constructs and application-specific handling profiles. Across these settings, surgeons are prioritizing devices that offer consistent luminal dimensions, predictable deployment, and reduced reliance on complex microsurgical steps, which is steering purchasing decisions toward clinically differentiated product lines.
Cost and supply chain considerations are becoming more prominent as manufacturers scale and as hospitals scrutinize implant economics. The production of acellular matrices, scaffolds, and polymer-based guides involves controlled processing, sterilization, and storage requirements that can influence total landed cost. At the same time, value analysis committees are weighing not only unit price but also operating room efficiency, revision rates, and training burden. Companies that can demonstrate integrated workflows, stable inventory availability, and clear procedural benefits are better positioned to defend pricing and expand adoption.
Competitive Landscape and Leading Strategies
The market’s leading participants are pursuing distinct strategic positions that reflect their technological heritage and procedural focus. Several established players are emphasizing acellular allografts and complementary connector and protector portfolios, leveraging expanded indications to deepen presence across sensory and motor applications. Others are anchored in nerve guides and protector lines that address gap management and surrounding tissue protection, often paired with surgeon education and procedural support programs. A subset of innovators is differentiating through sutureless or minimally traumatic repair concepts, aiming to simplify handling and shorten case time while maintaining structural integrity during the critical healing window.
Strategic differentiation is increasingly multidimensional. Product architecture matters, but so does the alignment with surgical workflow. For example, devices designed to integrate smoothly into existing microsurgical or minimally invasive routines can reduce adoption friction, especially when accompanied by targeted training and in-service support. Regulatory readiness also functions as a competitive moat; organizations with mature quality systems and a track record of successful clearances are better equipped to iterate product families, pursue indication expansions, and respond to emerging clinical needs. Reimbursement alignment further enhances commercial resilience, as coverage clarity reduces purchasing uncertainty for both large health systems and ambulatory settings.
The competitive landscape is evolving along several axes. Incumbents with broad portfolios are seeking to consolidate clinical positioning by linking core repair products with complementary protective and connective devices, thereby increasing per-case relevance and strengthening relationships with surgical teams. Smaller, technology-focused entrants are introducing differentiated mechanics or material designs that address specific gap lengths, handling sensitivities, or procedure types. At the same time, consolidation dynamics are plausible where larger organizations seek to acquire specialized capabilities, expand into adjacent procedural segments, or accelerate access to novel polymer and processing platforms. The net effect is a market that rewards both clinical differentiation and commercial execution, with winners likely to be those that can combine credible evidence, workflow fit, and reliable supply.
Recent regulatory milestones illustrate how strategy and timing intersect. The expanded clearance for an acellular allograft broadened its addressable use cases and reinforced a biologic-centric positioning, while the De Novo authorization for a sutureless system introduced a differentiated repair modality for short gaps. These milestones do not merely reflect product-level achievements; they signal to the broader field where regulatory tolerance, clinical interest, and surgeon receptivity are converging. Competitors and new entrants alike are likely to calibrate their development roadmaps in response, prioritizing indication coverage, handling simplicity, and documentation rigor.
Forward-Looking Trends: Where Value Is Likely to Emerge
Over the next three to five years, one of the most consequential trends will be the continued broadening of indication pathways paired with differentiated device architectures. As regulatory frameworks accommodate expanded use across sensory, mixed, and motor discontinuity scenarios, and as sutureless or atraumatic options gain traction for short gaps, the market is likely to segment more precisely by gap length, tissue type, and procedural setting. This segmentation opens the door to targeted product strategies, with opportunity for manufacturers to build family-based portfolios that address multiple clinical scenarios without diluting focus.
A second trend is the growing emphasis on operating room efficiency and procedural standardization. Surgeons and health systems are increasingly weighing handling characteristics, deployment reproducibility, and training requirements alongside regenerative performance. Devices that reduce technical variability, shorten setup and repair time, and integrate with established surgical sequences can gain adoption advantage even when technical specifications appear similar on paper. This dynamic favors companies that invest in user-centric design, procedural education, and consistent quality across production lots.
A third trend concerns the tightening interplay between evidence, coverage, and procurement. Reimbursement codes are available for specific conduit and allograft-based repair approaches, but coverage decisions and value analysis expectations are becoming more granular. Manufacturers that can articulate not only clinical performance but also procedural value—lower revision potential, smoother learning curves, predictable inventory needs—will be better positioned to sustain adoption and pricing. Health economic framing is likely to become a standard element of commercialization rather than a post-market afterthought.
These trends carry commercial opportunity, but they also introduce uncertainty. Regulatory pathways and coverage policies can evolve unevenly across jurisdictions and payers, which may affect timing and breadth of adoption. Material supply and processing complexity can limit scalability if not managed proactively, especially for advanced constructs that rely on tightly controlled manufacturing. In addition, competition may intensify as new entrants attempt to target niche gap lengths or procedural conditions, potentially compressing margins in specific sub-segments. Organizations planning multi-year investments should therefore balance optimism about demand growth with disciplined scenario planning around regulation, reimbursement, and manufacturing readiness.
Strategic Actions for Decision-Makers
For manufacturers and product developers, the priority is to align innovation with procedural reality and regulatory clarity. Building product families that span complementary repair, connection, and protection functions can strengthen per-case relevance and reduce the risk of isolated-item commoditization. At the same time, early attention to biocompatibility documentation, quality system maturity, and coverage mapping can shorten the path from concept to sustained commercialization. Companies should also evaluate whether their manufacturing footprint and supply resilience support consistent availability, since procurement committees increasingly view reliability as part of value rather than a separate operational concern.
For investors, the market’s growth profile argues for selective exposure to platforms with clear differentiation and defensible execution. Due diligence should focus on indication coverage, evidence strategy, regulatory readiness, and the ability to convert procedural efficiency into adoption. Particular attention is warranted for technologies that either expand usable clinical scenarios for existing product classes or introduce meaningful surgical workflow advantages, provided the company also demonstrates credible reimbursement alignment and scalable operations. Given the moderate concentration in the market, there may also be value in tracking partnerships, acquisition signals, and capability-accretion moves that could reshape competitive positions over time.
Worldwide Peripheral Nerve Stimulators Market
For procurement leaders and clinical decision-makers, the emphasis should be on total procedural value rather than device price alone. Evaluation criteria should include handling consistency, deployment reliability, training burden, inventory stability, and the strength of supporting documentation. Where feasible, institutions can benefit from structured surgeon education, case-based feedback loops, and value analysis frameworks that account for operating room time, revision risk, and downstream resource use. Aligning purchasing decisions with the products that best match local procedural mix can improve outcomes while managing cost risk.
Worldwide Soft Tissue Repair Mesh Market
As the market expands toward a projected $1.44 billion revenue level by 2032, the volume of strategic decisions will only increase. Detailed segmentation data, company-specific capability mapping, and customized scenario analysis can materially improve planning quality for organizations operating across product development, investment, and procurement functions. Readers seeking a deeper dive into regional dynamics, application-by-application trajectories, supplier-level benchmarking, and tailored strategic recommendations are encouraged to review the full PW Consulting report, where the underlying data set and segmentation detail support more precise decision-making.
For detailed analysis of this topic, please visit the official page: Nerve Repair Biomaterial Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com