

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electric Parking Brake Market: Why 9.4% CAGR and 2026–2032 Forecast Shift Supplier Strategy

The Electric Parking Brake Market: Strategic Shifts and Commercial Opportunities Through 2032
The electric parking brake market has transitioned from a mechanical convenience to a core component of vehicle safety architecture and electronic control systems. Valued at approximately 215 million USD in 2025, the market has expanded steadily from 163.15 million USD in 2020, reflecting a compound annual growth rate of 9.4 percent across the 2026-2032 forecast horizon. By 2032, revenue is projected to reach 344.8 million USD, driven by the broader electrification of vehicle platforms, stricter safety mandates, and the integration of parking brake functions into advanced driver assistance and 자율 주행 capability stacks. This growth trajectory is not merely a function of vehicle volume; it reflects a structural shift in how braking, hold functionality, and vehicle dynamics are engineered, regulated, and monetized.
PW Consulting
Three structural dynamics define the current market environment. First, the industry is navigating the transition from cable-pull and electro-hydraulic architectures toward full electric drive-by-wire and electro-mechanical brake systems, a shift that redefines supplier capabilities, validation requirements, and cost curves. Second, regulatory frameworks are tightening around fail-safe performance, holding force, and friction-type emergency stopping functionality, forcing both OEMs and tier suppliers to redesign systems that can meet FMVSS 135 and equivalent global standards while preserving packaging and weight advantages. Third, the value chain is under pressure from localization ambitions and component ecosystem maturity, particularly in emerging production hubs where sourcing strategies are being recalibrated to balance cost, flexibility, and qualification timelines.
For decision-makers, the implication is clear: electric parking brake strategy is no longer a component-level purchasing decision. It is a platform-level choice that affects vehicle architecture, safety case validation, supply chain resilience, and the ability to support hybrid, electric, and autonomous-capable vehicle programs. The following analysis examines the drivers reshaping the market, the competitive positioning of leading suppliers, the trends likely to define the next three to five years, and the strategic actions that manufacturers, investors, and procurement teams should prioritize.
Key Drivers Reshaping the Electric Parking Brake Market
Technology Innovation and the Move Toward By-Wire and Smart Actuation
The most consequential technical shift in the electric parking brake space is the progression from mechanically linked cable-pull systems toward electro-hydraulic caliper integration and, increasingly, full electric drive-by-wire and electro-mechanical brake architectures. Cable-pull systems remain prevalent in cost-sensitive and legacy platforms, but the revenue mix is tilting toward caliper-integrated and by-wire solutions as OEMs seek tighter integration with stability control, regenerative braking, and auto-hold intelligence. The evolution is not simply about removing a cable; it is about embedding the parking brake function within a broader electronic brake system that can execute software-defined behaviors, support fail-operational requirements, and enable diagnostic telemetry that feeds into vehicle health monitoring and predictive maintenance.
Recent product and production activity illustrates the pace of this transition. In mid-2025, Hitachi Astemo introduced its electro-mechanical brake-by-wire system, branded as Smart Brake, at North American industry showcases, signaling the commercialization path for systems that combine parking brake hold with brake-by-wire capability. Around the same period, Robert Bosch GmbH launched a new electric parking brake system designed specifically for hybrid vehicles, reflecting the need to manage hold and braking behavior across internal combustion, electric drive, and blended torque conditions. On the commercial side, ZF Friedrichshafen AG commenced production of its EPB system at a new Oragadam facility near Chennai in India, while also securing a large order for electro-mechanical brake and by-wire technology equipping nearly 5 million vehicles earlier in the year. These moves collectively indicate that by-wire and smart actuator platforms are moving from technology demonstration into volume production, with suppliers investing in regional capacity and platform-specific designs.
For manufacturers and platform planners, the strategic question is how to sequence architecture transitions without over-committing to a single technical path. The market is not converging on one solution overnight; rather, it is bifurcating between cost-optimized electro-mechanical implementations for high-volume passenger and light commercial platforms and premium, software-intensive brake-by-wire stacks for hybrid, electric, and advanced safety-focused programs. This creates an opportunity for suppliers that can offer modular, software-upgradable platforms and for OEMs that can align vehicle segmentation with the appropriate brake architecture.
Policy and Regulatory Environment as a Design and Validation Constraint
Regulatory requirements are increasingly shaping EPB design beyond basic functionality. In the United States, FMVSS 135 requires parking brakes, including electric variants, to meet holding force and fail-safe criteria that ensure performance under varying vehicle load and slope conditions. The standard also stipulates that parking brakes be of a friction type to preserve emergency stopping functionality. Similar expectations exist in other major markets, and the practical effect is that EPB systems must be validated not only for routine hold and release but also for fault tolerance, degradation modes, and emergency scenarios. This elevates the importance of system-level engineering, sensor reliability, actuator redundancy, and diagnostic coverage.
The regulatory environment is also interacting with the broader safety and autonomy agenda. As vehicles incorporate higher levels of driver assistance and automated functionality, the parking brake and broader braking system become part of the safety case for features such as auto-hold, hill start assistance, and low-speed maneuvering under electronic control. Suppliers that can demonstrate fail-operational behavior, AI-enabled diagnostics, and intelligent actuator control are better positioned to support these use cases. Bosch’s positioning around autonomous-grade EPB meeting fail-operational requirements and AI-enabled diagnostics, for example, reflects a strategy that ties parking brake capability to higher-value safety and autonomy enablers rather than treating it as an isolated convenience feature.
Industrial Brakes Market
The commercial implication is twofold. First, validation and compliance costs are rising, which favors suppliers with established safety engineering pipelines and OEMs that can amortize these costs across platforms. Second, regulatory alignment creates a barrier to rapid, low-cost re-badging of components across regions, because performance criteria, testing protocols, and approval pathways differ. Companies that localize engineering and validation capabilities, rather than only assembly, will be better equipped to manage time-to-market and certification risk.
Demand-Side Changes: Electrification, Safety Expectations, and Feature Integration
Demand for electric parking brake systems is being reshaped by three interrelated consumer and enterprise behaviors. The first is the continued electrification of vehicle fleets, including hybrid and battery-electric platforms, where parking brake functionality must coordinate with regenerative braking, high-voltage safety states, and drive-away readiness. Hybrid-specific EPB designs, such as the system Bosch launched in September 2025, illustrate how demand is becoming platform-specific rather than generic. The second is rising consumer and fleet expectation for safety, convenience, and seamless driver experience, which translates into stronger adoption of auto-hold, hill hold, and integrated stability functions that depend on reliable EPB actuation. The third is the growing relevance of EPB in light and heavy commercial vehicles, where hold functionality, load conditions, and operational safety on inclines and during docking and stop-and-start cycles create distinct performance requirements.
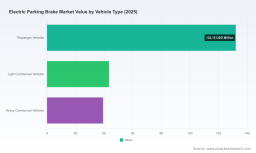
The passenger vehicle segment remains the largest demand pool, but commercial vehicles are an important growth vector because the performance bar is higher and the differentiation from mechanical systems is more operationally meaningful. In heavy commercial applications, for instance, the ability to maintain hold under variable loads and to integrate with vehicle stability and brake systems can influence both safety outcomes and total cost of ownership. Suppliers that can adapt EPB solutions across passenger and commercial segments while addressing different load, duty-cycle, and packaging constraints are well positioned to capture cross-platform demand.
Supply Chain and Cost Structure Dynamics
Cost structure and sourcing strategy are becoming as important as technical performance in the EPB market. A notable dynamic is the push toward regionalization and local content. In India, for example, approximately 40 percent of EPB components are currently sourced from local suppliers, with plans to increase local content to 80-90 percent within two years. This reflects a broader industry intent to reduce logistics cost, mitigate geopolitical and logistics risk, and align with local production incentives. However, the same analysis points to a limitation: the lack of a localized manufacturing ecosystem for EPB components in India results in increased costs and supply chain flexibility constraints. In other words, the ambition to localize is real, but the component-level supply base is still maturing, and that gap affects lead times, qualification cycles, and the ability to scale flexibly.
This tension between localization ambition and ecosystem readiness is a defining cost-and-risk dynamic. It means that near-term savings from local assembly can be partially offset by import dependence for critical subcomponents, tooling lead times, and the cost of qualifying new local sources. For suppliers, the opportunity lies in building component ecosystems, sharing design and process knowledge, and structuring partnerships that improve local content without compromising quality or validation timelines. For OEMs, the practical task is to balance localization targets with supply assurance, particularly for safety-critical braking components where qualification rigor and fault-tolerance requirements are non-negotiable.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Suppliers
The electric parking brake market is moderately concentrated, with the top three suppliers accounting for approximately 24.6 percent of revenue and the top five reaching roughly 26.2 percent. This concentration suggests a market in which incumbent suppliers hold strong positions through platform breadth, safety credentials, and long-standing OEM relationships, while there remains room for specialists and regional players to compete on specific architectures, cost points, and integration services. Several companies illustrate distinct strategic plays.
Electric Brake Booster Market
ZF Friedrichshafen AG has built a broad EPB footprint spanning motor-on-caliper and electro-mechanical systems, with a track record of large-scale production and modular offerings for passenger cars and commercial vehicles. Its recent activities underscore a dual strategy of regional expansion and technology scale-up: production start in India, a major order win for electro-mechanical brake and by-wire technology covering nearly 5 million vehicles, and continued investment in modular EPB platforms. The strategic takeaway is that scale, platform modularity, and regional manufacturing capacity can reinforce each other, especially when paired with large order wins that anchor long-term demand.
Continental AG has positioned around smart actuator control, auto-hold intelligence, and regenerative braking integration, with a focus on hybrid and EV platforms. This aligns with the broader trend of embedding parking brake functionality into electrified brake behavior rather than treating it as a standalone function. Robert Bosch GmbH, with a share above 13 percent, has emphasized autonomous-grade EPB meeting fail-operational requirements and AI-enabled diagnostics, a strategy that ties braking safety and diagnostics to higher-value vehicle capabilities. Aisin Seiki, Hitachi Astemo, and Brembo each provide complementary angles: Aisin and Hitachi Astemo offer actuator kits and brake-by-wire-capable systems for OEM integration, while Brembo focuses on actuator and caliper-integrated systems and has partnered with Lucid to supply brake calipers integrated with EPB for the Lucid Gravity SUV.
The Korean suppliers add a further dimension. Hyundai Mobis emphasizes localized production and integration with vehicle stability systems, while Mando Corporation focuses on modular and software-upgradable platforms. These approaches reflect a pragmatic response to regional cost structures and OEM integration preferences, and they indicate that localization and software-defined upgradability are becoming competitive levers, not just operational tactics. Akebono Brake Industry and Kuster Holding round out the field with specialist positions in actuators, calipers, and EPB components for passenger and commercial applications, illustrating that niche expertise can remain relevant where performance or application specificity matters.
How the Landscape Is Evolving
Several evolution patterns are visible. First, differentiation is shifting from purely mechanical capability to system intelligence: auto-hold behavior, regenerative coordination, diagnostics, fail-operational design, and software-defined features are increasingly part of the value proposition. Second, regional production is expanding, but the supply base for critical components is still catching up, creating a window for suppliers that can bridge global design standards with local execution. Third, partnerships and program wins are becoming strategic signals: collaborations around brake-by-wire platforms, EV and hybrid programs, and large-volume orders indicate where by-wire and integrated EPB architectures are gaining traction. The market is not consolidating into a single dominant model; instead, it is fragmenting by platform type, region, and performance tier, with suppliers competing on architecture flexibility, safety credentials, and the ability to support both volume and premium segments.
Future Trends and Commercial Opportunities (2026-2032)
Trend 1: Accelerated Adoption of Electro-Mechanical and By-Wire Brake Platforms
Over the next three to five years, electro-mechanical and brake-by-wire platforms are likely to capture a growing share of EPB-related value, particularly in hybrid, electric, and safety-focused vehicle programs. The rationale is structural: these architectures enable tighter integration with vehicle dynamics, regenerative braking, auto-hold, and automated functions, while also providing a path to software-defined behavior and diagnostics. Commercial opportunities will arise for suppliers that can offer modular platforms spanning multiple vehicle segments, for OEMs that can align platform segmentation with brake architecture choices, and for service and diagnostics businesses that can monetize telemetry and predictive maintenance tied to brake system health.
The associated risk is execution complexity. By-wire and electro-mechanical systems require more extensive validation, fault-tolerance design, and calibration effort, and the cost of changeovers can be significant if architecture decisions are made too late or too broadly. Companies that sequence investments by segment and region, rather than attempting a single wholesale transition, are more likely to manage both cost and time-to-market risk.
Trend 2: Regulatory-Driven Safety and Diagnostics as a Competitive Differentiator
Regulatory requirements for holding force, fail-safe performance, and friction-type emergency stopping will continue to shape system design, and the bar is likely to rise as vehicle automation and advanced safety features become more common. This creates a competitive divide between suppliers that can deliver robust safety cases, fail-operational behavior, and AI-enabled diagnostics, and those that compete primarily on cost without equal safety engineering depth. Commercial opportunities include safety-certification partnerships, diagnostic services, and platform designs that can be adapted across regions while meeting multiple regulatory regimes. The uncertainty lies in how quickly standards and testing expectations evolve, and in the cost of maintaining compliance across multiple markets with different approval pathways.
Trend 3: Regionalization with Ecosystem Maturity Gaps
The push to localize production and increase local content will continue, but the pace will be uneven because component ecosystems are not yet fully mature in several key regions. Where localization succeeds, it can reduce logistics exposure and improve responsiveness; where it outpaces ecosystem readiness, it can increase cost and limit flexibility. Commercial opportunities will favor suppliers and OEMs that invest in component-level localization, joint development with local sources, and qualification pipelines that shorten the path from design to approved local supply. The strategic risk is over-committing to local content targets before the supply base can support them, which can create qualification bottlenecks and cost inflation.
Strategic Actions for Decision-Makers
For Manufacturers and Tier Suppliers
Align brake architecture decisions with platform strategy rather than treating EPB as a standalone commodity. Where hybrid, electric, and software-defined features are central, prioritize electro-hydraulic and by-wire-capable platforms that support regenerative coordination, auto-hold intelligence, and diagnostics. Where cost and volume dominate, cable-pull and motor-on-caliper solutions may remain appropriate for a defined segment of the portfolio, but the transition path should be planned. Invest in modular, software-upgradable designs where possible, because they provide flexibility across vehicle generations and reduce the cost of future feature additions. Equally important, build or partner for localized component capability where production is expanding, so that localization targets do not outpace ecosystem readiness and create qualification delays.
For Investors
Focus on suppliers whose value proposition is tied to system intelligence, safety credentials, and platform breadth rather than on component cost alone. The market’s growth is increasingly linked to by-wire adoption, hybrid and EV integration, and regulatory-driven safety and diagnostics capability. Evaluate regional production plans against component ecosystem maturity, because localization can be a genuine advantage or a near-term cost trap depending on the readiness of local sources. Monitor program wins and partnerships as indicators of where by-wire and integrated EPB architectures are gaining traction, but validate them against qualification timelines, regional content assumptions, and the supplier’s ability to support fail-operational and diagnostic requirements.
For Procurement and OEM Planning Teams
Treat EPB sourcing as a platform-level decision with safety, validation, and supply chain implications. Evaluate suppliers not only on unit cost but also on fail-safe design, diagnostic coverage, auto-hold and regenerative integration capability, and the ability to support multiple regulatory regimes. Where regional production is planned, assess the maturity of local component sources and the qualification pathway, because localized assembly alone may not deliver the intended flexibility or cost improvement if critical subcomponents remain import-dependent. Consider multi-source and modular-platform strategies where feasible, to balance cost, supply assurance, and the ability to adapt to changing vehicle programs and safety requirements.
The electric parking brake market is entering a phase in which technical architecture, regulatory compliance, and regional supply chain design are inseparable from commercial performance. With the market projected to expand from roughly 215 million USD in 2025 to 344.8 million USD by 2032 at a 9.4 percent CAGR, the winners will be those who can align component strategy with platform roadmap, safety case, and localization reality simultaneously. Detailed segmentation data, regional dynamics, supplier benchmarking, and program-level scenario analysis can sharpen these decisions further, and the full research report provides the structured detail needed to translate these trends into specific action plans for individual portfolios and programs.
For detailed analysis of this topic, please visit the official page: Electric Parking Brake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com