

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Pharmaceutical Equipment Market: Why 7.5% CAGR and Regional Shifts Change Everything

Navigating the Pharmaceutical Equipment Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global pharmaceutical equipment market is entering a phase of sustained, structurally driven expansion. Valued at approximately USD 169.3 million in 2025 , the sector is projected to reach USD 279.8 million by 2032 , translating to a compound annual growth rate of 7.5% across the 2026–2032 forecast window. This trajectory follows a consistent upward march from USD 120.45 million in 2020 , reflecting a market that has not merely recovered from supply chain disruptions but has fundamentally upgraded its operational baseline. Growth is no longer episodic; it is being embedded into capacity planning, compliance infrastructure, and technology adoption cycles. For executives and investors, the central question has shifted from whether demand will hold to which segments, geographies, and strategic positions will capture disproportionate value as the market matures.
Behind the headline figures lies a more complex reality. The sector is navigating a convergence of heightened regulatory stringency, rapid automation mandates, and divergent regional capacity builds. Companies that treat equipment procurement as a purely tactical capital expenditure are increasingly exposed to bottlenecks in validation, integration, and lifecycle support. Conversely, organizations that align equipment strategy with broader manufacturing resilience and compliance roadmaps are positioning themselves to scale output without proportional increases in risk or overhead. The following analysis unpacks the structural drivers, competitive dynamics, and forward-looking shifts that will define commercial decision-making over the next several years.
PW Consulting
Market Landscape: Growth Trajectory and Structural Headwinds
A Market Accelerating on Consistency, Not Spikes
The expansion pattern from 2020 through 2025 demonstrates a market that has moved past recovery-mode volatility and settled into a more predictable, demand-led cadence. Year-over-year progression has been steady, with each successive period adding meaningful increments to the base. This consistency matters strategically: it signals that procurement cycles are lengthening, validation timelines are being planned further in advance, and capital allocation is increasingly tied to multi-year capacity roadmaps rather than reactive 주문을. A 7.5% CAGR over the coming seven years implies that the market will roughly double in scale, a rate that outpaces many broader industrial equipment categories and reflects the specific weight of compliance-driven capital renewal and throughput upgrades.
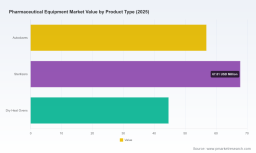
The revenue composition also reveals where operational priorities are crystallizing. Oral solid dosage processing, blending and mixing operations, and separation technologies continue to anchor core production workflows, while sterilization and controlled-environment equipment underscore the non-negotiable nature of contamination control. These categories are not competing for the same budget pools; they are complementary layers of a modern manufacturing stack. As facilities seek to reduce changeover times, improve batch consistency, and meet increasingly granular audit expectations, the integration of these functional units into cohesive lines is becoming a competitive differentiator rather than a convenience.
The Three Critical Junctures Shaping the Next Cycle
First, regulatory qualification is no longer a post-purchase formality; it is a design constraint. Equipment that cannot be seamlessly documented through installation, operational, and performance qualification protocols introduces schedule risk and audit exposure. The industry context confirms that major regulatory frameworks continue to reinforce a documented qualification lifecycle with pre-defined acceptance criteria, making validation readiness a procurement prerequisite rather than an afterthought. This shifts bargaining power toward suppliers who can provide traceable documentation packages, modular calibration architectures, and lifecycle support that extends well beyond delivery.
Second, the tension between throughput ambitions and quality assurance is intensifying. High-output automation promises faster cycle times and lower per-unit costs, but it also compresses the margin for error. Facilities operating at higher speeds must demonstrate that process controls, in-line inspection, and environmental monitoring hold steady under continuous load. The commercial implication is clear: equipment that enables speed without compromising verifiable quality will command premium positioning, while solutions that trade one for the other will face increasing resistance during technology transfer and scale-up reviews.
Third, geographic capacity distribution is rebalancing. While established markets continue to upgrade existing lines and consolidate upstream processing, emerging manufacturing hubs are expanding foundational infrastructure at a pace that reshapes where procurement dollars flow. This divergence creates a bifurcated demand environment: mature regions prioritize modernization, compliance harmonization, and line integration, while newer capacity centers focus on core equipment deployment, operator training, and foundational qualification. Suppliers that can tailor deployment models, documentation depth, and after-sales support to these distinct profiles will capture broader share than those applying a uniform go-to-market approach.
Core Drivers Reshaping Demand and Investment Logic
Technology Innovation as a Throughput-and-Compliance Multiplier
Equipment design is increasingly converging around three technical imperatives: precision dosing and blending repeatability, closed or semi-closed processing to limit cross-contamination, and modular architectures that simplify changeovers and qualification. rotary tablet presses, fluid bed systems, and advanced encapsulation platforms are being engineered to sustain high output while reducing variability in critical quality attributes. At the same time, sterilizers, dry heat ovens, and autoclave systems are being refined to shorten cycle times without sacrificing thermal uniformity or documented process control. These innovations are not incremental; they directly affect batch release cadence, rework rates, and the cost of quality, making equipment selection a lever for both capacity and margin improvement.
The commercial ripple is significant. Manufacturers are increasingly evaluating total cost of ownership through the lens of validation effort, line integration complexity, and lifecycle service availability rather than sticker price alone. Equipment that arrives with pre-validated subsystems, clear user requirement specification alignment, and documented acceptance pathways reduces the hidden costs of commissioning. In practical terms, this means that suppliers offering engineered interoperability, standardized documentation packages, and predictable uptime profiles are gaining preference in competitive evaluations, even when upfront pricing is not the lowest.
Regulatory Tightening as a Catalyst for Capital Renewal
Policy and guidance continue to raise the floor for equipment qualification and process control. Across major jurisdictions, expectations around documented qualification lifecycles, calibration discipline, cleaning verification, and pre-defined acceptance criteria have become deeply embedded in good manufacturing practice frameworks. The direction is not toward more paperwork for its own sake; it is toward verifiable consistency that can withstand regulatory review and internal audit scrutiny. For equipment buyers, this environment favors platforms that are designed with qualification in mind from the outset, including accessible instrumentation, traceable configuration records, and service intervals that align with compliance calendars.
This regulatory rhythm also influences renewal timing. Facilities that originally commissioned equipment under less stringent expectations increasingly find that retrofitting or supplementing legacy lines is more disruptive than planned upgrades. As a result, capital cycles are being synchronized with compliance strategy: organizations are choosing to replace or augment equipment not only when output demands it, but when validation burden, audit findings, or process variability make continuation uneconomical. This dynamic supports the broader growth outlook while shifting the purchase trigger from pure volume expansion to a combined quality-and-capacity rationale.
Demand-Side Shifts in Manufacturing Footprints and Product Mix
On the demand side, product portfolios are diversifying in ways that stress equipment flexibility. The continued emphasis on oral solid dosage forms keeps tableting, blending, and encapsulation lines busy, but there is also growing interest in formats that require careful handling, controlled environments, or rapid line reconfiguration. At the same time, manufacturing footprints are being rethought in response to supply chain risk, regional incentive programs, and the desire to shorten time-to-market for key therapeutic categories. The result is a broader set of buyer priorities: not just throughput, but agility, documentation readiness, and the ability to run smaller, higher-value batches with minimal disruption.
Behaviorally, procurement teams are becoming more deliberate. Longer lead times for integrated lines, more complex qualification coordination, and greater internal expectations for lifecycle reliability are pushing buyers to involve engineering, quality, and operations earlier in the selection process. This multi-stakeholder buying cycle favors suppliers who can demonstrate process understanding, provide realistic deployment timelines, and offer post-installation support that addresses operational learning curves. Equipment that appears competitive in a spec sheet but underperforms in commissioning or operator onboarding is increasingly filtered out before final selection.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by energy efficiency expectations, component availability, and the economics of integration. Energy-intensive thermal and sterilization equipment is under greater scrutiny, pushing suppliers and buyers alike to evaluate cycle optimization, insulation performance, and control precision as cost levers rather than mere technical specifications. At the same time, the cost of integration—engineering alignment, qualification documentation, and startup support—is becoming a larger share of total project spend. This has two strategic consequences: first, buyers are more willing to pay for reduced integration risk; second, suppliers that bundle deployment, training, and documentation into a coherent package can differentiate on total project predictability rather than discrete hardware pricing.
Supply chain stability also matters more than before. Components that affect calibration stability, sealing integrity, or control reliability can create cascading delays if unavailable at the right specification. The implication for the market is a gradual preference for equipment architectures that reduce single-point dependencies, simplify spare parts management, and allow phased commissioning when full-line delivery is constrained. In an environment where production schedules are tightly linked to commercial commitments, resiliency in equipment design and supplier support becomes a direct contributor to revenue assurance.
Competitive Dynamics: Positioning, Differentiation, and Market Evolution
How Leading Players Are Composing Their Advantage
The competitive landscape is anchored by firms that have built capabilities across processing, filling, and packaging, but their strategic emphasis differs in ways that matter for buyers and investors. German and Italian engineering-origin companies tend to lean into integrated line architecture, high-speed automation, and documentation rigor that aligns with demanding regulatory environments. Their value proposition often centers on end-to-end consistency: conveying, filling, sealing, and packaging units designed to operate as a coordinated system with shared control logic and streamlined qualification pathways. This integration advantage reduces interface risk and can shorten commissioning timelines when lines are scoped holistically rather than assembled from disparate vendors.
Worldwide Pharmaceutical Equipment Maintenance Services Market
At the same time, firms with strong positions in oral solid dosage equipment emphasize throughput precision, batch repeatability, and modular flexibility for tableting, blending, encapsulation, and coating workflows. Their differentiation frequently lies in maintaining tight control over critical processing parameters while enabling changeovers that do not destabilize quality attributes. Suppliers with specialized strength in liquid handling, vial filling, and bio-processing platforms add another layer of relevance by addressing products that require aseptic discipline, closed processing, and sensitive containment. In practice, this segmentation means that competitive advantage is increasingly defined by how well a company can match a specific product risk profile with the right combination of mechanical precision, environmental control, and documentation support.
Strategic positioning also extends to how companies engage with customers beyond the sale. Trade presence, technical forums, and application-focused demonstrations have become important channels for communicating capability in context rather than in isolation. Participation in industry events allows suppliers to showcase line integration concepts, sanitation-friendly designs, and high-output automation in front of buyers who are actively comparing configuration options. For the market overall, this shifts competition toward proven applicability: the ability to show how equipment behaves under realistic batch sizes, changeover patterns, and qualification expectations becomes a stronger deciding factor than brochure performance alone.
Market Structure: Consolidation Pressure and Segment Differentiation
Concentration in the sector suggests that a relatively small group of large players commands a substantial share of revenue, yet the market remains open enough for specialized entrants and regional specialists to compete on configuration, responsiveness, and application fit. This combination is creating two simultaneous pressures. First, larger players are incentivized to deepen integration across processing and packaging to capture the premium associated with reduced interface risk and more predictable qualification outcomes. Second, smaller or regionally focused firms are finding room by offering highly tailored solutions, faster local support, or cost-competitive configurations for specific dosage forms and facility types. The practical outcome is a market that is not simply consolidating into a single model, but differentiating into tiers of capability that serve distinct risk and budget profiles.
Evolution is also being shaped by how buyers allocate projects. Integrated, multi-unit lines tend to favor suppliers with broad portfolios and robust service networks, while point-solution purchases—such as a single tablet press, a blender upgrade, or a sterilization unit—can be won on application expertise, lead-time reliability, and documentation fit. This dual structure means that competitive success increasingly depends on both breadth and depth: the ability to propose a cohesive architecture when needed, and the credibility to deliver a focused solution when that is the smarter choice. Over time, this will likely encourage partnerships, selective acquisitions, and service expansions that widen each player’s effective footprint without requiring every vendor to own every capability end to end.
Forward Outlook: Three Trends That Will Shape 2027–2032
Trend 1: Qualification-by-Design Becomes a Default Expectation
Over the next several years, equipment that is designed with qualification documentation, calibration accessibility, and acceptance criteria traceability embedded into its architecture will move from preferred to expected. As audit scrutiny persists and internal quality systems mature, the cost of retrofitting documentation or reworking qualification packages will increasingly outweigh any upfront savings from less-prepared platforms. Commercial opportunity lies in solutions that reduce the friction of installation qualification, operational qualification, and performance qualification through standardized protocols, clear user requirement alignment, and service models that maintain compliance readiness across the lifecycle. Buyers who plan qualification timelines alongside equipment selection will compress project risk; suppliers who deliver that alignment will capture preference in contested evaluations.
Trend 2: High-Speed, High-Containment Lines Will Redefine Throughput Economics
The push for higher output will continue, but the definition of success is broadening to include containment integrity, inspection reliability, and minimal deviation under sustained load. Lines that combine fast cycle times with robust environmental control and in-line verification will offer a more defensible economics case than speed alone. This trend opens opportunities for vendors that can demonstrate how automation, vision inspection, and controlled processing work together to maintain quality at scale. It also raises risk for solutions that chase throughput without equivalent controls, since scale-up failures and batch variability can erase apparent efficiency gains.
Trend 3: Regional Diversification Will Create Tiered Procurement Patterns
As manufacturing capacity spreads across more regions, procurement behavior will increasingly reflect local priorities: foundational equipment deployment in newer hubs, and modernization, integration, and compliance harmonization in established markets. This will produce a tiered market in which the same functional category may be evaluated under different criteria depending on facility maturity, regulatory exposure, and operator experience. The strategic opportunity is to match deployment models—documentation depth, training intensity, spare parts logistics, and on-site support—to the specific context rather than assuming a one-size approach. The associated risk is misalignment: offering a highly integrated, documentation-heavy solution in a setting that prioritizes rapid deployment and affordability, or vice versa, can weaken commercial outcomes even when the equipment itself is sound.
Strategic Actions for Decision-Makers
For Manufacturers and Business Leaders
- Treat qualification readiness as a procurement gate. Evaluate equipment against documentation traceability, calibration access, and acceptance-criteria clarity early in the selection process to reduce commissioning risk and audit exposure.
- Prioritize integration over isolated spec optimization. Where feasible, scope processing, filling, and packaging as a coordinated system to minimize interface gaps, shorten validation coordination, and improve line predictability.
- Plan capacity expansion around product risk profiles. Align equipment type and automation level with the containment, inspection, and environmental requirements of the specific dosage forms and product mixes you intend to run.
For Investors and Strategic Allocators
- Focus on lifecycle value, not just unit pricing. Companies that combine engineering depth with deployment support, documentation packages, and service reliability are better positioned to defend margins and win contested projects.
- Watch for integration-led consolidation. Value is migrating toward suppliers that can reduce interface risk across processing and packaging; this creates advantages for broad-portfolio players and for regional specialists that can partner effectively into integrated projects.
- Map regional demand tiers. Recognize that growth will not be uniform: mature markets will reward modernization and compliance alignment, while emerging hubs will drive foundational equipment demand and operator-dependent deployment models.
For Procurement and Quality Leaders
- Engage engineering, quality, and operations earlier. Multi-stakeholder evaluation reduces the likelihood of selecting equipment that performs well on paper but creates friction during qualification, startup, or operator training.
- Standardize acceptance criteria before bidding. Clear user requirement specifications and pre-defined acceptance parameters improve vendor comparisons and lower the probability of post-delivery rework.
- Model total project cost with integration and validation in scope. Including commissioning, documentation, training, and spare-parts logistics in the evaluation framework produces a more realistic comparison of commercial offers.
The pharmaceutical equipment market is evolving from a transactional hardware environment into a strategically integrated, compliance-informed capital arena. Growth at a 7.5% CAGR through 2032 reflects more than incremental demand; it reflects a structural upgrade in how manufacturers think about throughput, quality assurance, documentation, and regional capacity. The winners in this environment will be those who align equipment decisions with broader operational and compliance roadmaps, and those who can demonstrate that alignment under realistic project conditions. For decision-makers seeking deeper segmentation detail, company-level positioning data, and customized deployment scenarios, the full PW Consulting research report provides the granular breakdown and tailored recommendations needed to translate these trends into actionable plans.
Semiconductor Equipment Market
For detailed analysis of this topic, please visit the official page: Pharmaceutical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com