

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Motorcycle Apparel Market 2026: Why a 6.5% CAGR Hides Real Growth Drivers

Strategic Trends and Commercial Opportunities in the Global Motorcycle Apparel Market
The global motorcycle apparel sector is navigating a period of structural transformation, driven by evolving safety standards, material science breakthroughs, and shifting rider demographics. Market valuation reached approximately 263.0 million USD in 2025, expanding from a 2020 baseline of 207.45 million USD. Projections indicate the segment will scale to 404.7 million USD by 2032, reflecting a compound annual growth rate of 6.5 percent across the 2026-2032 forecast window. This trajectory underscores a market that is no longer defined solely by traditional riding gear cycles, but rather by sustained expansion fueled by functional innovation, regulatory realignment, and cross-regional demand generation.
Beyond headline growth figures, the sector is characterized by meaningful concentration dynamics. The top three players account for 48.2 percent of market revenue, while the top five collectively represent 65.3 percent. This concentration pattern suggests established incumbents hold considerable pricing leverage and distribution advantages, yet also leaves substantial runway for specialized manufacturers, regional challengers, and technology-integrated brands to capture differentiated positioning. The market is large enough to support multiple strategic plays, but competitive execution increasingly depends on how quickly organizations translate material, design, and compliance capabilities into rider-centric product architectures.
Current Market Structure and Key Inflection Points
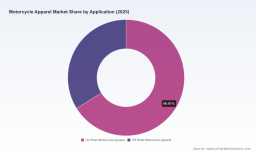
The market is anchored by a product mix that prioritizes upper-body protection, with jackets representing the largest revenue contributor among apparel categories. Pants, gloves, footwear, base layers, and complementary accessories round out a diversified hardware ecosystem that serves both daily commuters and performance-oriented riders. Application-wise, on-road motorcycle apparel commands the largest share, reflecting the broader base of street riders, touring enthusiasts, and urban commuters who prioritize visibility, weather protection, and ergonomic fit. Off-road motorcycle apparel constitutes a meaningful secondary segment, sustained by adventure riding growth, enduro participation, and crossover demand from consumers who blend trail performance with road usability.
Regionally, Asia Pacific leads in absolute market scale, followed by Europe, Latin America, the Middle East and Africa, and North America. Each geography carries distinct demand drivers, ranging from motorcycle ownership penetration and commuting patterns to regulatory frameworks and weather-specific gear requirements. Rather than competing purely on price, successful players are differentiating through regional fit, climate-adaptive designs, and localized compliance alignment.
Three structural inflection points are reshaping how operators should think about the market:
- Safety as a baseline expectation rather than a premium feature. Riders increasingly assume impact protection, abrasion resistance, and ergonomic articulation as standard requirements. This shifts competitive differentiation away from basic protective function toward comfort, weight reduction, ventilation, and lifestyle integration.
- Regulation and classification pressure on supply chains. Standards such as Federal Motor Vehicle Safety Standard No. 218 and CE certification requirements are reinforcing the need for purpose-built protective clothing. At the same time, customs classifications that distinguish motorcycle-specific protective apparel from general-use garments affect sourcing strategies, tariff exposure, and product positioning.
- Material convergence between industrial, outdoor, and riding applications. Heavy denim and reinforced fabrics once associated primarily with workwear or outdoor use are being adapted for riding gear, blurring category boundaries and opening new design and sourcing pathways. This convergence creates opportunities for performance blends, enhanced durability, and cost-efficient material strategies, while also raising the bar for product validation and authenticity of use-case claims.
Core Growth Drivers Shaping the Market
Innovation in protective technology is one of the most consequential drivers in the sector. Impact protection is moving from add-on inserts to integrated system design, with advanced protective foams and engineered armor now appearing as standard elements across race, adventure, and road product lines. This transition matters because it changes the value proposition at the point of purchase: riders are increasingly evaluating fit, mobility, climate control, and protective coverage as a unified package rather than treating armor as an after-market consideration. In practice, brands that can standardize advanced protection across a large share of their range build both credibility and repeat-purchase momentum, especially in categories where safety perception directly influences buying decisions.
Regulatory and compliance dynamics reinforce this shift. Helmet and protective clothing standards are increasingly tied to fatality and injury reduction goals, and protective apparel is expected to meet defined certification frameworks. CE certification remains a critical benchmark for motorcycle protective clothing and gear, while national safety standards continue to shape what can be marketed as purpose-built riding equipment. These frameworks influence product development cycles, testing requirements, and market access. For manufacturers, compliance is no longer a back-office activity; it is a product strategy variable that affects design choices, material selection, and even packaging and labeling language.
Riding Gear Market
Demand-side behavior is also evolving. Riders are seeking apparel that performs across more use cases, including commuting, weekend touring, and light off-road exposure. This multi-use expectation favors versatile construction, modular layering, and seasonal adaptability. At the same time, fashion adjacency remains relevant, particularly in segments where riders treat motorcycle jackets and pants as part of broader wardrobe choices. The result is a dual demand structure: one strand prioritizes technical performance and certified protection, while another values styling, brand heritage, and everyday wearability. Companies that can balance both without compromising protective integrity are better positioned to expand their addressable audience.
Supply chain and cost structure changes add another layer of complexity. Raw material choices increasingly determine both performance outcomes and commercial resilience. Heavy denim fabrics, for example, are used by motorcycle apparel brands for protective riding gear, and heavy-duty denim garments for industrial and outdoor applications represent a substantial share of total heavy-duty denim usage, with motorcycle apparel brands incorporating similar materials. This overlap matters because it affects sourcing flexibility, cost negotiation, and the ability to scale reinforced textiles without sacrificing protective performance. Brands that diversify material sources, validate alternative textile constructions, and design for manufacturability can reduce exposure to single-source dependencies while preserving product integrity.
Motorcycle Gear Market
Competitive Landscape and Leading Strategic Positions
The competitive field blends legacy motorcycle heritage brands, technical apparel specialists, and protection-technology partners. Harley-Davidson, Inc. leverages its MotorClothes® and apparel line to connect riding gear directly with brand identity and a broad consumer base. Tourmaster operates with a broad accessory and apparel focus, extending from motorcycle apparel and heated apparel to gloves, motorcycle luggage, and covers, which creates cross-category relevance for riders seeking integrated gear solutions. Aerostich continues to emphasize equipment for motorcycle and scooter riders, reinforcing a design-led approach to riding-specific gear.
RST has built a clear technical differentiation path by integrating advanced impact protection as a standard feature across its range. In March 2026, RST launched a new apparel collection with 80 percent of the line featuring advanced D3O armor as standard across race, adventure, and road categories. This move signals a strategy centered on protection parity and rider confidence, rather than limiting premium protection to select premium SKUs. Acerbis took a different route in May 2026 by introducing a new denim line with four certified technical models designed for everyday commuting. That launch points to a growing commercial interest in bridging everyday fabric aesthetics with certified technical performance, especially for urban riders who want protective gear that does not read as purely specialized riding equipment.
Belstaff continues to position around men's motorcycle clothing, jackets, and gear tied to movement and lifestyle, reinforcing the appeal of heritage, fit, and stylistic credibility. D3O Lab's role in the ecosystem underscores the importance of protection technology as a shared infrastructure across apparel makers. By developing advanced impact protection technology integrated into motorcycle apparel, technology partners enable multiple brands to raise protective standards without each having to invent proprietary armor systems from scratch. This creates a layered competitive dynamic: apparel brands compete on fit, design, range breadth, and rider experience, while technology suppliers compete on performance characteristics, integration ease, and certification compatibility.
Several broader patterns are visible in how the landscape is evolving:
PW Consulting
- Integration of protection into standard assortments. Leading players are increasingly making advanced protective features part of the core range rather than confining them to high-margin or specialist products. This expands the practical reach of improved safety and normalizes higher protection expectations across price tiers.
- Category blending for everyday use. Releases such as certified denim models for commuting reflect a strategic push to reduce the psychological and aesthetic gap between protective gear and daily wear. This broadens the potential buyer pool and supports repeat usage in urban settings.
- Trade shows and product visibility as launch infrastructure. Events such as the Moto Austria 2026 exhibition, which featured a large selection of clothing and accessories, remain important for assortment signaling, retailer engagement, and trend confirmation. Visibility at these venues is increasingly tied to how clearly a brand communicates protection credentials, material innovation, and use-case versatility.
- Concentration with room for targeted disruption. While the market remains relatively concentrated, the presence of distinct strategic plays—heritage branding, heated and accessory ecosystems, armor integration, and certified commuter wear—indicates that differentiation is still achievable through product definition rather than scale alone.
Future Outlook: Three Strategic Trends for the Next 3-5 Years
Protection is likely to become more standardized across mainstream assortments. As more ranges adopt advanced armor and impact protection as default elements, the market will gradually shift from "optional upgrade" to "expected baseline." For commercial strategy, this means the value of protection alone may compress as a differentiator, while the value of integration quality—fit, weight distribution, ventilation, and washability—increases. Brands that make protection comfortable and unobtrusive will benefit from higher adoption and better rider compliance.
A second trend is the continued narrowing of the gap between protective gear and everyday apparel. Certified technical denim, versatile commuting jackets, and adaptable base layers suggest that motorcycle apparel will keep expanding into routine wear contexts. This opens opportunities for seasonal colorways, urban styling, and multi-environment performance, but it also raises the importance of maintaining authentic protective claims. Consumers and retailers will likely become more attentive to whether a product truly meets riding-specific performance expectations or merely borrows the appearance of motorcycle gear.
A third trend involves regulatory and classification scrutiny becoming more operationally relevant. Standards that define protective clothing and gear can influence product labeling, marketing language, and cross-border trade treatment. Customs classification decisions that distinguish motorcycle-specific protective apparel from general-use garments can affect sourcing choices and cost structures, especially when supply chains rely on materials or manufacturing bases in multiple regions. Companies that proactively align product definitions, testing documentation, and sourcing strategy with regulatory reality will face fewer friction points and greater commercial predictability.
These trends point to concrete commercial opportunities, but they also carry uncertainty. Material and protection innovation can create differentiation quickly, yet they can also raise cost structures and lengthen development cycles. Category expansion into everyday wear can increase demand, yet it can also invite scrutiny if protection claims are not clearly supported. Concentration among leading players can stabilize the market, yet it may also make it harder for smaller entrants to secure shelf space, distribution partnerships, or retailer attention without a sharply defined niche.
Implications and Action Steps for Decision Makers
For apparel manufacturers, the most useful priority is to treat protection, comfort, and styling as a single design equation rather than separate workstreams. Product lines that standardize advanced impact protection while maintaining fit for long rides, ventilation in warmer conditions, and aesthetic versatility for daily use are better aligned with where demand is heading. Equally important is material strategy. Manufacturers should evaluate reinforced textile options, validate alternative sourcing pathways, and ensure that product claims match the use cases they intend to serve. Clear documentation of certification status and intended application can reduce commercial risk and support retailer confidence.
For investors, the market presents a nuanced picture. Growth is steady and the addressable base is expanding, but value creation will likely favor companies with defensible differentiation rather than those competing primarily on volume or price. Attention should be given to brands that can demonstrate repeatable protection integration, credible compliance positioning, and product breadth across on-road and off-road applications. It is also worth monitoring how technology partners and apparel brands interact, since protection technology can be a multiplier for multiple competitors at once. The strategic question is not only which companies are growing, but which are building durable advantages in product definition, rider trust, and supply chain resilience.
For procurement and sourcing leaders, the priority is to align material selection with both performance and trade realities. Sourcing decisions should account for protective textile availability, certification compatibility, and classification implications that may affect import treatment and cost planning. Given the overlap between heavy denim used in motorcycle apparel and similar materials used in industrial and outdoor applications, procurement teams should assess whether dual-use sourcing can improve flexibility without undermining protective performance. Inventory planning should also reflect the increasing expectation that protection features are a standard part of the assortment rather than a limited premium subset.
Across all three roles, the practical takeaway is that the market is moving toward higher default safety expectations, broader everyday usability, and more intricate compliance and sourcing considerations. Decisions made now around product architecture, material strategy, and market positioning will shape how effectively a company can capture demand in the next growth cycle. Organizations that want to evaluate these dynamics at the level of segment splits, regional nuances, and company-specific benchmarks will find greater precision in the full research dataset and custom analysis, where detailed tables, scenario breakdowns, and targeted recommendations are available for deeper planning.
For detailed analysis of this topic, please visit the official page: Motorcycle Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com