

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Inositol Market 2026: Why Plant Based Sources and 6.98% CAGR Reshape Strategy

The Inositol Market: Strategic Trends and Commercial Opportunities Through 2032
The inositol market has transitioned from a niche biochemical ingredient to a strategically important segment within the broader nutritional and pharmaceutical supply chain. Valued at approximately $160.0 million in 2025, the market has expanded from $122.42 million in 2020, reflecting consistent demand growth across multiple downstream applications. Looking ahead, the trajectory points toward $255.82 million by 2032, with a compound annual growth rate of 6.98 percent. This expansion is not merely a function of population growth or generalized wellness trends. It reflects structural shifts in how manufacturers source active compounds, how regulators frame safety and labeling requirements, and how end users increasingly differentiate between synthetic and fermentation-derived alternatives.
For executives and strategic planners, the numbers tell only part of the story. The more critical question is what forces are reshaping competitive positioning, where margin pressure is emerging, and which capabilities will separate future leaders from followers. This analysis examines the market's core dynamics, the drivers accelerating change, the evolving competitive landscape, and the practical implications for manufacturers, investors, and procurement teams.
Market Context and Structural Challenges
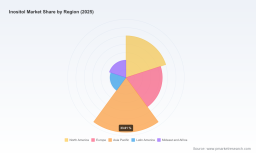
The inositol market operates at the intersection of dietary supplements, pharmaceutical development, animal nutrition, and industrial applications. Demand is distributed across these segments, with dietary supplements and animal feed representing the largest application pools, followed by pharmaceutical use and other industrial or research-oriented applications. On the source side, plant-based production dominates supply, with animal-derived and synthetic routes occupying smaller but strategically important niches. Regional demand is balanced across North America, Europe, and Asia Pacific, with Latin America and the Middle East and Africa providing incremental growth corridors.
Despite this broad distribution, the market is not uniformly mature. Several structural challenges are shaping decision-making and forcing companies to reconsider sourcing strategies, product positioning, and compliance investments.
Raw Material Volatility and Sourcing Diversification
One of the most immediate pressures stems from input cost fluctuations. Rising corn prices through 2025 have prompted manufacturers to reconsider traditional feedstock dependencies and explore alternative raw material pathways. Rice bran and other plant-based inputs are increasingly being evaluated as viable alternatives for inositol extraction and fermentation processes. This diversification is not simply a cost-containment exercise. It reflects a broader recognition that feedstock concentration creates vulnerability, particularly when grain markets are influenced by weather patterns, trade policy shifts, or competing demand from biofuel and food sectors. Suppliers that can secure flexible sourcing agreements or invest in multi-feedstock fermentation capabilities are better positioned to stabilize margins and maintain consistent supply to downstream customers.
Regulatory Clarity and Compliance Burden
Regulatory developments are simultaneously creating opportunities and raising the bar for market participation. In the United States, the FDA's GRAS designation now permits inositol use in infant formula at defined dosage ranges of 4 to 40 milligrams per 100 kilocalories. This establishes a clearer pathway for manufacturers targeting the infant nutrition segment, but it also requires rigorous documentation, batch consistency, and labeling accuracy. In Europe, the European Food Safety Authority has confirmed inositol's safety profile with conservative dosing guidelines, which supports expanded applications while reinforcing the need for evidence-based positioning. At the same time, stricter compliance standards across dietary supplements and functional ingredients are encouraging manufacturers to invest more heavily in clinical research, transparency, and quality control. Companies that treat regulatory alignment as a strategic capability rather than a administrative hurdle are gaining trust with retailers, formulators, and end consumers.
Capacity, Purity, and Differentiation Pressure
The market's competitive structure remains moderately concentrated, with the top three players accounting for a combined share that reflects meaningful but not insurmountable barriers to entry. A CR3 of 35.6 percent and CR5 of 47.8 percent indicates that scale, technological capability, and application-specific expertise matter, but there is still room for specialized suppliers to compete on purity, sustainability, or niche performance characteristics. This dynamic creates pressure for mid-tier and emerging producers to articulate a clear value proposition. Suppliers offering generic bulk inositol face margin compression and customer switching risk, while those able to demonstrate fermentation-derived consistency, solvent-free processing, or application-tailored grades are better positioned to command premium positioning.
Core Drivers Reshaping the Market
The market's growth trajectory is being shaped by several interconnected forces. These drivers extend beyond basic demand expansion and reflect deeper changes in technology, regulation, consumer behavior, and supply chain economics.
1. Fermentation Technology and Sustainable Production Pathways
Technological progress in fermentation has emerged as a defining shift in how inositol is produced and positioned. Traditional extraction and chemical synthesis routes are increasingly being complemented, and in some cases displaced, by fermentation-based processes that offer higher purity, reduced solvent use, and more consistent batch profiles. The commercial launch of solvent-free fermented myo-inositol and the introduction of fermented D-chiro-inositol represent meaningful milestones. These products are being positioned as cleaner, sustainable alternatives for nutraceutical and health-focused formulations, aligning with broader industry expectations around ingredient transparency and environmental impact.
Strategic partnerships are reinforcing this trajectory. Collaborations between biotechnology developers and established chemical or industrial partners are accelerating process optimization and creating pathways for higher-volume production of fermentation-derived intermediates. For market participants, the implication is clear: fermentation capability is becoming a differentiator not just for environmental messaging, but for performance consistency, regulatory positioning, and appeal to formulators seeking cleaner ingredient profiles.
2. Regulatory Alignment and Application Expansion
Regulatory clarity is unlocking new application pathways while simultaneously raising quality expectations. The FDA's guidance on infant formula use and EFSA's supportive safety confirmation are examples of how regulatory frameworks can broaden addressable markets when manufacturers have the documentation and quality systems to meet requirements. These developments are particularly significant for companies targeting early-life nutrition, specialized dietary supplements, and pharmaceutical-adjacent applications where safety and traceability are non-negotiable.
At the same time, tighter compliance expectations are driving investment in clinical research and product transparency. Manufacturers are increasingly expected to substantiate functional claims, provide batch-level consistency, and maintain clear documentation across the supply chain. This environment favors companies that integrate quality, research, and regulatory affairs into their commercial strategy rather than treating them as back-office functions.
3. Demand-Side Shifts Toward Wellness, Metabolic Health, and Specialty Nutrition
End-user demand is evolving along several axes. In dietary supplements, growing consumer awareness of metabolic health, stress response, and hormonal balance has increased interest in inositol as a functional ingredient. In animal nutrition, the push toward improved gut health, feed efficiency, and alternatives to antibiotic growth promoters is expanding the relevance of inositol in feed formulations. Pharmaceutical and research applications continue to require high-purity grades for development and specialized use.
These demand-side shifts are not uniform, but they share a common thread: end users are increasingly selective about ingredient origin, purity, and supporting evidence. Brands and formulators are looking for suppliers that can provide not only consistent material, but also the technical support, regulatory documentation, and application expertise needed to integrate inositol effectively into finished products.
Inulin Market
4. Supply Chain Reconfiguration and Cost Structure Realignment
The inositol supply chain is being reshaped by feedstock dynamics, regional production capabilities, and the cost implications of different manufacturing routes. As corn-based inputs face price volatility, manufacturers are diversifying toward rice bran and other plant-based materials, while fermentation-based producers are investing in scale and process efficiency. These shifts are changing the relative economics of plant-based extraction, animal-derived sourcing, and synthetic production.
For procurement and supply chain teams, the practical implication is that supplier resilience now depends on feedstock flexibility, geographic diversification, and the ability to maintain quality across alternative inputs. Suppliers that can demonstrate robust sourcing strategies and consistent processing standards are better equipped to support long-term customer relationships in a volatile input environment.
Competitive Landscape and Strategic Positioning
The competitive field in the inositol market includes large-scale producers, specialized fermentation developers, established distributors, and research-grade suppliers. The diversity of players reflects the broad application base, but it also means that competitive advantage increasingly depends on how companies align their capabilities with specific customer needs and market segments.
Scale, Fermentation Expertise, and Global Supply
Several Chinese manufacturers have built significant capacity around plant-based myo-inositol and derivatives, including D-chiro-inositol and scyllo-inositol, produced via fermentation and supplied globally for supplements, pharmaceuticals, food, and animal nutrition. With annual capacity reaching thousands of tons in some cases, these suppliers compete on scale, cost efficiency, and the ability to serve multiple downstream markets. Their strategic positioning often emphasizes fermentation know-how, high-purity output, and broad application coverage. For customers seeking reliable volume supply across multiple formats, these players offer an attractive combination of capacity and versatility.
Other regional producers are similarly focused on fermentation-derived inositol and derivatives for dietary supplements, infant nutrition, and feed applications, with an emphasis on high-purity processes. Their value proposition centers on application-specific consistency and the ability to support specialized nutrition segments with controlled-quality material.
Sustainable Innovation and Product Differentiation in Advanced Markets
In the United States and Europe, a different competitive dynamic is emerging around sustainability, purity, and application-specific innovation. Manufacturers and distributors of bulk inositol powder and graded materials for nutritional, pharmaceutical, and industrial uses are active in supplying established markets with reliable volumes and clearly defined specifications. Some focus on whole-food nutritional supplements, offering plant-based inositol for wellness and dietary applications, while others serve industrial and research channels with ISO-certified chemical supply and laboratory-grade material.
D-Mannose Market
A particularly notable strategic move has come from biotechnology developers commercializing solvent-free fermented myo-inositol and industry-first fermented D-chiro-inositol as cleaner, sustainable alternatives for nutraceutical formulations. These launches are not just product additions; they represent a positioning strategy centered on sustainability, higher purity, and alignment with health-focused brands that value fermentation-derived ingredients. Partnerships with established industrial players further reinforce the credibility and scalability of these processes, signaling that fermentation-based differentiation is increasingly integrated into broader supply chain strategies rather than treated as a standalone innovation experiment.
PW Consulting
Research-Grade Suppliers and the High-Purity Segment
Several suppliers specializing in laboratory-grade and API inositol for research, pharma, and biotech applications occupy an important niche. These companies focus on high-purity biochemicals for development, analytical work, and specialized formulations. Their competitive advantage lies in quality documentation, consistency, and the ability to support technically demanding customers. For pharmaceutical developers, research institutions, and biotech teams, these suppliers provide the reliability and specification control required for advanced applications, even if their volumes are smaller relative to bulk nutrition and feed channels.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's structure suggests multiple concurrent trends. On one hand, scale advantages in fermentation and bulk supply are encouraging consolidation among larger producers seeking to strengthen cost positions and global reach. On the other hand, the demand for specialized grades, sustainable sourcing, and application-specific support is sustaining a fragmented layer of niche suppliers and regional specialists. New entrants are likely to focus on fermentation innovation, solvent-free processes, or targeted application segments where purity and documentation create defensible positioning. The overall trajectory points toward a market where broad-scale suppliers and specialized innovators coexist, with competitive success determined by how well each aligns its capabilities with the expectations of its chosen customer base.
Forward Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by several interconnected trends that will shape both opportunity and risk for market participants.
1. Fermentation-Derived and Solvent-Free Products Will Gain Share in Premium Segments
As sustainability expectations rise and formulators seek cleaner ingredient profiles, fermentation-derived inositol and solvent-free processes are poised to capture greater attention in nutraceutical, wellness, and specialty nutrition applications. This trend will not eliminate extraction or synthetic routes across all segments, but it will increasingly differentiate premium offerings and influence procurement decisions among brands that prioritize transparency and environmental positioning. Companies that can demonstrate scalable fermentation capability, consistent purity, and credible sustainability claims will be best positioned to benefit from this shift.
2. Regulatory-Driven Application Expansion Will Open New Demand Pools
The combination of clearer regulatory guidance in the United States and Europe, along with growing interest in infant nutrition, metabolic health, and functional supplements, is likely to expand the addressable market beyond current baselines. Suppliers that invest in documentation, quality systems, and application support will be better equipped to enter these higher-value segments. The opportunity is not simply to sell material, but to provide the regulatory and technical scaffolding that allows customers to use inositol confidently in sensitive or regulated applications.
3. Feedstock Flexibility and Supply Chain Resilience Will Become Competitive Essentials
As input cost volatility persists and manufacturers diversify away from single-feedstock dependencies, the ability to maintain consistent quality across alternative raw materials will become a key differentiator. Supply chain resilience will increasingly be evaluated not just on price, but on sourcing flexibility, geographic diversification, and the ability to guarantee batch consistency under changing input conditions. Companies that build these capabilities into their operating model will be more reliable partners for customers operating in regulated or quality-sensitive environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory described above. Feedstock price swings could compress margins or delay investment in alternative sourcing if volatility proves more persistent than expected. Regulatory environments may shift as authorities revisit dosing guidance, labeling expectations, or safety thresholds, particularly in sensitive applications such as infant nutrition. Competitive entry in fermentation-based production could intensify price competition in premium segments if new capacity outpaces demand growth. Finally, if clinical evidence or consumer perception does not keep pace with product launches, some innovation-driven positioning may face headwinds. Companies should monitor these variables closely and build flexibility into both sourcing and product strategy.
Actionable Guidance for Decision-Makers
The strategic implications differ depending on a company's role in the value chain, but several priorities are broadly relevant.
For Manufacturers and Producers
- Evaluate feedstock diversification as a strategic capability, not just a cost initiative. Multi-source strategies and flexible fermentation or extraction pathways can reduce exposure to commodity volatility and improve supply reliability.
- Invest in fermentation capability and solvent-free or high-purity processes where they align with target customer expectations. Differentiation in sustainability and purity is increasingly tied to commercial positioning in premium nutrition and pharmaceutical-adjacent markets.
- Strengthen quality documentation, regulatory support, and application expertise. Customers in regulated or quality-sensitive segments are looking for suppliers that can provide more than material; they want partners who can support formulation, compliance, and consistency.
For Investors
- Focus on companies with clear technological differentiation, scalable fermentation or production capabilities, and credible pathways into higher-value applications. Volume alone is less compelling than the ability to command premium positioning through purity, sustainability, or application support.
- Monitor regulatory developments as indicators of where demand is likely to expand. Clear guidance in infant nutrition, dietary supplements, and functional ingredients can signal near-term opportunity for suppliers with the right documentation and quality systems.
- Assess supply chain resilience and feedstock strategy as part of long-term risk evaluation. Companies that depend on a single input route or lack flexibility may face margin and continuity risk if commodity conditions shift.
For Procurement and Formulators
- Prioritize supplier resilience and quality consistency over short-term price advantages. In regulated or quality-sensitive applications, batch consistency, documentation, and sourcing transparency can reduce downstream risk and protect brand reputation.
- Engage suppliers early on application requirements, regulatory documentation, and technical support. The most valuable partnerships are built on alignment around purity, grade specifications, and the evidence or compliance support needed for the target market.
- Track fermentation-derived and solvent-free options as potential differentiation levers for product positioning. Where sustainability or cleaner ingredient narratives matter to end users, these alternatives may offer strategic value beyond basic material supply.
Closing Perspective
The inositol market is moving from a broadly functional ingredient space toward a more differentiated landscape shaped by fermentation innovation, regulatory clarity, feedstock dynamics, and evolving end-user expectations. The growth trajectory through 2032 reflects genuine expansion, but the commercial opportunity will be captured by companies that treat quality, sustainability, regulatory alignment, and supply resilience as strategic capabilities rather than operational details.
For organizations seeking deeper segmentation data, company-level benchmarking, region-specific demand patterns, and tailored strategic recommendations, the full PW Consulting research report provides a more granular view of the market and its participants.
For detailed analysis of this topic, please visit the official page: Inositol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com