

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ethylene Oxide Market: Why the 4.22% CAGR Trajectory Changes Everything

Navigating the Ethylene Oxide Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Structural Dynamics
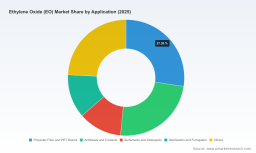
The global ethylene oxide (EO) market has demonstrated consistent expansion over the past half-decade, advancing from approximately $33.9 billion in 2020 to an estimated $41.7 billion in 2025. Projections indicate the market will reach roughly $55.7 billion by 2032, reflecting a compound annual growth rate of 4.22 percent across the forecast window. This trajectory underscores a resilient demand environment that continues to absorb incremental capacity, regulatory friction, and supply chain recalibrations without losing momentum. The underlying composition of value creation remains heavily weighted toward derivative chemistry, with a single downstream family accounting for the majority of volume conversion, while sterilization and specialty applications carve out a strategically critical but smaller share of total throughput.
Current market dynamics reveal two structural tension points that will define investment and operational decisions over the next several years. The first revolves around regulatory intensity targeting commercial sterilization operations, particularly in North America, where emission standards and permitting frameworks have tightened considerably. Facilities have responded by investing in containment engineering, permitting new sites, or adjusting operational footprints, but the pace and durability of compliance adjustments remain uneven across jurisdictions. The second tension lies in regional demand asymmetry. Asia Pacific has emerged as a high-growth conversion hub, driven by expanding polyester and antifreeze/coolant capacity, while mature regions are increasingly focused on high-margin medical and specialty applications rather than bulk commodity margins. This divergence is reshaping how producers allocate merchant-grade material and how sterilization service providers site their processing networks.
A third inflection point sits at the intersection of feedstock economics and end-use substitution pressure. Ethylene oxide pricing and availability are tightly coupled to upstream ethane and ethylene markets, which means cost structures can shift quickly when regional energy dynamics move. At the same time, certain downstream segments are experimenting with alternative sterilization modalities or material substitutions, especially where regulatory exposure and community emissions concerns create operational uncertainty. The result is a market that is still growing, but one in which growth is increasingly contingent on operational discipline, compliance readiness, and differentiated service capabilities rather than volume alone.
Key Drivers Reshaping the Ethylene Oxide Value Chain
Technology and Process Innovation
Innovation in EO handling, sterilization processing, and derivative conversion is moving from incremental improvement toward capability redefinition. On the sterilization side, service providers are increasingly combining EO cycles with complementary modalities such as gamma radiation and vaporized hydrogen peroxide to widen the range of sterilizable materials and reduce cycle times for mixed product portfolios. This hybrid approach matters because medical device manufacturers increasingly ship complex assemblies, polymer components, and temperature-sensitive instruments that cannot tolerate uniform treatment protocols. By layering sterilization technologies under one service framework, providers can offer design-for-sterilization guidance and post-processing validation that become value-added differentiators rather than commoditized throughput services.
In the derivative space, conversion efficiency and purity specifications are becoming more tightly linked to application performance. Ethylene glycols and glycol ethers continue to anchor large-scale industrial and consumer demand, but the highest-value niches are concentrating around ultra-pure grades for medical sterilization and specialty ethoxylates and ethanolamines used in formulation chemistry. Operators that can guarantee consistent purity, traceability, and lot-level documentation are gaining preferential access to regulated applications, which in turn raises the operational bar for newer entrants and rewards established facilities with mature quality systems and engineering depth.
Regulatory and Compliance Environment
Regulatory evolution remains the single most consequential variable for commercial sterilization operations. Recent EPA proposals to amend existing emission standards for commercial sterilization facilities reflect a deliberate balancing act: preserving the availability of life-saving devices that depend on EO sterilization while addressing community exposure concerns. The proposed adjustments, which include discussions around permanent total enclosure requirements and other operational conditions, signal that regulators are actively recalibrating compliance burdens in response to supply chain risk considerations. This matters commercially because sterilization capacity is not easily relocated or rapidly duplicated; permitting timelines, community engagement, and engineering retrofits can stretch project schedules and alter site economics.
Beyond federal action, state and local air quality programs continue to influence operating conditions, and enforcement outcomes can reshape community expectations and facility siting strategies. The trend is not a blanket regulatory contraction; rather, it is a selective tightening that creates compliance winners and losers. Operators with robust emissions control engineering, transparent monitoring practices, and documented safety governance are better positioned to sustain operating continuity. Conversely, facilities that rely on legacy configurations without proactive upgrade planning face greater uncertainty in permitting renewals, expansion approvals, and long-term site viability.
Demand-Side Shifts in Medical Devices and Industrial Applications
Demand behavior is bifurcating across application clusters. In medical and pharmaceutical channels, EO remains deeply embedded in sterilization workflows for in vitro diagnostics, catheters, syringes, disposable consumables, and other temperature-sensitive devices. The scale of this dependency reinforces the strategic importance of reliable sterilization capacity, particularly when device complexity increases and manufacturers require validated, repeatable processes with strong documentation support. As device portfolios diversify, sterilization is increasingly treated as an extension of product design and quality assurance, not simply a finishing step. This creates commercial opportunities for service providers that can align sterilization protocols with device development cycles and regulatory submissions.
Polyethylene Oxide (PEO) Market
On the industrial side, polyester fiber and PET resin production continue to anchor large-volume EO derivative demand, supported by apparel, packaging, and industrial polyester applications. Antifreeze and coolant formulations also remain substantial consumer of ethylene glycol derivatives, with demand tied to automotive, HVAC, and industrial machine cooling needs. While these bulk segments are more price-sensitive and cyclical than medical sterilization, they still provide the volume foundation that supports merchant EO economics. The strategic implication is that producers and converters must manage a dual rhythm: disciplined execution in cyclical commodity demand, and premium positioning in regulated, specification-driven applications that carry higher switching costs.
Ethanolamine Market
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost and supply dynamics are increasingly influenced by geographic concentration in feedstock access and conversion capacity. Regional production clusters have shaped short-term availability and pricing behavior, with merchant EO distribution dependent on logistics, storage, and site-level handling standards. Because EO is both reactive and hazardous, the cost structure extends beyond raw material pricing to include safety systems, certification, transport controls, and insurance exposure. As a result, the economics of EO supply are highly sensitive to operational maturity and regional infrastructure quality, which gives established producers and integrated service networks a structural advantage in stable service delivery.
At the same time, sterilization demand for ultra-pure grades creates a specialized supply track that operates with higher quality and handling requirements than merchant commodity streams. This bifurcation means that the same molecule can command very different commercial treatment depending on application class, documentation needs, and compliance posture. Companies that can cleanly separate operational lanes, manage purity assurance, and maintain reliable throughput under tighter handling protocols are better positioned to capture margins in regulated segments, while commodity-focused players must compete more aggressively on availability, flexibility, and cost discipline.
Competitive Landscape and Strategic Positioning
How Leading Players Differentiate
The competitive field spans producers, sterilization service providers, and device manufacturers that intersect with EO across different segments of the value chain. Core enterprise profiles reveal three broad strategic orientations. Some organizations focus on high-purity medical-grade EO packaged for low-temperature sterilization of sensitive devices, emphasizing purity assurance, packaging integrity, and service support for regulated applications. Others position around contract sterilization services, offering validated processing in compliance with recognized sterilization standards and building multi-facility networks that can serve device manufacturers at scale. A third group includes large device manufacturers and diversified industrial players that use EO sterilization as part of their product delivery or supply operations, often embedding sterilization strategy into broader quality and regulatory planning.
Within this landscape, differentiation is increasingly driven by compliance capability, geographic reach, and service integration rather than by feedstock ownership alone. Sterilization providers that invest in validated protocols, engineering support, and emissions management can reduce the operational risk that device manufacturers are increasingly unwilling to absorb internally. Producers that supply merchant-grade EO benefit from volume stability in bulk derivative markets, but their strategic leverage grows when they can reliably serve regulated sterilization demand with consistent quality and logistics reliability. Device manufacturers that oversee their own sterilized product lines gain advantage by aligning material selection, packaging, and sterilization validation early in development, which can shorten qualification cycles and reduce downstream processing risk.
Recent operational moves illustrate these choices in practice. New sterilization facility construction in growth regions reflects the push to place capacity closer to expanding medical device and diagnostics manufacturing bases. Simultaneously, technology combinations that blend EO with other sterilization modalities are being introduced to accommodate broader material compatibility and sterility assurance requirements. Regulatory and legal resolutions around permitting and emissions have also become part of the strategic picture, reminding the market that operating license stability, community relations, and documented compliance practices are now central to long-term commercial viability.
PW Consulting
Market Structure Evolution
Market concentration remains relatively high, with a limited number of large players accounting for a substantial share of total value. That concentration is most visible in bulk derivative supply, where scale economics and feedstock access shape the competitive field. In sterilization services, the structure is more fragmented across geographies and facility networks, but consolidation trends are emerging where integrated service capabilities, multi-site footprints, and compliance infrastructure create defensible positions. The resulting landscape is neither purely consolidated nor purely dispersed; it is stratified, with commodity supply leaning toward scale concentration and specialized sterilization and device-related applications trending toward capability-driven consolidation.
The evolution trajectory suggests a continued pull toward operational maturity thresholds. New entrants will find it difficult to compete on pure price in regulated sterilization markets because qualification, documentation, emissions control, and long-term reliability create high switching costs for customers. At the same time, regional demand growth can still invite capacity additions in conversion and derivatives, especially where local polymer, packaging, and antifreeze demand expands. The practical outcome is a market where strategic advantage accrues to firms that combine scale, quality systems, compliance readiness, and proximity to end-use demand clusters, while generic capacity without differentiated execution faces margin compression and higher operational risk.
Forward Outlook: Three Trends Shaping 2027 to 2032
Trend One: Sterilization as a Stabilized Strategic Capability
Over the next several years, EO sterilization is likely to become more institutionalized as a specialized capability rather than a commoditized service. The combination of device complexity, regulatory scrutiny, and the continued scale of EO-dependent sterilization supports this direction. Providers that invest in standardized protocols, hybrid sterilization options, emissions engineering, and transparent compliance reporting will be better positioned to secure multi-year service relationships and reduce customer-side operational burden. The commercial opportunity lies not just in processing volume but in becoming a partner in device qualification, packaging design, and supply continuity, which can create stickier demand and more predictable revenue streams.
Trend Two: Regional Rebalancing of Conversion and Service Capacity
Demand growth will continue to be uneven geographically, and capacity expansion will follow end-use momentum rather than uniform global growth rates. Asia Pacific and other developing industrial regions will likely remain focal points for derivative expansion, particularly in polyester and coolant-related applications, while North America and Europe will keep attention on higher-value medical device sterilization and specialty derivatives. This rebalancing creates opportunities for companies that can site capacity intelligently, manage cross-border logistics for merchant EO, and align service networks with regional device manufacturing density. It also introduces risk for operators who assume demand migration will be linear; regional policy shifts, energy cost changes, and local permitting environments can alter the attractiveness of specific sites or expansion plans.
Trend Three: Compliance Discipline as a Margin Determinant
As emissions expectations and community oversight remain elevated in several jurisdictions, compliance performance is increasingly becoming a margin determinant rather than a back-office operational issue. Facilities that proactively manage containment, monitoring, permitting documentation, and community engagement will face lower interruption risk and stronger negotiating positions with regulators and customers. Conversely, facilities that treat compliance improvements as reactive or episodic will face greater exposure to enforcement actions, operational pauses, and reputational friction. The strategic implication is that capital allocation toward safety, engineering, and compliance infrastructure should be modeled as a growth enabler, not merely a cost center, especially for operations tied to regulated medical applications.
Strategic Actions for Decision Makers
For Manufacturers and Service Providers
Design EO-related operations around two parallel mandates: reliability in regulated applications and cost discipline in bulk derivative markets. For sterilization services, prioritize validated processing frameworks, hybrid modality flexibility, emissions engineering, and documentation quality that supports device manufacturers across qualification and production cycles. For derivative producers, sharpen purity assurance and lot-level traceability where premium grades command stronger positioning, while preserving operational efficiency in commodity conversion. Where expansion is contemplated, sequence site decisions around end-use density, permitting feasibility, and logistics reliability rather than treating capacity additions as purely volume-driven responses.
Strengthen supply resilience by clarifying which customer segments depend on merchant EO availability versus ultra-pure sterilization grades, then align inventory, handling, and distribution practices accordingly. Build contingency planning for feedstock price volatility and regional energy shifts, since those variables can quickly change margin profiles even when end-demand remains stable. Treat safety, compliance, and emissions management as core competencies that influence customer selection, permitting speed, insurance conditions, and long-term site viability.
For Investors
Screen opportunities through a lens of operational maturity and regulatory exposure, not just top-line growth potential. In sterilization-linked operations, assess emissions control capability, facility siting strategy, compliance documentation, and the degree to which the business is integrated with device qualification and service continuity. In producer and derivative conversion businesses, evaluate feedstock access, regional cost structure, purity capability for premium grades, and exposure to cyclical demand swings in polyester, antifreeze, and coolant markets. The highest-risk exposures often sit where compliance, permitting, or community relations are under-managed, even if revenue growth appears attractive in the near term.
Look for businesses that are converting regulatory pressure into durable competitive advantage by investing in engineering, monitoring, and multi-modality service options. In growth regions, distinguish between genuine demand-led expansion and speculative capacity additions; the former tends to be supported by local manufacturing density and downstream application growth, while the latter may face margin pressure if supply outpaces absorption. Finally, monitor where hybrid sterilization services and premium-grade handling create switching costs that protect revenue quality, since those are the segments most likely to sustain differentiated returns through cycles.
For Procurement and Supply Chain Leaders
Treat EO-dependent supply as a strategic continuity issue rather than a routine commodity purchase. Where medical devices, diagnostics, or temperature-sensitive materials depend on EO sterilization, validate supplier readiness across validation support, emissions posture, facility redundancy, and documentation quality. For industrial derivative procurement, focus on availability reliability, specification consistency, and logistics controls that account for hazardous-material handling and regional supply access. Diversifying processing routes or site options where feasible can reduce concentration risk, but only if alternative sources meet the same quality and compliance expectations required by your applications.
Incorporate compliance and operational resilience questions into supplier evaluation, including evidence of emissions management practices, permitting status, safety governance, and continuity planning. For categories where substitution or alternative sterilization modalities are technically feasible, run structured cost and risk comparisons rather than assuming price alone determines the best choice. In many cases, the lowest apparent unit cost can be offset by qualification delays, documentation gaps, or interruption risk in regulated supply chains.
From Market Intelligence to Execution
The ethylene oxide market is expanding, but the character of that expansion is changing. Growth is increasingly governed by compliance readiness, product complexity, regional end-use demand, and the ability to deliver reliable service across both regulated and commodity segments. Firms that understand these operating realities can align capacity, service models, and procurement strategies with where value is actually being created, rather than assuming that volume growth will automatically translate into favorable outcomes.
For teams that need a deeper, segment-level view of regional demand patterns, derivative conversion splits, application drivers, competitive footprints, and scenario-based sizing through 2032, the comprehensive PW Consulting research report provides detailed data and customized recommendations designed for implementation planning.
For detailed analysis of this topic, please visit the official page: Ethylene Oxide (EO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com