

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Peripheral Guidewire Market: 7.8% CAGR Trajectory Signals Shifting Value Pools

Strategic Shifts and Commercial Opportunities in the Peripheral Guidewire Market
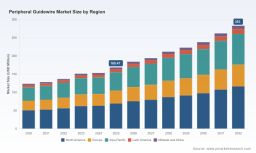
The peripheral guidewire market has entered a phase of sustained expansion, underpinned by consistent revenue growth across the 2020–2025 period and a robust projected trajectory through 2032. Market size evolved from approximately $123.45 million in 2020 to $151.08 million in 2023, accelerating to $168.47 million in 2025. The forecast period from 2026 to 2032 projects a compound annual growth rate of 7.8 percent, with valuations scaling toward $283.0 million by the end of the horizon. This trajectory reflects not merely incremental expansion but a structural redefinition of how clinicians navigate peripheral vascular disease, diagnostic pathways, and minimally invasive interventions. For executives and investors, the market presents a maturing landscape where differentiation hinges on material science, regulatory agility, and partnership-driven distribution rather than volume alone.
Despite the positive momentum, the industry faces structural tensions that will shape competitive outcomes over the next five years. First, the balance between standardization and specialization remains unresolved. Guidewires must deliver reliable trackability and pushability across diverse anatomical targets, yet the proliferation of lesion complexity, smaller vessel diameters, and transradial access protocols demands tailored performance profiles. Second, regulatory harmonization is intensifying compliance costs while simultaneously raising barriers to entry for fragmented suppliers. The alignment of quality management systems with ISO 13485:2016 and the continued reliance on 510(k) pathways for device iterations create a dual dynamic: predictable clearance routes for incremental innovations, but elevated scrutiny for novel material combinations or performance claims. Third, reimbursement environments and hospital cost-containment programs are pressuring procurement teams to justify premium device selections, pushing manufacturers to demonstrate clinical outcomes, reduced procedure time, or lower complication rates to sustain pricing power.
Technology Innovation and Material Performance
Material science continues to anchor the market’s evolution. Nitinol-based constructions dominate performance-sensitive applications due to their superelastic properties and resistance to kinking, while stainless steel retains a strong foothold for routine procedural navigation where cost efficiency and torque control are prioritized. Composite architectures are gaining traction in scenarios requiring balanced flexibility and column strength, particularly where hydrophilic coatings and jacketed designs enhance lubricity without compromising tactile feedback. Innovation is increasingly moving toward micro-scale engineering: micro-cut nitinol sleeves, targeted coil geometries, and precision-layered jackets are enabling guidewires that maintain luminal support in smaller vessels while improving deliverability through tortuous anatomy. These advances are not cosmetic; they translate into longer device longevity, reduced procedural friction, and expanded use cases that blur the boundary between diagnostic traversal and interventional support.
Regulatory Environment and Quality System Alignment
The regulatory landscape is evolving from fragmented national expectations toward more converged quality frameworks. The finalization of quality management system rules aligning with ISO 13485:2016 has consolidated expectations around design control, risk management, and post-market surveillance, providing a clearer compliance pathway for manufacturers that invest early in standardized processes. Concurrently, 510(k) clearances for peripheral and neurovascular guidewires remain a practical route for incremental product iterations, but the emphasis on substantial equivalence and performance comparability means that innovation must be framed within demonstrable clinical or usability advantages. For companies operating across regions, the divergence in certification timelines—exemplified by CE MDR approvals and U.S. clearances—requires portfolio planning that anticipates geographic sequencing, not just device readiness.
Guide Wires Market
Demand-Side Shifts in Clinical Practice
Clinical adoption patterns are reshaping demand. Transradial access has expanded beyond coronary interventions, with growing interest in peripheral artery disease procedures that prioritize patient comfort, reduced bleeding complications, and faster recovery. At the same time, interventional volumes in lower extremity disease are rising as population risk factors persist and image-guided techniques improve procedural confidence. The convergence of these trends puts pressure on guidewire portfolios to support both diagnostic navigation and interventional maneuvering, often within a single procedural workflow. Hospital administrators and procurement committees increasingly evaluate device choices through the lens of procedure efficiency, compatibility with existing catheter systems, and the ability to reduce device swaps or redundant access attempts. Consequently, guidewire value propositions that emphasize reliability, trackability, and procedural versatility are gaining procurement attention.
Supply Chain and Cost Structure Pressures
Manufacturing complexity, raw material variability, and sterilization requirements continue to influence cost structures. The competitive intensity reflected in a moderately concentrated market—with the top three and top five players holding a modest combined share—indicates room for specialization but also rewards scale advantages in sourcing, testing, and quality assurance. Companies that can manage coating consistency, coil precision, and device finishing at scale are better positioned to absorb compliance overhead while maintaining margin integrity. At the same time, distribution strategies are becoming a more meaningful lever: exclusive partnerships and regional commercialization agreements allow established players to expand portfolios without proportionally increasing internal manufacturing footprint, while smaller innovators leverage targeted approvals to enter high-value markets with focused product lines.
Competitive Landscape and Leading Strategies
The competitive field combines multinational device platforms with specialized manufacturers and regional innovators, each pursuing distinct strategic positions. Abbott Laboratories provides a peripheral vascular intervention portfolio focused on support and navigation wires for lower extremity procedures, positioning itself around clinical familiarity and broad procedural coverage. Boston Scientific Corporation has emphasized challenging small vessel and peripheral artery disease interventions through dedicated lines, reinforcing a strategy centered on deliverability in complex anatomy. Terumo Corporation offers hydrophilic and specialty guidewires for interventional cardiology and peripheral procedures, leveraging coating technology and navigation feel as differentiators. Medtronic plc supplies peripheral guidewires for transradial access in peripheral artery disease treatment, aligning product design with the broader shift toward radial workflows. Asahi Intecc Co., Ltd. focuses on trackability and durability for PTA and PPI procedures, emphasizing precision engineering in repeat-use scenarios. Cook Medical LLC extends peripheral guidewire portfolios across urology, gastroenterology, and vascular access, reflecting a cross-specialty distribution logic rather than a single-vascular focus. B. Braun Melsungen AG designs guidewires for safe catheter placement in peripheral procedures, emphasizing controlled access and procedural safety. Merit Medical Systems, Inc. delivers high-precision guidewires across cardiovascular, peripheral, radiology, and urology interventions, supporting a diversified interventional footprint. Biotronik SE & Co. KG provides vascular access and intervention guidewires, adding to the regional and specialty coverage mix. CONMED Corporation manufactures guidewires and related peripheral intervention tools, while Cardinal Health, Inc. distributes guidewire products through its Cordis division for peripheral vascular procedures. Specialty and emerging players such as LA Vascular, Future Medical Design Co., Ltd., and BrosMed Medical illustrate a parallel layer of targeted innovation and regional commercialization.
Worldwide Wedge Pressure Catheter Market
Differentiation Through Product Architecture and Access Strategy
Leading strategies are bifurcating around two complementary models. The first is portfolio depth within a defined clinical pathway: companies invest in multiple diameters, tip designs, coating options, and support profiles to cover diagnostic traversal, lesion crossing, and post-dilation support. The second is targeted expansion through distribution and co-commercialization, where established platforms extend their reach by licensing or exclusively distributing specialized guidewires that complement existing procedural lines. Both approaches aim to reduce the need for clinicians to switch vendors mid-procedure, a practical driver of preference and order consistency. Differentiation is increasingly less about claiming generic superiority and more about demonstrating that a particular combination of tip stiffness, shaft flexibility, coating behavior, and compatibility with catheter systems solves a specific procedural bottleneck.
Market Evolution: Consolidation, Niche Focus, and New Entrants
The market structure suggests gradual consolidation in distribution and service delivery, but persistent fragmentation in product specialization. Incumbents benefit from clinician relationships, established training ecosystems, and the credibility of broad intervention portfolios, which strengthens repeat procurement. At the same time, niche players continue to enter with focused designs, CE MDR approvals, or 510(k) clearances that unlock regional opportunities. This dynamic creates a two-speed environment: large players compete on breadth, service, and procedural integration, while smaller entrants gain traction by addressing specific anatomical challenges, access routes, or coating preferences. Over time, the most resilient portfolios will likely combine internal engineering with selective partnership-driven expansion, balancing fixed cost exposure with the agility to enter new procedural niches.
Future Trends and Commercial Implications
Several trends are likely to shape the market over the next three to five years. First, the integration of guidewire performance with procedure efficiency will intensify. Devices that reduce navigation time, improve lesion access, or lower the likelihood of device exchange will be valued not only for clinical outcomes but also for throughput and resource utilization. Second, transradial and small-vessel access will continue to expand peripheral use cases, encouraging designs that preserve tactile feedback while supporting finer delivery systems. Third, the regulatory and quality environment will reward manufacturers that have already institutionalized ISO-aligned processes and can respond quickly to clearance requirements, potentially favoring organizations with disciplined design controls and documented performance comparability. These trends collectively point toward a market where technical performance, procedural fit, and commercial execution matter as much as raw device approval.
Commercial opportunities will accrue to companies that align product development with procurement realities. For manufacturers, the value proposition will increasingly include evidence of procedural reliability, compatibility with existing access systems, and a clear mapping to lesion complexity and vessel size. For investors, the market’s moderate concentration invites attention to firms that can convert specialized approvals into regional scale, and to platforms that use distribution agreements to extend portfolio breadth without proportionate manufacturing expansion. For procurement and clinical leaders, the opportunity lies in standardizing around guidewires that demonstrably reduce procedural friction, while maintaining flexibility for complex cases that require alternative support profiles. Potential risks include reimbursement variability that compresses device budgets, regulatory timeline shifts that delay regional launches, and material or coating consistency challenges that can affect device performance consistency at volume.
Strategic Actions for Decision-Makers
Guidance for Manufacturers
Product roadmaps should prioritize features that translate directly into procedural value: predictable trackability in tortuous anatomy, reliable torque transfer, and coating behavior that supports smooth advancement without compromising tactile control. Regulatory planning should treat geographic sequencing as a commercial decision, aligning approval timing with distribution readiness and clinician training capacity. Where internal scale is limited, selective distribution partnerships can accelerate market access while preserving engineering focus on performance differentiation. Quality systems should be designed with anticipated clearance expectations in mind, ensuring that design history, risk documentation, and performance comparability are ready when submission windows open.
PW Consulting
Guidance for Investors
Investment attention should focus on companies that demonstrate a credible path from product approval to commercial execution, particularly where regional clearance events can unlock share in targeted markets. The combination of moderate concentration and active specialty entrants suggests that value will emerge from execution discipline rather than broad market exposure alone. Distribution agreements and exclusive partnerships can be meaningful indicators of commercialization intent, but they should be evaluated alongside manufacturing readiness, service infrastructure, and the clarity of the underlying procedural need. Portfolio breadth is valuable, but breadth without procedural fit or reliable supply can dilute returns.
Guidance for Procurement and Clinical Strategy Leaders
Procurement strategies should weigh guidewire selection against total procedural impact, including navigation reliability, compatibility with existing catheter systems, and the likelihood of reducing device swaps in complex cases. Standardization where clinically appropriate can improve efficiency and inventory management, while maintaining access to specialty designs for challenging anatomy preserves procedural flexibility. Supplier evaluation should incorporate not only unit economics but also documentation quality, regulatory alignment, and the ability to support training and consistent supply. In an environment where procedure efficiency and access route preferences are evolving, device selection should be revisited periodically to ensure alignment with updated clinical workflows.
The peripheral guidewire market is expanding on the strength of procedural demand, material innovation, and evolving access preferences, but the most consequential decisions will be made by organizations that can connect device performance to real workflow outcomes. Detailed segment-level sizing, regional demand patterns, and company-specific benchmarking will sharpen strategic planning and reveal where commercial leverage is greatest. For decision-makers seeking granular data and tailored recommendations, the full PW Consulting market research report provides deeper breakdowns and scenario-based guidance to support investment, portfolio, and procurement decisions under evolving clinical and regulatory conditions.
For detailed analysis of this topic, please visit the official page: Peripheral Guidewire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com