

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bearing Steel Market 2026: Why a 5.07% CAGR Early to 2032 Reflects Real Demand Shifts|Beyond the Numbers

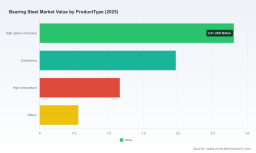
Strategic Trends and Commercial Opportunities in the Bearing Steel Market
The bearing steel market stands at a critical inflection point, shaped by the convergence of aerospace innovation, automotive electrification, and industrial automation. Over the historical period from 2020 to 2025, the market expanded from approximately $5.00 billion to $6.50 billion, reflecting steady demand acceleration across end-use sectors. Looking ahead through 2032, the trajectory points to a compound annual growth rate of 5.07 percent, with revenue projected to reach roughly $9.19 billion by the end of the forecast horizon. This growth pattern underscores a market that is not merely expanding in volume but is also undergoing structural transformation in material specifications, supply chain configuration, and regional balance.
Such a macro environment presents both opportunity and complexity. Demand is increasingly tied to performance-critical applications where bearing steel must withstand higher loads, elevated temperatures, and stricter cleanliness standards. Simultaneously, producers and end-users face volatility in raw material logistics, energy costs, and regulatory expectations around sustainability. Understanding how these forces interact is essential for executives evaluating capacity investments, procurement strategies, or product roadmaps.
Resilience Amid Raw Material and Energy Volatility
One of the most persistent challenges is the sensitivity of bearing steel production to energy prices, alloying element availability, and broader metallurgical input costs. The margin structure of specialty steel manufacturing depends heavily on controlled process conditions, scrap quality, and access to high-purity additives. When energy markets fluctuate or logistics networks tighten, producers must balance cost absorption with price pass-through, making margin stability a recurring concern. Companies that can decouple operating efficiency from commodity swings are better positioned to sustain profitability across cycles.
For downstream bearing manufacturers and OEMs, this volatility translates into longer planning horizons, more frequent contract renegotiations, and a stronger emphasis on supplier reliability. Procurement teams are increasingly prioritizing partners that can demonstrate consistent chemical control, traceability, and flexible delivery models. In practical terms, the cost challenge is less about absolute price levels and more about predictability and risk allocation across the value chain.
Performance Demands from Aerospace and Automotive Electrification
A second pivotal shift comes from the performance envelope required in next-generation applications. Aerospace engines and electric vehicle drivetrains are pushing bearing materials into higher temperature, higher load, and lower friction regimes. These applications demand not only superior fatigue strength and wear resistance but also compatibility with novel manufacturing approaches such as ceramic coatings, specialized heat treatments, and tighter cleanliness thresholds. The result is a market segment where incremental improvements in alloy design and process control can generate disproportionate value.
This trend creates a clear divergence between commodity-grade bearing steel and advanced, application-specific grades. As aerospace and automotive programs become more technology-intensive, the ability to certify and scale new steel formulations becomes a competitive differentiator. Firms that can align material development with the qualification timelines of OEMs gain access to higher-margin, longer-cycle relationships that are less susceptible to price competition.
Regional Rebalancing and Supply Chain Reconfiguration
A third structural factor is the ongoing rebalancing of regional production and demand patterns. Asia Pacific has emerged as a dominant demand center, reflecting the scale of automotive manufacturing, industrial equipment production, and infrastructure investment across the region. This concentration is reshaping supply chain logic, with regional sourcing priorities increasingly influenced by delivery reliability, trade policy, and the desire to reduce exposure to transoceanic disruptions.
At the same time, European and North American producers retain strengths in advanced metallurgical expertise, aerospace-grade certifications, and proximity to high-value end markets. The market is therefore not simply consolidating around one geography; instead, it is evolving into a multi-polar system where regional specialization, technology leadership, and logistics flexibility determine competitive advantage. Companies that can operate across this distributed landscape while maintaining quality consistency are gaining strategic leverage.
Advanced Alloy Development as a Core Growth Engine
Technological innovation remains the most direct driver of market value creation. Recent introductions of patented bearing steel alloys designed for higher load and temperature capacity illustrate how material science is opening new performance frontiers. These alloys are not merely incremental refinements; they enable tighter integration between bearing design and steel specification, allowing OEMs to optimize systems for weight reduction, efficiency, and durability.
The commercial implication is clear: advanced alloy development is shifting from a supporting function to a strategic capability. Producers that invest in proprietary grades, controlled melting practices, and application-specific testing can command premium positioning and longer-term customer engagement. This dynamic also raises the barrier to entry for commoditized producers, reinforcing a market structure in which differentiation increasingly depends on metallurgical know-how rather than scale alone.
Policy and Regulatory Pressures on Sustainability and Material Standards
Policy and regulatory evolution is shaping both production practices and demand behavior. Stricter expectations around carbon intensity, material traceability, and product lifecycle accountability are becoming embedded in procurement requirements across automotive, aerospace, and industrial sectors. These expectations are not abstract compliance issues; they influence supplier selection, product qualification, and long-term contract structures.
For bearing steel producers, the regulatory environment is accelerating investment in cleaner production methods, energy-efficient rolling and heat-treatment processes, and documentation systems that support transparent sourcing. The firms that treat sustainability as an operational capability rather than a reporting exercise are likely to secure stronger relationships with customers facing their own decarbonization targets. In this context, regulatory pressure functions as a catalyst for product and process innovation, not merely a constraint.
Demand-Side Shifts Across Automotive, Aerospace, and Industrial End-Use
On the demand side, the most influential change is the transformation of end-use requirements. Automotive applications continue to represent the largest share of market value, driven by both conventional drivetrain components and the evolving needs of electrified powertrains. Aerospace demand is intensifying as engine architectures become more demanding and as long-life, high-reliability components gain prominence. Industrial machinery and equipment add further support as automation, robotics, and high-cycle manufacturing expand.
This diversification matters because it alters the shape of demand growth. Rather than relying on a single dominant application, the market is increasingly supported by multiple specialty demand centers, each with different performance, certification, and volume characteristics. For producers and service providers, this means that portfolio breadth, application expertise, and the ability to customize steel grades are becoming more important than uniform volume growth.
Supply Chain Localization and Cost Structure Compression
Supply chain dynamics are also reshaping the cost structure and competitive logic of the bearing steel market. Regional sourcing preferences, inventory strategies, and risk mitigation priorities are encouraging closer alignment between steel producers and bearing manufacturers within key markets. This localization trend supports faster response times and greater transparency, but it also pressures producers to maintain cost efficiency at smaller regional scales.
At the same time, vertical integration is becoming more visible as an industry theme. Some bearing manufacturers maintain in-house steel production to secure consistency and reduce dependency on external suppliers, while others rely on specialized steelmakers with deep metallurgical capabilities. The interplay between integrated and specialized models is influencing pricing power, innovation cycles, and long-term resilience. Companies that can adapt their sourcing and production strategies to these evolving relationships are better equipped to manage both cost and performance risks.
Market Structure and Competitive Dynamics
The market remains moderately concentrated, with the top three players accounting for approximately 45 percent of share and the top five reaching roughly 55 percent. This structure reflects the advantages of scale, technical depth, and established customer relationships, but it also indicates room for differentiation through specialized products and regional leadership. Rather than a simple oligopoly, the landscape is characterized by overlapping strengths: some firms compete on aerospace-grade materials, others on high-cleanliness industrial grades, and others on integrated bearing solutions.
Sweden-based SKF illustrates the strategic importance of advanced alloy development with recent introductions of bearing steel formulations designed for next-generation aeroengine applications. Its focus on combining higher load capacity with elevated temperature tolerance highlights how material innovation can anchor high-value aerospace relationships. Sweden-based Ovako has reinforced a complementary position through bearing quality steel optimized for fatigue strength and high cleanliness, emphasizing consistent metallurgical control as a basis for serving major bearing manufacturers.
Japan-based producers are pursuing distinct pathways. Sanyo Special Steel continues to support aerospace and wind power applications by expanding high-cleanliness bearing steel grades, while Aichi Steel Corporation maintains a strong presence in high-carbon chrome bearing steel for automotive and industrial use. Nippon Steel contributes high-cleanliness grades within a broader specialty steel portfolio, and several Japanese bearing and engineering groups utilize in-house steel production to secure performance and supply reliability. NSK’s recent launch of ceramic-coated bearing steel balls for high-temperature aerospace applications underscores the trend toward hybrid material solutions, while JTEKT and NTN demonstrate the strategic value of integrating steel production with precision bearing manufacturing. Germany-based Saarstahl rounds out the competitive field with high-purity aluminum-free bearing steels targeting industrial and automotive applications.
Taken together, these profiles reveal a market in which differentiation is multi-dimensional. Some competitors compete on alloy novelty, others on cleanliness and fatigue performance, and others on vertical integration and application-specific product design. The presence of both steel specialists and bearing manufacturers with internal steel capabilities suggests a landscape where partnerships, co-development, and selective integration are all viable strategic models.
Evolution of the Competitive Landscape
The competitive dynamics are likely to become more layered rather than purely consolidated. On one hand, the technical complexity of advanced bearing steel supports continued advantages for established players with strong testing, certification, and production capabilities. On the other hand, demand for specialized grades and regional responsiveness creates openings for focused suppliers that can deliver high value in targeted segments. New entrants are unlikely to succeed through broad commodity positioning; instead, credible competition is emerging where firms can demonstrate clear performance advantages, reliable supply, or cost-efficient specialization.
High Carbon Bearing Steel Market
This evolution favors companies that can align their strategic positioning with the highest-value demand streams. Aerospace applications reward material innovation and qualification depth. Automotive applications reward scale, consistency, and cost discipline. Industrial applications reward flexibility and closeness to regional machine-building ecosystems. The firms that can articulate and execute a distinct value proposition within these streams are best placed to expand share without depending solely on volume-driven competition.
Trend One: Material Innovation as the Primary Value Frontier
Over the next three to five years, advanced material design is expected to remain the most important value frontier. As bearing systems face higher loads, greater thermal stress, and tighter efficiency requirements, the ability to offer steel grades that meet application-specific targets will increasingly determine commercial success. This trend benefits producers with strong internal R&D, application testing, and customer co-development capabilities. It also expands the opportunity set for hybrid solutions that combine steel with coatings or complementary materials, particularly in aerospace and high-performance industrial uses.
PW Consulting Health Care Research Center
The commercial opportunity lies not only in launching new grades but in building repeatable qualification pathways that reduce time-to-market for OEM programs. Companies that can shorten the loop between material development, validation, and production scale-up will capture a larger share of high-margin demand. The risk is that innovation cycles become expensive if not directed by clear end-use requirements, so disciplined portfolio targeting will matter as much as technical ambition.
Trend Two: Sustainability-Driven Procurement and Process Transformation
A second major trend is the deepening influence of sustainability criteria on procurement and production. Buyers are increasingly factoring carbon intensity, material traceability, and process transparency into supplier evaluations. This shift is encouraging investment in energy-efficient manufacturing, cleaner melting and refining practices, and documentation systems that support verifiable sourcing. The trend is especially relevant where automotive and aerospace customers operate under public decarbonization commitments and require supplier alignment.
Bearing for Steel Industry Market
For producers, the commercial implication is that sustainability can become a competitive parameter in its own right, not just a compliance requirement. Firms that can demonstrate credible progress and operationalize it across their product lines may gain preferential access to long-cycle contracts and co-development opportunities. The uncertainty lies in the pace and consistency of regulatory and customer requirements across regions, which can create uneven demand for “green” bearing steel until standards and expectations converge more fully.
Trend Three: Regional Specialization and Multi-Polar Supply Networks
The third trend is the continued regional specialization of demand and supply. Asia Pacific is expected to remain a substantial demand engine, while North America and Europe will likely sustain strength in advanced aerospace, industrial, and specialty automotive applications. This multi-polar structure encourages supply networks that are both regionally responsive and globally coordinated. Producers and bearing manufacturers that can manage this balance will be better positioned to reduce disruption risk while maintaining performance quality and delivery reliability.
The opportunity here is to design sourcing and production footprints that match the geography of high-value demand. For some companies, that means strengthening regional capacity or partnerships; for others, it means building flexible logistics and inventory strategies that support just-in-time performance without over-reliance on a single route. The risk is that regional fragmentation can raise duplication costs and complicate quality standardization, so the winners will be those who combine localized responsiveness with disciplined process control.
For Bearing Steel Producers and Material Developers
Producers should prioritize a focused portfolio strategy that distinguishes commodity continuity from advanced-grade growth. Commodity segments will remain essential for cash flow and scale, but value expansion is increasingly tied to specialty formulations, high cleanliness, and application-specific certification. It is strategically important to identify which end-use segments offer the best combination of performance premium, qualification feasibility, and volume potential, then align R&D and capacity decisions accordingly. Co-development with key bearing manufacturers and OEMs can shorten validation cycles and improve the likelihood that new grades translate into commercial adoption.
Operational resilience should also receive renewed attention. Energy efficiency, scrap and alloy management, and quality consistency are no longer just cost levers; they are strategic factors that influence customer trust and contract stability. Producers that can demonstrate both technical differentiation and dependable execution will be better positioned to maintain pricing power and expand into higher-value segments.
For Investors and Strategic Buyers
Investors should look beyond headline growth and assess where value is being created within the market. The most attractive exposure is likely in segments where advanced steel grades, certification depth, and application expertise translate into higher margins and stickier customer relationships. Vertical integration can be valuable when it secures quality and supply for high-performance bearings, but it is not universally superior; the optimal structure depends on whether a company’s advantage lies in steelmaking, bearing design, or both.
Valuation and due diligence should therefore focus on product mix, qualification pipelines, regional demand exposure, and the credibility of sustainability improvements. Companies with a clear link between material innovation and end-use performance are better positioned to capture the market’s projected growth trajectory. The main caution is that not all scale is equal: volume growth in undifferentiated segments may not generate proportional returns if pricing pressure and input volatility persist.
For Procurement and Engineering Leaders
Procurement and engineering leaders should treat bearing steel selection as a system-level decision rather than a standard commodity purchase. The performance requirements of aerospace, automotive electrification, and high-cycle industrial applications increasingly reward closer collaboration with suppliers on grade selection, cleanliness targets, and processing compatibility. Early engagement in the design and qualification phase can reduce downstream risk and improve total system efficiency, especially where new alloys or hybrid solutions are under consideration.
Supplier evaluation should incorporate not only price and delivery but also consistency of metallurgical control, traceability, and the ability to support evolving sustainability requirements. Diversifying the supplier base in a structured way can reduce exposure to regional disruptions while preserving access to advanced grades where needed. The key is to match sourcing strategy with application criticality: the more performance-sensitive the bearing system, the more important it is to secure partners with proven material expertise and reliable qualification support.
Why Timely Intelligence Matters Now
The bearing steel market is evolving quickly enough that decisions made on outdated assumptions can lock in suboptimal sourcing, product, or investment strategies. The combination of advanced alloy development, sustainability-driven procurement, and regional rebalancing means that competitive advantage is increasingly determined by how well companies understand shifting performance requirements and supply chain logic. Detailed segment-level data, application-specific demand patterns, and supplier capability assessments can make the difference between reactive adjustments and proactive positioning.
For organizations seeking a deeper view of these dynamics, the full PW Consulting research report provides more granular segmentation, regional breakdowns, and customized strategic recommendations tailored to specific business models and end-use exposures.
For detailed analysis of this topic, please visit the official page: Bearing Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com