

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
GET Market 2026: Why This 5.5% CAGR and $5.8B Outlook Changes Everything

Strategic Shifts and Commercial Opportunities in the Global Ground Engaging Tools Market
The global market for ground engaging tools has entered a period of structural evolution. Valued at approximately USD 4,050 million in 2025, the market is projected to reach USD 5,800 million by 2032, representing a compound annual growth rate of 5.5% over the forecast period. Growth is not uniform across all geographies or equipment categories, but the overall trajectory reflects a maturing industry where performance optimization, total cost of ownership, and operational uptime increasingly drive purchasing decisions. The market remains moderately concentrated, with the top three players accounting for roughly 48.5% of revenue and the top five capturing about 65.2%. This concentration underscores scale advantages in engineering, distribution, and aftermarket service, while leaving meaningful room for specialized innovators and regional specialists to differentiate on fit, durability, and service responsiveness.
For executives and investors, the core question is not whether the market will grow, but how value will be created and captured as the industry transitions from replacement-driven demand to performance-driven procurement. The following analysis examines the defining challenges, demand and supply forces, competitive strategies, and forward-looking trends that will shape commercial outcomes through the end of the decade.
Market Landscape and Defining Pressures
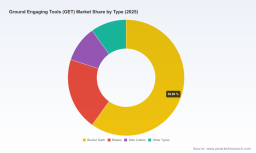
The ground engaging tools market spans a broad portfolio of wear components—bucket teeth, adapters, blades, side cutters, lips, and complete bucket protection systems—deployed across excavators, loaders, dozers, and a range of other earthmoving and mining equipment. Bucket teeth represent the largest product category, reflecting their universal role across general construction and mining applications. Excavators anchor the application side of the market, followed by loaders and dozers, with the balance distributed across specialized attachments and mixed fleets. Regionally, North America and Europe together form the largest revenue base, while Asia Pacific and Latin America represent structurally faster-growing theaters tied to infrastructure development and mining expansion.
Several intersecting pressures are reshaping how manufacturers, fleet operators, and distributors approach the category:
- Material volatility and specification rigidity. Carbon steel wear plates, cutting edges, and high-abrasion steels remain foundational to ground engaging tools, yet they are subject to supply constraints and price fluctuations. At the same time, industry standards for hardox wear plate and high-abrasion steel continue to govern material selection, anchoring cost structures and requiring disciplined sourcing strategies.
- Skilled labor constraints are changing the value equation. Shortages of skilled technicians for heavy machinery maintenance are pushing operators toward long-life ground engaging tools and designs that reduce manual intervention. Components that resist premature wear, simplify replacement, and extend service intervals are gaining preference over lowest-unit-price alternatives.
- Safety standards are raising the bar on design. ISO and mining safety standards increasingly demand secure locking mechanisms in ground engaging tools, influencing product architecture and limiting the viability of indirect, non-conforming substitutes in regulated mining environments.
Together, these pressures are compressing price-based competition while elevating durability, interchangeability, and safety-compliant engineering as the primary arenas of differentiation. The strategic implication is clear: vendors that can stabilize input costs, design for serviceability, and align with recognized safety and material specifications will command stronger margin pools than those competing primarily on price.
What Is Driving Change: Technology, Regulation, Demand, and Supply
Technology and design innovation
Product innovation is shifting from incremental material improvements toward integrated systems that protect buckets, extend component life, and support faster replacement. Recent developments illustrate this direction. In April 2026, Bradken updated its ground engaging tools catalog with enhanced Zenith Plate Lip and Eclipse Cast Lip solutions, signaling continued emphasis on high-performance mining ground engaging tools for face shovels, front-end loaders, and backhoe excavators. In May 2026, Sandvik introduced the Mako™ GET as a next-generation bucket protection system tailored for underground loader operations, reinforcing the trend toward engineered protection packages that improve durability and productivity in demanding environments. Later in the same month, Haladjian Mining completed new ESCO® MaxDRP™ Ripper GET system installations for mining dozers, demonstrating how complete, specification-aligned systems are being deployed to optimize performance and equipment life in mining dozers and excavators.
Excavator Attachments Market
These releases share a common thread: they are not isolated wear parts but engineered systems designed to reduce operating costs and downtime. For manufacturers, the opportunity lies in bundling teeth, adapters, lips, and bucket protection into coherent configurations that simplify specification, improve fit, and reduce the risk of premature failure. For operators, this aligns with the broader industry shift toward monitored wear systems and digital monitoring technologies, which are accelerating adoption of data-informed maintenance decisions and creating a stronger link between component design and telemetry-compatible service models.
Policy and regulatory environment
Regulatory and standards-driven requirements are becoming a more decisive factor in product design and procurement. ISO and mining safety standards require secure locking mechanisms in ground engaging tools, which narrows the feasible design space and rewards manufacturers that can deliver compliant, field-proven solutions. Material specifications—particularly standards for hardox wear plate and high-abrasion steel—continue to shape what can be used in high-wear applications, reinforcing a preference for traceable, spec-aligned inputs in mining and regulated construction settings.
The commercial consequence is dual-edged. On one hand, compliance narrows the path for low-cost, non-conforming competitors and strengthens the moat for established engineering organizations. On the other hand, it imposes design and certification overhead that smaller entrants must manage carefully. Organizations that anticipate specification changes and invest in documented material traceability and locking-system integrity will find it easier to win and retain contracts in regulated segments.
Worldwide Ground Stabilization Geogrid Market
Demand-side behavior and fleet economics
Demand is being shaped less by headline equipment sales alone and more by how operators manage total cost of ownership. The decision to replace a tooth, adapter, or bucket protection system is increasingly evaluated against downtime, labor availability, and the durability of the installed configuration. In markets where skilled labor is scarce, long-life ground engaging tools and systems that reduce handling and installation time carry a premium. In mining, where machine utilization directly influences throughput, complete ground engaging systems that combine teeth, lips, adapters, and wear packages are gaining traction because they simplify specification and reduce variability in wear performance.
PW Consulting
In the aftermarket, the demand picture is broadening as fleets seek compatible wear parts that can be integrated across OEM and non-OEM equipment. A robust aftermarket ecosystem that offers teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major manufacturer systems remains attractive to mixed-fleet operators who prioritize flexibility and uptime over single-brand lock-in. The practical insight for buyers is that compatibility, interchangeability, and documented performance across equipment types are becoming as important as the unit price of individual components.
Supply chain and cost structure dynamics
Cost structures are being pressured from both ends. On the input side, carbon steel wear plates and cutting edges are subject to supply constraints and price fluctuations, which can erode margins if not managed through specification discipline and supplier diversification. On the output side, competitive intensity among large, well-capitalized players and capable aftermarket specialists limits how much of those costs can be passed through in price-sensitive segments. The net effect is a strategic emphasis on design efficiency, material optimization, and service economies.
Manufacturers that can standardize high-performing configurations, reduce waste in fabrication, and align inventory with real wear patterns are better positioned to stabilize margins. At the same time, companies that can maintain regional service proximity and quick-turn availability for critical wear parts gain a measurable edge in markets where downtime is costly and logistics are complex.
Competitive Landscape and Strategic Positioning
The market’s moderate concentration reflects a layered competitive structure. Large, multi-brand manufacturers bring engineering scale, broad product lines, and integrated service networks. Specialized mining-focused producers compete on performance in demanding applications, often with differentiated lip, tooth, and wear-package designs. Aftermarket specialists provide broad compatibility and rapid local availability across major systems, enabling mixed-fleet operators to maintain uptime without full OEM dependence. The result is a market where scale, specialization, and service proximity each create distinct competitive advantages.
Several players illustrate how these advantages are being exercised:
- Caterpillar Inc. leverages a full line of ground engaging tools—including cutting edges, teeth, adapters, bucket protection, and Advansys systems—across excavators, wheel loaders, dozers, and mixed fleets. Its strategy emphasizes reducing operating costs and downtime, and recent moves such as extending Cat GET systems to support third-party buckets broaden the addressable market beyond proprietary equipment. This is a clear play to combine engineering credibility with fleet flexibility.
- ESCO Group LLC focuses on engineered lips, teeth, adapters, and full ground engaging systems for mining excavators, rope shovels, wheel loaders, and draglines. Its orientation toward optimizing performance and extending equipment life positions it strongly in mining applications where wear performance and system fit are closely scrutinized.
- Bradken Limited emphasizes high-performance mining ground engaging tools with differentiated solutions such as Zenith Plate Lip and Eclipse Cast Lip, along with bucket wear packages for face shovels, front-end loaders, and backhoe excavators. Its focus on demanding mining applications and periodic catalog refreshes illustrates a commitment to updating product architecture in line with field requirements.
- Sandvik AB provides the Shark™ GET range with Mako™ systems, Blue Pointer 2, profile bars, shrouds, and mechanical locking for underground mining buckets. The emphasis on durability, productivity, and mechanical locking aligns directly with safety and performance expectations in underground mining and demonstrates a systems-level approach to bucket protection.
- ITR America and ITR Africa operate extensive aftermarket lines of teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major OEM systems for earthmoving equipment. Their value proposition centers on compatibility and availability across dozers, loaders, and excavators, which is especially relevant for mixed-fleet operators and regions with distributed service needs.
- Cutting Edge Supply offers a full range of aftermarket ground engaging tools—including cutting edges, teeth, adapters, buckets, and attachments—using alloy steels and hardox wear parts. This positions the company as a practical source for operators seeking spec-aligned materials and broad coverage in construction and earthmoving applications.
- Haladjian Mining provides the ESCO® MaxDRP™ Ripper GET systems, teeth, lips, and wear parts for mining dozers and excavators, supported by distributor-level installation activity. Its role highlights how regional execution and system-level offerings can deliver performance improvements in specific mining contexts.
Strategically, the market is evolving along three vectors. First, scale players are extending compatibility and service reach to capture value beyond proprietary equipment, as seen in moves to support third-party buckets with engineered ground engaging systems. Second, mining specialists are refining system designs and lip/teeth architectures to address high-wear conditions more effectively, often refreshing catalogs and product lines in response to field feedback. Third, aftermarket specialists continue to build regional density and compatibility breadth, making them indispensable to operators who manage diverse equipment pools. New entrants face the highest barriers where certification, material traceability, and locking-system integrity are required, but opportunities remain for focused innovators that can deliver differentiated wear performance, faster replacement, or telemetry-compatible service models.
Outlook Through 2032: Three Trends and What They Unlock
Looking ahead three to five years, the market direction is shaped by the convergence of material constraints, safety and specification requirements, and the growing importance of uptime economics. The following trends are likely to define commercial outcomes:
- From replacement parts to performance systems. Buyers will increasingly evaluate ground engaging tools as integrated protection and wear-management systems rather than collections of individual components. This favors manufacturers that can bundle teeth, adapters, lips, and bucket protection into coherent, documented configurations and provide guidance on specification and replacement intervals. Commercial opportunity lies in packaging, compatibility, and service-backed performance guarantees that reduce uncertainty for operators.
- Digital monitoring and data-informed wear management become mainstream. The accelerating adoption of monitored wear systems and digital monitoring technologies will link component design more tightly to usage data and maintenance planning. Over time, this creates opportunities for condition-based replacement, better inventory forecasting, and service offerings tied to actual wear rather than fixed schedules. The risk is that organizations without telemetry-compatible designs or data-driven service capabilities may lose share in fleets that prioritize predictive maintenance.
- Regional differentiation intensifies as cost and service pressures diverge. In price-sensitive segments, competition will remain tight, but in mining and regulated construction environments, durability, safety-compliant locking, and material traceability will command premiums. Regions with strong mining activity or infrastructure build-out will see faster demand growth for high-performance configurations, while mature markets will emphasize aftermarket breadth, component longevity, and mixed-fleet compatibility. Companies that localize service and inventory intelligently will capture more value than those relying on centralized, slow-turn models alone.
Potential risks and uncertainties should be monitored closely. Material price volatility and supply constraints can compress margins if input strategies are not diversified. Changes in safety and material standards can require redesigns and recertification, disproportionately affecting players with limited engineering bandwidth. Labor shortages can both increase demand for long-life tools and disrupt aftermarket execution if service capacity is insufficient. Finally, if monitored wear systems and digital tracking become widely adopted, data ownership and integration with fleet management platforms could emerge as new points of competitive differentiation, introducing vendor-lock-in considerations for operators.
Actionable Guidance for Decision-Makers
The commercial terrain is shifting from unit-price competition toward performance, compatibility, and service-driven value. Different roles in the value chain should respond accordingly.
For manufacturers and product leaders
- Design for system-level value. Prioritize configurations that combine teeth, adapters, lips, and bucket protection in documented packages that reduce specification complexity and downtime. Compatibility with major systems and support for third-party buckets can broaden addressable demand while preserving engineering credibility.
- Build resilience into the cost base. Diversify material sourcing for carbon steel wear plates and cutting edges, maintain spec-aligned documentation for hardox and high-abrasion steel usage, and standardize high-performing configurations to reduce fabrication waste and improve margin stability.
- Prepare for data-linked service. As monitored wear systems and digital monitoring technologies become more common, ensure component designs and service processes can integrate with usage data. This positions the product portfolio for condition-based maintenance offerings and more predictable aftermarket demand.
For investors and strategic planners
- Focus on durability economics. In a market where skilled labor is scarce and downtime is costly, long-life ground engaging tools and safety-compliant locking mechanisms have structural appeal. Evaluate exposure to regulated mining and infrastructure segments where performance and compliance can support stronger pricing power.
- Assess competitive moats by service proximity and compatibility breadth. Aftermarket specialists that combine spec-aligned materials with broad compatibility across OEM systems can sustain demand in mixed-fleet environments. Scale players with integrated service networks and expanding compatibility also warrant attention, especially where they can monetize uptime benefits beyond proprietary equipment.
- Watch for consolidation pressure in regional distribution. As product lines become more system-oriented and monitoring technologies mature, distribution models that can deliver fast-turn availability and technical support will gain importance. Gaps in regional service density may create both acquisition opportunities and execution risks.
For procurement, fleet managers, and contractors
- Specify for total cost of ownership, not just unit price. Evaluate ground engaging tools and systems against durability, replacement time, compatibility with existing equipment, and the reliability of locking mechanisms. In labor-constrained environments, designs that are durable and easy to service can reduce hidden costs that are often larger than the component price itself.
- Standardize where it pays. For mixed fleets, prioritize wear parts and systems with proven compatibility across major manufacturer configurations to simplify stocking, reduce errors, and keep equipment running. Documented performance and safety-compliant designs should be weighted alongside cost when making specification decisions.
- Plan inventory around real wear patterns. As monitored wear systems become more widespread, align stocking and replacement planning with actual usage data rather than fixed intervals. This reduces both stockouts and overstock, especially for high-wear applications in mining and heavy construction.
The most consequential decisions in this market will be made by organizations that can translate material constraints, safety requirements, and uptime economics into coherent product, sourcing, and service strategies. For readers seeking a more detailed segmentation view, regional demand pathways, and tailored recommendations for specific equipment categories and growth markets, the full PW Consulting study on the Ground Engaging Tools market provides deeper sub-segment data and customized guidance to support planning with precision.
For detailed analysis of this topic, please visit the official page: Ground Engaging Tools (GET) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com