

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Remittance Market 2026: Why 15.8% CAGR Growth Changes Everything

The Digital Remittance Market: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Landscape
Market Overview and Core Challenges
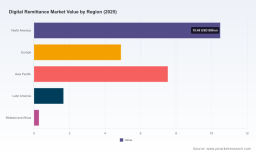
The digital remittance market has transitioned from a niche convenience to a fundamental infrastructure layer for global money movement. Between 2020 and 2025, the sector expanded from approximately $8.7 billion to nearly $24.9 billion, reflecting a compound annual growth rate of 15.8% over the period. Looking ahead to 2032, trajectory modeling suggests the market will reach roughly $69.4 billion, sustained by the same structural forces that accelerated adoption over the past half-decade. Growth is not uniform across all segments, but the overall expansion signals a durable shift away from cash-dependent, branch-heavy transfer models toward digital, mobile-first, and increasingly automated channels.
Despite the headline momentum, the industry sits at a critical inflection point. Three interconnected challenges define the current environment. First, regulatory fragmentation continues to raise the cost of cross-border compliance, particularly for providers operating across multiple jurisdictions with divergent anti-money laundering and consumer protection standards. Second, the economics of last-mile delivery remain strained, especially in markets where telecommunications infrastructure costs, spectrum licensing, and agent network maintenance compress margins. Third, customer expectations have reset the competitive baseline: speed, transparency, and low friction are no longer differentiators; they are table stakes, which puts pressure on incumbent cost structures and forces continuous reinvestment in technology and partnerships.
These pressures are not purely defensive. They are reshaping who can compete, how value is captured, and where the next wave of margin improvement will originate. For decision-makers, the practical question is not whether digital remittance will keep growing, but which structural shifts will determine winners and laggards over the next several years.
Key Drivers of Market Change
Technological Innovation and Platform Integration
Technology is compressing the distance between origination and receipt while simultaneously lowering the marginal cost of each transfer. Mobile applications, messaging-based interfaces, and wallet integrations are extending reach into contexts where traditional banking penetration is limited but smartphone and data connectivity are expanding rapidly. Real-time payment rails, programmable settlement, and API-first infrastructure are enabling providers to embed remittance capabilities into broader financial and commercial workflows rather than treating them as standalone transactions.
The shift toward messaging and conversational interfaces illustrates how product design is expanding access. Recent product launches have shown providers using familiar communication platforms to reduce friction for both senders and recipients, including features that allow recipients to initiate requests directly and expansions of message-based sending into additional countries. In parallel, stablecoin-based settlement experiments are being used to test faster, more predictable cross-border movement of value, particularly where traditional correspondent banking routes are slow or expensive. These developments do not replace the need for strong compliance and liquidity management, but they do change the operating model by moving more of the transaction lifecycle into digital, traceable, and automatable workflows.
Policy and Regulatory Environment
Regulation remains one of the most powerful levers shaping market structure, cost, and speed. In the United States, new federal excise tax provisions on certain remittance transfers funded by cash, money orders, or cashier's checks have introduced a differentiated cost environment, with digitally funded transfers using bank or card sources exempt from the tax. Proposed regulatory clarifications around the scope of remittance transfer taxation further signal that policymakers are actively defining which channels and funding methods fall under new obligations. For operators, this creates both a pricing dynamic and a strategic incentive to steer customers toward digital funding paths that are more efficient from a tax and compliance standpoint.
At the same time, international regulatory bodies have been tightening expectations around risk-based oversight for digital channels. Guidance emphasizing AML/CFT compliance for digital remittance providers reflects a broader push to ensure that faster, more automated channels do not weaken oversight. Complementary analysis from multilateral forums has highlighted persistent licensing and regulatory barriers that can slow digitization, particularly for non-bank providers seeking to operate across borders. The net effect is a market where compliance capability is becoming a competitive asset rather than a back-office function. Providers that can align product design, onboarding, monitoring, and reporting with evolving requirements are better positioned to scale without running into structural bottlenecks.
Shifts in Consumer and Business Behavior
Demand-side behavior is changing on two tracks. For personal users, the expectation is increasingly about seamless, low-cost, and trackable transfers that fit into daily digital routines. Senders want clarity on fees and exchange rates, while recipients often prefer immediate availability through local wallets, bank accounts, or cash pickup where digital liquidity is not yet universal. This dual expectation pushes providers to offer multiple payout options and to optimize for local relevance rather than a single global template.
On the business side, cross-border payments are becoming more embedded in operational workflows. Companies that source, pay, or employ across jurisdictions need predictable settlement, multi-currency management, and automation that reduces manual intervention. This has increased interest in infrastructure-oriented solutions that connect enterprises to local payout networks and provide FX and payment capabilities in a more integrated form. As a result, the market is not only expanding in volume but also broadening in use cases, with business-driven flows becoming a meaningful component of overall digital remittance activity.
Cost Structure and Infrastructure Dynamics
The cost side of the market is being redefined by both technology and local infrastructure conditions. Digital channels can reduce some legacy handling costs, but they do not eliminate the expense of maintaining liquidity, managing FX exposure, meeting compliance requirements, and delivering reliable last-mile payouts. In some regions, telecommunications and spectrum-related costs add measurable pressure to the operating environment, affecting the economics of mobile-based delivery and agent-supported networks. Where infrastructure costs are elevated, providers must either absorb them, pass them through carefully, or redesign distribution to reduce dependence on high-cost pathways.
This creates an opportunity for differentiation based on distribution efficiency. Providers that can combine digital onboarding with optimized payout routing, selective partnerships, and stronger working capital management can improve unit economics even in challenging local conditions. Conversely, operators that rely on high-cost legacy touchpoints without sufficient automation may find margin expansion difficult, especially as customers compare experiences across increasingly transparent pricing environments.
Competitive Landscape and Leading Strategies
The competitive field blends established global transfer brands, technology-native platforms, and infrastructure-focused providers. Each group is pursuing a different angle of value creation, and the landscape is evolving through a mix of expansion, consolidation, and targeted partnership activity.
Several leading players have built their positioning around transparency, speed, and channel convenience. Some emphasize predictable exchange rates and low-cost bank-funded transfers, appealing to users who prioritize clarity and efficiency. Others leverage extensive agent and pickup networks alongside digital channels, preserving cash-oriented access while modernizing the front end. A third cohort focuses on platform and messaging integration, using familiar consumer touchpoints to expand reach and reduce onboarding friction. These divergent approaches reflect different assumptions about where the biggest growth and retention leverage lies: price transparency, physical reachability, or digital convenience.
A separate but increasingly important set of players operates more as enabling infrastructure than as consumer-facing brands. These providers supply cross-border payment and remittance capabilities to fintechs, banks, and enterprises, often emphasizing real-time settlement, multi-currency accounts, and localized payout capabilities. Their growth illustrates a broader trend: as more entities seek to embed international money movement into their own products or operations, the demand for robust backend rails and compliance-ready integrations is rising.
PW Consulting
Recent activity shows how companies are trying to extend their advantage. One global provider expanded a messaging-based sending feature into additional markets and introduced a recipient-initiated request capability, reinforcing a strategy centered on reducing friction and increasing engagement through familiar communication channels. Another major player introduced a stablecoin tied to its remittance network, signaling an interest in using digital asset infrastructure to support faster settlement and network expansion. A separate cross-border platform secured a partnership to enable transfers directly into a major regional wallet and linked bank accounts, highlighting the continued importance of local payment system access in high-volume markets.
Digital Insurance Market
Taken together, these moves point to a market that is both consolidating around strong digital brands and fragmenting through specialized infrastructure plays. Incumbents are modernizing distribution and experimenting with new settlement models, while newer and mid-sized players are carving out niches based on enterprise needs, regional payout strength, or integration depth. The likely trajectory over the next few years is not a single dominant model, but a layered ecosystem in which consumer-facing brands, B2B infrastructure providers, and local access partners compete and cooperate simultaneously.
Future Trends and Commercial Opportunities
Deeper Integration of Messaging, Wallets, and Embedded Flows
Over the next three to five years, digital remittance is likely to become less visible as a standalone product and more embedded into everyday digital interactions. Messaging-based requests, wallet-to-wallet movement, and integration with broader financial apps will continue to reduce the steps between intent and completion. For commercial players, this creates opportunities to design products that are not just about moving money, but about supporting the surrounding workflows: bill payment, family support, supplier settlement, and payroll-related cross-border needs. The winners will be those that can make the transfer experience feel local, immediate, and contextually relevant rather than generic and transactional.
Regulatory Capability as a Competitive Moat
As tax rules, licensing expectations, and compliance guidance continue to evolve, regulatory competence will increasingly separate scalable operators from those that face repeated friction. Providers that invest early in compliant digital onboarding, transaction monitoring, and transparent funding-path design will be better placed to manage cost exposure and expand into new corridors. There is also an opportunity for providers that can help customers navigate differentiated tax and funding environments by steering them toward more efficient digital channels, provided this is done with clear communication and strong compliance foundations. In practical terms, regulatory readiness will become part of the product value proposition, not just a legal requirement.
Stable Settlement Innovation and Corridor-Specific Optimization
Experiments with stablecoin-based settlement and other digital asset infrastructure are likely to mature in select corridors where speed, FX certainty, and liquidity management matter most. This does not imply uniform adoption across all markets; instead, it suggests a corridor-by-corridor optimization dynamic. Where traditional rails are slower or more expensive, digital settlement layers may offer meaningful improvements, especially when paired with strong local payout partners and robust risk controls. The commercial opportunity lies in identifying which corridors benefit most from alternative settlement, building reliable liquidity and compliance support around them, and integrating these capabilities without disrupting the customer experience.
These trends carry risks. Regulatory changes can shift cost structures quickly, especially where tax treatment or licensing rules differentiate between funding methods or provider types. Infrastructure costs in certain regions can constrain distribution economics, making it harder to scale without a tailored model. FX volatility, liquidity management, and fraud or misuse risks remain persistent challenges in any high-volume cross-border environment. Finally, customer adoption can be uneven: digital convenience expands reach, but not every recipient market is ready for fully digital payout, which means hybrid models will remain necessary for years.
Strategic Recommendations for Decision-Makers
For executives, investors, and operators evaluating the digital remittance space, the most useful lens is to treat the market as a set of shifting cost, compliance, and distribution dynamics rather than as a simple volume growth story. The following actions can help translate that perspective into better decisions.
Digital Banking Market
- Align product and funding-path design with the changing cost and tax environment. Where digital bank- or card-funded transfers carry different implications than cash-based funding, optimize the experience to make the more efficient path attractive and easy to use, while maintaining clear customer communication and compliance integrity.
- Invest in compliance and operational scalability as core product capabilities. Strong onboarding, monitoring, reporting, and licensing readiness should be treated as enablers of expansion, especially for providers planning to enter new corridors or serve business customers with higher documentation and control expectations.
- Build corridor-specific distribution strategies instead of relying on a single global template. Local payout preferences, wallet penetration, agent networks, and infrastructure costs vary widely. Tailoring routing, partnerships, and payout options to local conditions can improve unit economics and customer satisfaction more reliably than standardizing every market.
- Evaluate infrastructure and partnership plays for enterprise and embedded use cases. As more businesses and platforms seek integrated cross-border payment capabilities, there is room to capture value by providing reliable rails, multi-currency management, and localized settlement support, particularly when paired with strong FX and automation features.
- Monitor settlement innovation selectively and operationally. Where alternative settlement models can improve speed or cost in specific corridors, test them with disciplined risk controls and liquidity management. Avoid broad commitments until the corridor economics, regulatory stance, and customer readiness are well understood.
The strategic value of detailed intelligence in this market is high because the differences between corridors, funding paths, compliance regimes, and distribution models can decisively affect profitability and scalability. Broad market narratives are useful for orientation, but operational decisions depend on finer-grained insight into where growth is concentrated, which channels are most efficient, how regulatory changes alter cost structures, and which partnership or infrastructure models fit a given business profile. For leaders who need that level of clarity, a full research report can provide the segmented data, corridor-level context, and customized strategic guidance necessary to move from directional confidence to executable planning.
For detailed analysis of this topic, please visit the official page: Digital Remittance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com