

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydro Turbine Generator Market: The 5.0% CAGR Shift from Asia Pacific and Francis Turbines

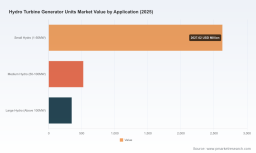
Strategic Trends and Commercial Opportunities in the Hydro Turbine Generator Units Market
The global hydro turbine generator units market has entered a phase of measured but meaningful expansion, underpinned by a decade of steady capital deployment and a clear shift toward modernizing aging assets. The market, valued at approximately $2.6 billion in 2020, reached an estimated $3.5 billion in 2025, with projections indicating a trajectory toward $5.4 billion by 2032. This growth path corresponds to a compound annual growth rate of roughly 5.0 percent, reflecting a market that is expanding at a pace consistent with broader infrastructure and clean energy investment cycles while avoiding the volatility often seen in nascent technology segments.
The trajectory is not a simple function of new capacity additions. Instead, it reflects a layered dynamic: new large-scale projects continue to contribute, but the dominant near-term driver is the rehabilitation, uprating, and digital modernization of existing installations. This structural shift matters for commercial strategy because it changes the nature of demand from episodic greenfield events to a more continuous pipeline of service, component replacement, and efficiency upgrades. For decision-makers, the consequence is straightforward: the market's center of gravity is moving toward lifecycle value, performance reliability, and the ability to extract more output from existing water infrastructure.
Core Challenges and Inflection Points
Despite the positive outlook, the market faces a set of practical challenges that shape how value is created and captured. One of the most significant is the tension between long project lead times and the urgency of decarbonization and grid modernization. Hydropower development typically requires extended permitting, environmental review, and civil engineering preparation. This creates a mismatch between political or corporate ambition and execution speed, particularly in regions where regulatory processes are still evolving. The result is a market where strategic planning must account for multi-year horizons, and where companies that can compress timelines through modular design, standardized equipment, or strong local execution capability gain a durable advantage.
A second challenge lies in cost structure variability and supply chain sensitivity. Turbine and generator projects involve substantial steel-intensive manufacturing, specialized machining, and customized engineering tied to site-specific hydraulic conditions. Cost ranges can vary widely depending on unit size, turbine type, and installation complexity, which means margin discipline depends heavily on scope control, localization, and the ability to manage input cost fluctuations. At the same time, trade dynamics are shifting. In the United States, for example, imports of hydraulic turbines rebounded significantly in 2024, signaling that domestic demand is not always matched by local manufacturing capacity alone. This underscores the importance of understanding where procurement will be sourced, how logistics affect final delivery, and which suppliers can offer both technical credibility and regional responsiveness.
A third inflection point is the growing importance of the upgrade and rehabilitation segment. In the U.S. alone, capacity additions from turbine-generator upgrades amounted to hundreds of megawatts as of mid-2025, a clear sign that existing plants are becoming a major source of new productive output. This trend is not merely a short-term substitute for greenfield development; it reflects a deliberate strategy to increase generating efficiency, extend asset life, and improve grid reliability without the full cost and risk of new dam construction. For equipment suppliers and service providers, the implication is that aftermarket capability, retrofits, and performance optimization are becoming strategic rather than supporting activities.
Key Drivers Shaping Market Direction
Technology Innovation and Performance Enhancement
Technical advances are reshaping what hydro assets can deliver. One of the most commercially relevant shifts is the continued uprating of existing turbine-generator sets to increase output without proportionally expanding civil works. Recent large-scale rehabilitation projects demonstrate this pattern clearly: at Old Hickory Power Plant, Kaplan units were replaced and uprated from 25 MW to 45 MW each, expanding productive capacity enough to support roughly 125,000 homes. This kind of outcome is compelling for asset owners because it combines higher generation with retrofit execution rather than entirely new construction.
Beyond output gains, digitalization and automation are increasingly central to how hydropower equipment is specified and operated. Modernization contracts now frequently include controls, supervision, testing, and commissioning as integrated parts of the package, not optional add-ons. This reflects a broader market expectation that turbine generator units should be delivered with better integration between mechanical hardware and plant-level intelligence. As a result, companies that can provide both electro-mechanical equipment and the systems that optimize performance over time are positioned more strongly than those competing on hardware alone.
Policy and Regulatory Environment
Policy stability is a decisive factor in hydropower investment, and recent developments have reinforced the attractiveness of conventional hydro and pumped storage in several markets. In the United States, legislation signed in 2025 retained key investment and production tax credits for conventional hydropower and pumped storage through 2033. This continuity reduces uncertainty for long-cycle projects and strengthens the financial case for both new installations and major upgrades. For commercial strategy, the practical implication is that policy support is no longer just a background condition; it is a planning variable that affects project timing, financing structures, and the relative appeal of different technology choices.
At the same time, grid connection reform is becoming a critical enabler. Regulatory bodies in several regions have moved to reduce speculative project entries and accelerate the integration of pumped storage and hydropower into system planning. When grid access becomes more predictable, hydropower projects can progress with less risk of delays that erode returns. This is especially relevant for turbine generator suppliers, because faster and more reliable connection pathways improve the prospects for equipment orders and reduce the chance that projects stall before procurement decisions are finalized.
Demand-Side Shifts and Asset Owner Priorities
Demand is being shaped not only by new generation targets but also by how utilities, public authorities, and independent operators view hydropower within a broader energy mix. Hydropower is increasingly valued for dispatchability, storage potential, and its ability to complement variable renewables. That changes the purchasing lens: buyers are less focused solely on lowest initial equipment cost and more attentive to reliability, uptime, service responsiveness, and the ability to integrate with evolving grid requirements.
This shift is visible in the types of contracts being awarded. Large rehabilitation and modernization orders are being placed with suppliers capable of delivering turbines, generators, and associated auxiliaries as part of coordinated projects. The demand pattern suggests that asset owners prefer fewer, more integrated partnerships over fragmented procurement, particularly where projects involve complex installation supervision and commissioning. For suppliers, this means the commercial battleground is moving toward capability breadth, execution credibility, and lifecycle support rather than unit price alone.
Supply Chain and Cost Structure Dynamics
Cost structure remains one of the most practical drivers of competitiveness. Hydropower equipment manufacturing is capital intensive and strongly influenced by the cost of steel, machining capacity, and skilled labor. Because turbine and generator costs can vary substantially by size and type, project economics are sensitive to manufacturing efficiency, sourcing strategy, and the ability to standardize where possible without compromising site-specific performance.
The supply chain is also showing signs of regional rebalancing. Increased import activity in certain markets indicates that local manufacturing does not always meet demand in the near term, while international suppliers with strong project execution records continue to win major orders. At the same time, the rehabilitation pipeline is creating demand for specialized components, retrofits, and replacement units that require both technical precision and timely delivery. Suppliers that can manage this balance—offering proven designs, reliable manufacturing, and responsive project support—are likely to capture disproportionate share in a market where downtime and schedule risk are costly.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The market is characterized by a meaningful degree of concentration, but it also contains a diverse set of participants with distinct positioning. Large, full-line suppliers have an advantage in major projects because they can deliver turbines, generators, automation, and associated auxiliaries within a coordinated framework. This breadth reduces integration risk for buyers and supports more complex rehabilitation or new-build programs. Companies with established footprints in both large and small hydro are particularly well placed to capture demand across a range of project sizes, which is valuable in a market where opportunities are dispersed across regions and asset classes.
Differentiation is increasingly tied to execution track record and service integration rather than product presence alone. Recent activity illustrates this pattern. ANDRITZ, for instance, has continued to secure substantial orders for both rehabilitation and new equipment, including modernization work in Thailand, a major rehabilitation order in Mozambique, and equipment orders for new Austrian projects. These assignments reinforce a positioning based on large-scale electro-mechanical supply, project supervision, and commissioning capability. GE Vernova has similarly engaged in refurbishment work, reflecting the strategic importance of established relationships in upgrading existing assets. Siemens Energy's emphasis on automation and controls aligns with the broader market shift toward integrated plant-level solutions.
In the smaller and medium-scale segment, the competitive logic is different. Here, specialization, design flexibility, and suitability for lower-head or constrained sites can matter more than full-line scale. Suppliers focused on micro and small hydro often compete on ease of deployment, material choices, and fit-for-purpose turbine designs. This creates room for niche players to build strong positions in specific geographies or application profiles, particularly where site conditions favor compact or specialized equipment.
Market Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape appears to be evolving along several axes at once. On one side, large projects continue to reward suppliers with global reach, robust engineering capacity, and the ability to manage complex delivery. On the other, the rehabilitation trend is creating demand for companies that can respond quickly with retrofit expertise and reliable aftermarket support. This dual structure encourages both consolidation among players seeking broader capability bundles and differentiation among those serving specialized niches.
New entry is possible but not trivial. The market's technical demands, long project cycles, and need for proven reliability raise barriers for entrants lacking manufacturing scale or documented project experience. However, the spread of small and medium hydro opportunities, along with the continued relevance of modernization work, means that focused suppliers can still build defensible businesses by concentrating on specific turbine types, regional markets, or application segments. The most durable positioning tends to combine technical credibility with the ability to execute reliably in local conditions.
Future Trends and Commercial Implications
Trend One: Rehabilitation and Uprating as a Core Growth Engine
Over the next three to five years, rehabilitation and uprating are likely to remain central to market growth. Many existing plants operate with equipment that can be upgraded to improve output, efficiency, and reliability. As utilities and public operators face pressure to maximize the value of existing infrastructure, the commercial opportunity will increasingly lie in offering upgrade packages that include turbine and generator replacement, controls modernization, and commissioning support. This trend benefits suppliers with strong field service capabilities and the ability to design retrofits that minimize downtime and integration risk.
Worldwide Geothermal Turbines Market
For investors and manufacturers, the strategic implication is that lifecycle-oriented offerings should be treated as a primary growth path rather than a secondary revenue stream. The ability to bundle equipment with performance improvements and service continuity can strengthen margins and customer retention, especially in markets where new construction is constrained by permitting or capital availability.
Trend Two: Greater Integration of Digital and Automation Solutions
A second trend is the deepening integration of automation, control systems, and performance monitoring into hydro turbine generator packages. As grid requirements become more demanding and asset owners look for better operational visibility, equipment purchases are increasingly evaluated through the lens of plant-level outcomes rather than isolated component specification. Suppliers that can deliver coordinated hardware and control strategies will be better positioned to win complex bids and support long-term value creation.
This trend also creates opportunities in predictive maintenance, efficiency optimization, and remote performance support. Even where the core turbine generator hardware remains the cornerstone of the transaction, the value of complementary digital services is likely to rise. Companies that treat digital capability as integral to the product—not an afterthought—can differentiate in a market where many competitors offer similar mechanical solutions.
The related implication for procurement and planning is that buyers should evaluate suppliers based on total system performance and support capacity, not just initial equipment specifications. In practice, this means giving weight to installation supervision, testing, commissioning, and post-delivery service when comparing bids.
Trend Three: Regional Rebalancing and Supply Chain Adaptation
A third trend is likely to be continued regional variation in demand and sourcing. Some markets will lean more heavily on imports or international suppliers for specialized equipment, while others will seek greater localization to reduce logistics risk or support domestic industrial policy. This uneven landscape will reward suppliers with flexible manufacturing, strong logistics coordination, and the ability to adapt offerings to regional procurement expectations.
The commercial opportunity here lies in building regional relevance without abandoning global technical standards. Suppliers that can combine engineering consistency with local partnerships, service presence, or manufacturing proximity are well placed to navigate this environment. At the same time, project developers and procurers should monitor trade and import patterns closely, because shifts in sourcing can affect lead times, cost estimates, and the resilience of project schedules.
Risks and Uncertainties
These trends are promising, but they are not without uncertainty. Hydropower projects remain vulnerable to permitting delays, environmental scrutiny, and long approval cycles. Cost pressures in steel and skilled labor can affect both project viability and supplier margin structure. Policy support may be strong in some jurisdictions but less predictable in others, creating uneven conditions across regions. In addition, grid connection reforms and integration processes can accelerate or slow project development depending on local implementation. These variables mean that market opportunity should be assessed with an explicit focus on where execution risk is manageable and where supplier capabilities match the project environment.
PW Consulting
Strategic Actions for Decision-Makers
For Manufacturers and Equipment Suppliers
Position the portfolio around lifecycle value. Growth in rehabilitation and uprating means that successful suppliers will need to compete as much on retrofit capability, service integration, and uptime performance as on new-unit specifications. Investing in modernization packages, controls compatibility, and field execution strength can create a clearer competitive edge than competing on equipment breadth alone.
Build regional responsiveness without sacrificing technical consistency. Where import patterns and local procurement expectations are shifting, the ability to provide reliable delivery, localized support, and adaptable project execution can matter as much as the core product. For companies serving multiple geographies, this may mean strengthening partnerships, service footprints, or manufacturing flexibility in strategically important markets.
Emphasize integrated delivery where it matters most. Many large orders now include turbines, generators, auxiliaries, and commissioning in a single program. Suppliers that can reduce integration risk for buyers and coordinate complex delivery are more likely to win preference in competitive situations, especially where asset owners seek to streamline procurement and minimize coordination burden.
For Investors
Evaluate the rehabilitation and service opportunity as a structural part of the market, not a cyclical add-on. Upgrading existing plants offers a more predictable demand environment in some regions than entirely new hydro development, and it can provide recurring revenue potential through service and modernization activity. Projects or companies with strong aftermarket capability and established relationships with asset owners may be better positioned to capture this value.
Hydroelectric Generator Repair Market
Watch for policy and grid connection developments as leading indicators. Tax credit continuity, storage-related incentives, and grid integration reforms can materially affect project pacing and the attractiveness of hydropower investments. Understanding where these conditions are most supportive can help prioritize where to allocate attention and capital.
Assess supply chain resilience as part of the investment thesis. Because hydropower equipment is steel-intensive and project-specific, sensitivity to input costs, manufacturing capacity, and logistics is high. Companies with disciplined cost control, diversified sourcing, and proven execution are more likely to sustain margins through market variability.
For Procurement and Asset Owners
Prioritize total value over lowest initial price. In a market where rehabilitation, uprating, and integration are increasingly important, long-term performance, commissioning support, and service availability can have a greater effect on project outcomes than headline equipment cost. Procurement strategies should reflect this by weighting reliability, service responsiveness, and system integration in supplier evaluations.
Align procurement with the asset strategy. If the goal is to increase output from existing infrastructure, consider suppliers with demonstrated retrofit and uprating experience. If the goal is new capacity, focus on vendors with strong project delivery records and the ability to manage civil-mechanical-electrical integration. Matching supplier capabilities to the specific project type reduces execution risk and improves the chance of achieving performance targets.
Keep market intelligence current. Policy, trade patterns, and rehabilitation pipelines are shifting in ways that affect timing, sourcing, and cost. Because these variables can change faster than individual project cycles, access to detailed and updated market information is valuable for procurement planning, bid evaluation, and strategic capacity decisions.
Conclusion
The hydro turbine generator units market is expanding at a steady and strategically meaningful pace, driven by a combination of modernization demand, policy support, grid integration needs, and continued interest in hydropower's dispatchable value. The most important commercial shift is not simply that the market is growing, but that growth is increasingly tied to upgrading existing assets, integrating automation and controls, and competing on lifecycle performance as much as on equipment specification. For manufacturers, suppliers, investors, and asset owners alike, the opportunity lies in aligning capabilities with these realities: strong execution, reliable service, regional responsiveness, and the ability to deliver outcomes that matter over the full life of the asset. In a market where procurement decisions increasingly hinge on long-term performance and integration, detailed market intelligence becomes a practical tool for reducing risk and identifying where value can be captured most effectively.
For detailed analysis of this topic, please visit the official page: Hydro Turbine Generator Units Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com