

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Differential Pressure Sensors Market: Why 5.14% CAGR and Industrial Shifts Redefine Growth 2026–2032

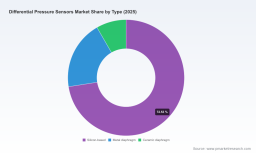
Differential Pressure Sensors Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global differential pressure sensors market has entered a phase of steady, technology-driven expansion. Valued at approximately 158.35 million USD in 2020, the market reached 200.05 million USD by 2025, with a projected compound annual growth rate of 5.14 percent through 2032. This trajectory reflects a mature yet evolving landscape where incremental performance gains, regulatory pressures, and shifting end-use demand converge to reshape competitive dynamics. For executives and investors, the market no longer operates as a commodity trade. It has become a battleground for precision, integration, and ecosystem alignment.
Behind the headline growth figures lies a more nuanced reality. The industry is navigating intense price compression, shifting trade policy exposure, and supply chain reconfiguration. These forces are not merely cost considerations; they are structural inflection points that will determine which players capture value in the next cycle and which remain trapped in margin erosion.
Market Snapshot and Structural Pressures
The revenue base has grown consistently over the past half-decade, but the composition of that growth reveals underlying tensions. Silicon-based sensing architectures dominate the product mix, leveraging economies of scale and compatibility with semiconductor manufacturing ecosystems. Metal and ceramic diaphragm variants maintain relevance in environments demanding corrosion resistance, mechanical robustness, or extreme operating conditions. Across applications, the market is anchored by industrial process control, HVAC systems, and automotive use cases, with medical devices and adjacent segments contributing steady, specialized demand.
Despite this breadth, three structural challenges are reshaping strategic decision-making:
- Sustained pricing pressure. Advances in semiconductor fabrication and broader competition are gradually pulling down average selling prices. Manufacturers that rely on volume without differentiated performance or integration capabilities face margin compression.
- Trade policy exposure. Tariff dynamics on pressure sensor imports have introduced pricing uncertainty and supply chain risk, particularly for manufacturers dependent on cross-border component flows. US-China trade tensions have further complicated import scenarios, forcing regional sourcing reevaluation and inventory strategy adjustments.
- Raw material and input volatility. Silicon wafers, specialty alloys, stainless steel, and engineering plastics form the backbone of sensor production. Procurement timing, supplier concentration, and distributor network quality directly influence cost structure and delivery reliability, especially for MEMS-based devices where material consistency is critical.
These pressures do not signal contraction. They signal a transition from unc differentiated supply to performance-anchored value creation. The companies that navigate this transition successfully will treat cost management, compliance readiness, and material strategy as competitive advantages rather than operational afterthoughts.
Key Demand and Supply Drivers Reshaping the Market
The market’s next phase of growth will be driven by factors that extend well beyond incremental unit volume increases. Four forces stand out as particularly consequential for strategic planning.
Technological Innovation and Sensor Integration
MEMS-based differential and gauge pressure sensors continue to expand their addressable range, with differential configurations reaching typical ranges up to 10 kPa in industrial, automotive, and consumer applications. Simultaneously, digital and board-mount formats are reducing the integration burden for original equipment manufacturers. Compact sensors with flexible interface options and multiple port configurations are becoming viable for embedded HVAC, medical instrumentation, and smart building controls. This trajectory lowers system-level engineering costs and opens opportunities for sensor fusion with airflow, temperature, and IAQ monitoring functions.
The commercial implication is clear. Differentiation is shifting from the sensor element alone to the surrounding value proposition: calibration stability, digital output readiness, integration ease, and application-specific tuning. Manufacturers that invest in interface flexibility, compact packaging, and robustness for embedded use cases are positioning themselves for volume growth in environments where space, reliability, and ease of deployment matter more than ever.
Regulatory and Standards Pressure in Building, Industrial, and Medical Sectors
Regulatory expectations around indoor air quality, energy efficiency, and process safety are tightening across multiple regions. In building automation, digital air differential pressure sensors are being deployed to enable smarter IAQ monitoring, fan energy reduction, and predictive maintenance workflows. In industrial process control, accuracy and repeatability requirements continue to push specification boundaries, particularly where differential readings influence control loops, leak detection, and filter monitoring. Medical applications add another layer of scrutiny, where sensor performance must align with clinical reliability expectations and device-level certification pathways.
For market participants, the regulatory environment is a double-edged sword. It raises compliance and validation costs, but it also creates stickier demand and longer product lifecycle relevance. Suppliers that can demonstrate consistent performance, documentation readiness, and application-specific validation are more likely to secure design-in positions in regulated end markets.
Pressure Sensors Market
Demand-Side Behavior and Application Diversification
End-use buyers are increasingly prioritizing system-level outcomes over isolated sensor specifications. In HVAC and building automation, the focus is on airflow management, energy optimization, and maintenance forecasting. In automotive and industrial settings, demand is shaped by electrification, tighter emissions expectations, and the need for robust measurement under variable operating conditions. Medical device manufacturers continue to seek low-differential and high-accuracy solutions for respiratory, filtration, and diagnostic applications.
This behavior change is reshaping procurement and design-in criteria. Buyers evaluate total cost of ownership, integration complexity, firmware or software compatibility, and supplier support for application engineering. The market is rewarding participants that can map sensor capabilities to end-use workflows rather than simply compete on discrete performance numbers.
Supply Chain Reconfiguration and Cost Structure Evolution
The input ecosystem for differential pressure sensors is adapting to new realities. Silicon and semiconductor material distributors are strengthening supply chain arrangements to support MEMS-based sensor production. At the same time, raw material procurement across silicon, stainless steel, specialty alloys, and plastics remains a sensitivity point that influences the value chain for pressure transducer production. Combined with tariff exposure and regional sourcing considerations, cost structures are becoming more variable and less predictable.
Strategically, this favors organizations that diversify supplier coverage, secure critical input capacity, and design for manufacturability with material availability in mind. It also favorsParticipants that can tolerate short-term cost fluctuations by offering higher reliability, accuracy, or integration value that reduces downstream rework and system failures.
Competitive Positioning and the Evolution of the Vendor Landscape
The competitive field is broad and heterogeneous, spanning semiconductor-oriented manufacturers, instrumentation specialists, industrial automation providers, and application-focused innovators. Market concentration remains moderate, indicating room for differentiation but also reflecting the fragmented nature of end-use requirements. Several companies illustrate distinct strategic postures within the market.
NXP Semiconductors focuses on MEMS-based differential and gauge pressure sensors with differential ranges up to 10 kPa, targeting industrial, automotive, and consumer applications. This positioning emphasizes semiconductor manufacturing leverage, integration potential, and broad application coverage. Honeywell International Inc. emphasizes differential pressure transducers and switches for building automation and HVAC, aligning with demand for reliable control and airflow monitoring in built environments. TE Connectivity offers piezoresistive and MEMS pressure sensors and transducers with wide pressure ranges, supporting applications that require flexibility across operating conditions and robust transducer architectures.
Robert Bosch GmbH and Denso Corporation both maintain strong footprints in automotive and industrial pressure sensing, including differential variants. Their relevance lies in the ability to align sensor performance with vehicle platforms, industrial equipment, and volume production requirements. ABB Ltd and IFM electronic GmbH concentrate on industrial process automation and control-oriented sensing, where reliability, transmitter integration, and process compatibility are paramount. Sensata Technologies spans automotive, industrial, and medical applications, positioning around breadth and application-specific pressure sensor portfolios.
In more specialized niches, Setra Systems uses capacitive sensing for industrial differential pressure transducers in HVAC and cleanroom environments, where stability and low-pressure accuracy matter. Omega Engineering addresses industrial and OEM applications with pressure sensors and transducers, while WIKA Alexander Wiegand SE & Co. KG and Keller AG für Druckmesstechnik focus on measurement technology for harsh environments and industrial differential use cases. Ashcroft Inc. complements this industrial emphasis with pressure gauges and transducers for demanding service conditions.
PW Consulting
The digital and embedded segments are gaining visible momentum. Sensirion AG offers digital differential pressure sensors for high-volume applications, supporting integration into automated and connected systems. Würth Elektronik introduced the WSEN-PDMS series, a compact, highly accurate differential pressure sensor for embedded HVAC and medical applications, with multiple port configurations and flexible interfaces. Belimo Automation AG launched a new Air Differential Pressure Sensor within its New Digital Generation line at the AHR Expo, enabling smart IAQ monitoring, fan energy reduction, and predictive maintenance through the Belimo Assistant 2 App. All Sensors Corporation targets ultra-low differential pressure sensors for medical and industrial use, while Superior Sensor Technology focuses on high-accuracy differential pressure sensors for semiconductor and industrial applications.
Industrial Differential Pressure Transducers Market
This landscape reveals several strategic patterns. First, competition is increasingly bifurcated between semiconductor-enabled integrators and application-focused instrumentation specialists. Second, digital connectivity, app-based monitoring, and predictive maintenance features are becoming differentiators in building and IAQ-related applications. Third, the market remains open enough for niche players to compete on ultra-low pressure ranges, harsh-environment robustness, board-mount compactness, or application-specific validation. Consolidation is possible where vertical integration, portfolio breadth, or regional reach creates scale advantages, but fragmentation persists where end-use specialization and customization remain decisive.
Forward-Looking Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the market over the next three to five years.
Trend 1: Embedded Digital Sensing Becomes the Default for Smart Building and IAQ Applications
Digital differential pressure sensors with connectivity, software integration, and monitoring app compatibility are poised to gain share in HVAC and building automation, particularly where airflow optimization and predictive maintenance are priorities. This trend creates commercial opportunities for suppliers that can deliver not only sensing accuracy but also firmware readiness, communication compatibility, and support for integration into broader building management ecosystems. The risk, however, lies in execution complexity: software support, interoperability expectations, and cybersecurity considerations can become adoption barriers if not addressed early.
Trend 2: MEMS and Board-Mount Form Factors Expand in Medical and Embedded Industrial Use
Compact, accurate differential sensors are increasingly suitable for embedded medical instrumentation and industrial equipment where space, reliability, and interface flexibility matter. The emergence of multiple port configurations and flexible interface options is lowering integration friction and expanding design-in potential. This opens opportunities for volume growth in niches that previously required more customized or bulky solutions. The uncertainty is regulatory and application-specific: medical and certain industrial segments demand validation rigor, and certification pathways can slow adoption even when technical performance is attractive.
Trend 3: Cost, Sourcing, and Tariff Dynamics Will Continue to Influence Competitive Advantage
With average selling prices gradually declining and trade policy exposure persisting, the market will reward companies that manage input costs, diversify sourcing, and protect margin through value-added integration rather than pure volume competition. The commercial opportunity lies in designing for supply resilience, reducing dependency on single-region procurement, and aligning product architecture with material availability. The risk is that margin compression becomes structural for undifferentiated offerings, especially where tariff exposure and input volatility converge.
Strategic Implications for Decision-Makers
Different stakeholders face distinct priorities, but all should treat the market as a value-creation contest rather than a volume race.
For Manufacturers and Sensor Suppliers
- Prioritize integration-friendly architectures. Compact board-mount formats, flexible interfaces, and multiple port configurations reduce downstream engineering cost and expand addressable use cases in HVAC, medical, and embedded industrial applications.
- Invest in application-level validation and documentation. Regulated segments reward suppliers that can demonstrate consistent accuracy, robust calibration behavior, and readiness for certification pathways.
- Protect margin through differentiation, not discounting. Accuracy, stability, harsh-environment capability, digital integration, and application support are more sustainable defenses against price compression than volume-only strategies.
For Investors and Corporate Development Teams
- Assess portfolio fit across semiconductor-enabled and application-focused segments. The market rewards different capabilities in different niches, so acquisition or partnership strategy should align with end-use exposure rather than pursue blanket vertical integration.
- Monitor trade policy and input volatility as valuation-sensitive variables. Tariff exposure, sourcing concentration, and material availability can alter cost structures quickly, especially for MEMS-based product lines and cross-border import scenarios.
- Look for companies that combine sensing competence with software or ecosystem readiness. Digital monitoring, predictive maintenance, and app-based workflows are emerging as commercial differentiators in building automation and IAQ-adjacent segments.
For Procurement and End-Use Buyers
- Evaluate total cost of ownership beyond unit price. Integration complexity, calibration stability, lifecycle support, and compatibility with monitoring or control systems often matter more than the lowest initial sensor cost.
- Plan for supply resilience. Diversify supplier coverage where feasible and verify input and production continuity for critical applications, especially in medical, industrial process control, and building automation contexts.
- Align procurement criteria with long-term application goals. If predictive maintenance, IAQ optimization, or energy efficiency are strategic objectives, prioritize sensors and ecosystems that support those outcomes rather than treating sensing as a standalone component decision.
Conclusion and Research Access
The differential pressure sensors market is expanding with disciplined momentum, but its next chapter will be defined by integration, precision, and supply resilience rather than simple volume growth. Digital connectivity in building and IAQ applications, compact MEMS and board-mount formats in medical and embedded industrial use, and ongoing cost and sourcing pressures are reshaping where value accrues. Participants that align product strategy with end-use workflows, protect margin through differentiation, and prepare for trade and material volatility will be best positioned to capture durable share.
For decision-makers seeking deeper segmentation data, regional demand patterns, pricing trajectory detail, and company-level competitive benchmarking across the full forecast horizon, the complete PW Consulting research report offers extended analytics and customized guidance for strategic planning.
For detailed analysis of this topic, please visit the official page: Differential Pressure Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com