

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Carrageenan Market 2026: Why 5.6% CAGR and Kappa Demand Shift Everything

Navigating the Carrageenan Market: Strategic Trends and Commercial Opportunities Through 2032
The global carrageenan market has transitioned from a mature commodity space into a strategically nuanced arena where functionality, sustainability, and regulatory compliance now define competitive advantage. In 2025, the market reached an estimated revenue of USD 1,000.0 million, building on a steady expansion trajectory from 2020 through 2025. Forward projections through 2032 indicate a compound annual growth rate of 5.6 percent, with revenue anticipated to surpass USD 1,433.0 million by the end of the forecast window. This growth is not merely incremental; it reflects structural shifts in how formulators, manufacturers, and end consumers value hydrocolloid functionality across food, beverage, pharmaceutical, and personal-care applications. The market’s evolution offers a clear lens into broader industry dynamics: ingredient portfolios are being re-engineered for clean-label expectations, supply chains are being re-evaluated for resilience, and regulatory frameworks are increasingly shaping technical feasibility.
For decision-makers across the value chain, the carrageenan landscape presents both familiar headwinds and unfamiliar inflection points. Understanding where growth concentrates, which pressures are structural rather than cyclical, and how leading players are positioning themselves provides a practical foundation for strategic planning. The following analysis examines the current market environment, the forces driving change, the competitive architecture, emerging trajectories, and actionable considerations for manufacturers, investors, and procurement leaders.
Market Landscape and Core Challenges
The carrageenan market’s size and growth profile reflect sustained demand across multiple application verticals, but the macro figures only tell part of the story. Revenue expansion from 2020 to 2025 was supported by consistent reformulation activity, rising adoption in plant-based and dairy-adjacent products, and expanding use in pharmaceutical and personal-care formulations. The forward projection through 2032 suggests continued upward momentum, yet the pace and composition of growth will be shaped by factors that extend well beyond baseline demand.
Several structural challenges are currently redefining how participants approach sourcing, formulation, and compliance. First, raw material availability remains a critical vulnerability. Red seaweed, the foundational input for carrageenan extraction, is exposed to biological and environmental pressures that can disrupt supply continuity. Disease outbreaks affecting seaweed cultivation have periodically constrained harvest volumes, and when coupled with broader energy cost volatility, the result is a supply environment where pricing power and inventory resilience vary significantly across suppliers and regions. This dynamic is not a temporary disruption; it reflects an ongoing tension between agricultural dependence and industrial scale.
Carbomer Market
Second, regulatory scrutiny is intensifying in ways that directly affect formulation feasibility and compliance economics. Emerging draft limits on carrageenan use in infant food within the European Commission have introduced new technical barriers and elevated compliance costs for processors. Parallel regulatory tightening in other markets, including stricter testing and certification requirements for food-additive suppliers, adds layers of administrative and operational complexity. These developments disproportionately affect companies without vertically integrated, GMP-certified facilities, effectively raising the barrier to entry for certain distribution channels and customer segments.
Third, the market’s structural concentration introduces both stability and strategic risk. With a significant share of revenue captured by a relatively small group of established players, competitive dynamics are shaped by scale advantages, formulation expertise, and long-term customer relationships. At the same time, this concentration can limit agility in responding to regional supply shocks or rapidly evolving application requirements. Participants must therefore balance the benefits of portfolio breadth and manufacturing scale with the need for localized sourcing flexibility and technical responsiveness.
The practical implication for executives is that carrageenan is no longer a straightforward input-purchase decision. It is increasingly a strategic variable tied to product performance, regulatory risk, and supply assurance. Businesses that treat it purely as a cost line item risk exposure to formulation constraints and supply interruptions, while those that integrate it into broader ingredient strategy, supplier qualification, and reformulation roadmaps are better positioned to capture value.
Key Drivers Shaping Market Dynamics
Several interconnected forces are propelling the carrageenan market forward, each influencing how value is created and where competitive gaps emerge.
Innovation in Application-Specific Formulations
Technical advancement remains one of the most visible drivers of market evolution. Rather than competing solely on bulk functionality, suppliers are developing specialized carrageenan-based solutions tailored to precise application needs. Recent product introductions highlight a clear directional shift: stabilizers and gelling systems are being engineered for clean-label positioning, alternative-protein textures, and demanding processing conditions. Notably, new carrageenan-based stabilizers designed for all-purpose cream applications and gelling solutions formulated specifically for plant-based abalone meat alternatives demonstrate how ingredient development is aligning with emerging consumer categories. These launches also indicate a broader industry pattern in which hydrocolloid providers are expanding their portfolios at trade events and through targeted commercialization, using direct customer engagement to validate functionality and accelerate adoption.
For formulators and product developers, this trend means carrageenan is increasingly viewed as a customizable functional ingredient rather than a standardized additive. The strategic opportunity lies in matching application-specific performance requirements with suppliers that can demonstrate reproducible results, technical support, and formulation compatibility across diverse processing environments.
Regulatory and Compliance Evolution
Regulatory dynamics are reshaping both market access and competitive positioning. Draft limits on carrageenan in infant food have heightened attention to safety standards, labeling expectations, and processing controls. In parallel, stricter certification requirements in major consumer markets have raised the operational bar for suppliers seeking to serve food-additive and personal-care segments. These developments are not uniformly negative; they create differentiation opportunities for companies that already operate under robust quality systems and can demonstrate traceability, consistent purity, and compliance readiness.
PW Consulting
For procurement and regulatory teams, the implication is clear: supplier qualification now extends beyond price and basic specification matching. It increasingly includes documentation of manufacturing standards, audit readiness, and the ability to navigate evolving regional requirements. Compliance capability is becoming a commercial asset, not just a cost center.
Demand-Side Shifts in Food and Personal-Care Formulations
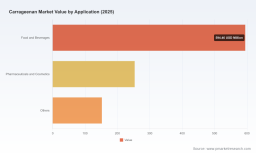
Consumer and industrial demand continues to redirect carrageenan usage toward cleaner-label, plant-forward, and functionally optimized products. In food and beverages, reformulation efforts are driving interest in stabilizers and texturants that support mouthfeel, suspension, and gelation without relying on ingredient profiles that trigger consumer skepticism. Simultaneously, pharmaceutical and personal-care applications are expanding the utility of carrageenan in areas such as wound-care, sustained-release formulations, and premium cosmetic textures. These demand shifts are not isolated trends; they reflect a broader preference for ingredients that combine performance with transparency and naturalness.
From a commercial standpoint, this environment rewards suppliers and formulators who can articulate functional benefits in application-specific language and support customers through development cycles. The growth potential is strongest where carrageenan can solve a tangible formulation challenge while aligning with brand-level positioning.
Supply Chain Structure and Sourcing Geography
The geography of raw material supply remains a defining feature of market behavior. Southeast Asia accounts for the majority of global carrageenan raw-material supply, with Chile serving as a key alternative source. This concentration provides efficiency advantages but also exposes the market to trade, logistics, and biological risk. Any disruption in key cultivation regions can ripple through pricing, availability, and lead times, especially for buyers who rely on just-in-time sourcing or single-supplier arrangements.
Sustainability-oriented sourcing programs are beginning to influence supplier selection as well. Initiatives that align red seaweed procurement with recognized natural-ingredient standards are increasingly referenced as differentiators, particularly in customer segments where environmental claims and responsible sourcing carry commercial weight. The strategic takeaway is that supply resilience is now a function of diversification, certification, and relationship depth, not simply contract negotiation.
Competitive Landscape and Leading Strategies
The carrageenan market features a diverse set of participants spanning global hydrocolloid specialists, ingredient conglomerates, regional manufacturers, and application-focused suppliers. Their strategies reveal how companies are navigating scale, specialization, and compliance in a market that rewards both breadth and precision.
Global Scale and Portfolio Breadth
Several established manufacturers compete primarily through integrated capabilities, multi-type portfolios, and global sourcing infrastructure. Companies with production facilities across multiple regions and certification frameworks are well positioned to serve food, beverage, and personal-care customers with consistent supply and formulation support. Their advantage often lies in the ability to offer Kappa, Iota, and Lambda types within a single supplier relationship, reducing complexity for buyers while maintaining technical continuity across applications.
In this tier, differentiation is less about product novelty and more about reliability, scale, and the depth of technical service. Leadership in this space typically depends on maintaining ISO-aligned manufacturing environments, sustaining supplier and customer relationships across geographies, and reinforcing sustainability commitments that resonate with procurement criteria.
Gellan Gum Market
Specialization and Application Focus
Other participants pursue advantage through narrower focus and application-specific expertise. Specialty hydrocolloid manufacturers and regional producers often emphasize particular customer segments, such as clean-label food systems, pharmaceutical-grade materials, or industrial stabilizers. By concentrating on targeted use cases, these companies can develop deep formulation knowledge, respond quickly to niche requirements, and build strong references within specific industries.
Partnerships also play a meaningful role in this segment. Some suppliers collaborate with seaweed producers or extraction specialists to secure sourcing advantages and strengthen quality control, while others leverage commercial references and application data to reinforce credibility. This strategy can be particularly effective where customers value tailored solutions and closer technical engagement over broad portfolio breadth.
Regional Manufacturing and Sourcing Positionality
Manufacturers based in key seaweed-producing regions benefit from proximity to raw material supply and, in some cases, multi-plant production networks that support export-oriented volume and grade flexibility. For refined and semi-refined grades, this regional positioning can translate into competitive lead times and sourcing adaptability. At the same time, these players must manage the same supply-side risks affecting the broader market, including biological constraints on seaweed cultivation and logistical exposure to trade and freight dynamics.
The global landscape is therefore not a single hierarchy but a set of overlapping competitive models. Some players win on scale and integration, others on specialization and responsiveness, and still others on regional sourcing advantage. The market’s evolution is likely to continue rewarding companies that can combine at least two of these strengths while maintaining compliance and quality assurance as foundational capabilities.
Forward Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how the carrageenan market develops and where commercial opportunities emerge.
Tighter Integration Between Sourcing, Compliance, and Formulation
One of the most durable trends will be the growing interdependence of raw material sourcing, regulatory compliance, and product formulation. As certification expectations rise and application requirements become more specific, suppliers and buyers alike will need to treat these elements as a connected system rather than separate workstreams. Companies with GMP-aligned facilities, traceable sourcing, and application-level technical support will be better equipped to navigate compliance barriers and serve demanding customer segments. For commercial teams, this creates opportunities to differentiate on reliability and service depth, particularly in markets where regulatory complexity is increasing.
Expansion of Application-Specific and Alternative-Protein Solutions
Demand for tailored stabilizer and texturant solutions is likely to remain a growth vector, especially in plant-based, dairy-adjacent, and premium personal-care applications. Product development activity centered on gelling systems, all-purpose stabilizers, and alternative-protein texture optimization points to a market that is moving toward functionality-defined selling. The commercial opportunity lies in pairing ingredient performance with development support, enabling customers to reduce time-to-market and improve formulation consistency. Suppliers that can demonstrate repeatable results across varied processing conditions will capture disproportionate value in this context.
Supply Resilience as a Strategic Differentiator
Given the market’s exposure to seaweed supply constraints and energy cost volatility, supply resilience will increasingly influence purchasing decisions. Buyers are likely to place greater weight on supplier diversification, inventory management, and long-term sourcing commitments. For producers, the ability to demonstrate stable availability, transparent sourcing practices, and responsive logistics can become a competitive advantage even when price remains an important consideration. This trend also raises the strategic importance of balancing regional sourcing dependence with alternative supply pathways and risk-mitigation planning.
At the same time, uncertainty remains. Regulatory directions may shift, raw material conditions may fluctuate, and customer preferences may accelerate or decelerate depending on broader economic and consumer trends. Businesses should therefore treat these forward trajectories as directional signals rather than fixed forecasts, and build flexibility into sourcing, formulation, and partnership strategies.
Actionable Considerations for Decision-Makers
Different roles within the value chain will derive different priorities from the current market environment, but several practical steps stand out across manufacturing, investment, and procurement perspectives.
For Manufacturers and Ingredient Suppliers
- Invest in application-specific technical capability and customer-facing formulation support, as differentiation increasingly depends on demonstrable performance in target use cases rather than generic product availability.
- Strengthen compliance readiness and quality-system visibility, especially where regulatory requirements are becoming more stringent, since certification and audit preparedness can function as commercial entry criteria.
- Diversify sourcing pathways and reinforce supply continuity planning to reduce exposure to regional raw material constraints and energy cost volatility.
For Investors and Strategic Buyers
- Evaluate participants not only on volume and revenue scale but also on compliance infrastructure, application expertise, and sourcing resilience, since these factors are increasingly tied to long-term competitiveness.
- Monitor where product innovation is converging with emerging demand categories, such as plant-based alternatives and premium personal-care formulations, to identify segments with stronger structural growth potential.
- Assess exposure to regulatory shifts and regional supply concentration, recognizing that market leadership may increasingly favor companies with integrated quality and sustainability capabilities.
For Procurement and Formulation Teams
- Expand supplier qualification criteria beyond price and basic specification matching to include manufacturing standards, traceability, and the ability to support application-specific development.
- Build sourcing flexibility through multi-supplier strategies or diversified regional exposure to reduce vulnerability to localized supply disruptions.
- Align ingredient selection with reformulation roadmaps early, so that functionality, labeling, and compliance considerations are addressed before scale-up rather than as afterthoughts.
The carrageenan market is evolving in ways that reward preparedness, technical depth, and strategic sourcing. For organizations that need granular segmentation data, regional demand detail, competitor benchmarking, and customized scenario planning, a more detailed research reference can provide the additional resolution required to translate these strategic signals into operational decisions. Exploring the fuller dataset and tailored analysis can help clarify where to prioritize investment, which supplier relationships deserve closer scrutiny, and how formulation roadmaps should adapt to the next phase of market development.
For detailed analysis of this topic, please visit the official page: Carrageenan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com