

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Audit Software Market 2026: Beyond the 11.32% CAGR Story

Audit Software Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The audit software market has entered a phase of accelerated expansion, driven by the convergence of digitization, heightened regulatory scrutiny, and the modernization of internal control frameworks. From 2020 through 2025, the market demonstrated resilient growth despite periodic macroeconomic headwinds and shifting enterprise investment priorities. The segment progressed from a mid-eight-figure revenue base to surpass the 1.1 billion threshold by 2025, reflecting a structural transition rather than a temporary uptick. Looking ahead to the 2026-2032 forecast horizon, the trajectory points toward a sustained compound annual growth rate near the low double digits, with projected revenues reaching into the mid-2.4 billion range by 2032. This expansion is not merely a function of more licenses being sold; it reflects a deepening embedding of audit management capabilities into core enterprise risk, compliance, and financial reporting operations.
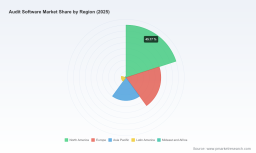
The market's near-term momentum is underpinned by several structural characteristics. Cloud-based delivery models have achieved a majority share of revenue, signaling that the long-running debate between on-premise control and cloud agility has largely tilted toward scalability, remote accessibility, and integration readiness. Application demand is heavily anchored in financial services, insurance, and banking segments, where the cost of noncompliance and the complexity of audit evidence continue to escalate. Geographically, mature markets continue to dominate revenue concentration, but the growth narrative increasingly depends on emerging adoption in Asia Pacific and other regions where regulatory frameworks are formalizing and where organizations are leapfrogging legacy manual processes. Market concentration metrics indicate that no single vendor commands a dominant monopoly, suggesting ample room for differentiated strategies, vertical specialization, and category creation.
Despite this favorable backdrop, the industry faces several inflection points that will determine which players scale profitably and which encounter friction. First, the dimensionality of audit work itself is expanding faster than historical headcount models can absorb. Regulatory expectations around continuous monitoring, data lineage, external reporting transparency, and third-party risk are compressing audit cycles while raising evidentiary standards. Organizations that rely on fragmented spreadsheets, email-driven coordination, and disconnected control repositories are encountering diminishing returns as audit scopes widen. Second, the talent equation is shifting. Audit functions are contending with specialized labor constraints and rising cost structures, even as organizations demand faster turnaround, broader coverage, and more granular risk insight. Automation and analytics are becoming operational necessities rather than optional enhancements, but integrating these capabilities without disrupting workflows or compromising control integrity remains a complex transition. Third, data governance and platform trust have moved from technical footnotes to commercial imperatives. Audit software must support rigorous compliance postures, including SOC 2 Type II and ISO 27001 orientations, while enabling secure collaboration across internal teams, external auditors, and regulated business units. Platforms that cannot demonstrate these standards in product design, deployment, and operational practice face meaningful friction in enterprise sales cycles.
For decision-makers, the strategic implication is clear: audit software is no longer a point tool for documenting workpapers or scheduling fieldwork. It has become a connective tissue linking controls, evidence, risk assessment, and reporting. The organizations that win in this environment will be those that treat audit systems as an integral part of the control architecture, not an afterthought attached to the close process.
Audit Management Software Systems Market
Key Drivers Shaping the Market
Technology Innovation and the AI Turn in Audit Workflows
The most consequential driver reshaping the market is the infusion of artificial intelligence into audit planning, evidence analysis, and issue management. AI-powered platforms are beginning to reduce manual testing time for internal audit teams, with sector analysis indicating reductions of up to half in certain manual testing contexts. This shift is not simply about speed; it changes what audit functions can realistically cover. When routine evidence collection and repetitive testing steps are automated, teams can redirect attention to judgmental areas, anomaly investigation, and control design effectiveness. Automated audit analytics have also lowered specialized labor requirements for evidence collection and issue tracking, helping organizations maintain coverage without proportionally increasing headcount. These capabilities are particularly valuable in environments where financial reporting standards are evolving and where AI-assisted tools are increasingly used to meet new expectations in audit processes. In practice, this means audit software vendors are competing not only on workflow convenience but on how intelligently their platforms surface risk, prioritize testing, and accelerate reconciliation between control findings and remediation actions.
Another dimension of technological disruption is the convergence of audit, risk, and compliance into unified platforms. Historically, internal audit management, IT risk assessment, ethics and compliance case management, and operational audit tracking often lived in separate systems. The emergence of AI-powered GRC platforms optimized for audit, risk, and compliance workflows reflects a market preference for consolidation. Unified platforms reduce data silos, improve traceability across workstreams, and enable cross-functional analytics that would be cumbersome in fragmented environments. For vendors, this consolidation dynamic raises the stakes on integration depth, data model flexibility, and user experience. For buyers, it creates an opportunity to rationalize tool sprawl while improving the quality of assurance evidence.
PW Consulting
Regulatory and Policy Environment as a Persistent Demand Engine
Regulatory complexity continues to act as a durable catalyst for audit software investment. Financial services, insurance providers, and manufacturing organizations operate under an expanding set of expectations around controls testing, evidence retention, transparency, and continuity of oversight. Platforms must maintain rigorous compliance postures to support audit workflows in regulated industries, and market participants increasingly evaluate software through the lens of auditability, access control, and certification readiness. This is especially relevant for cloud deployments, where data residency, segregation, and third-party assurance are scrutinized more closely. At the same time, policy signals around financial reporting standards are prompting audit teams to adapt their methods and documentation. AI-assisted tooling is enabling teams to keep pace by standardizing analysis, improving repeatability, and streamlining review cycles. The implication is that regulatory pressure is no longer just a compliance cost; it is a catalyst for modernization that favors platforms capable of adapting to new standards without requiring wholesale process redesign.
Demand-Side Shifts in Enterprise Behavior
On the demand side, two behavioral shifts are particularly important. First, the internal audit function is increasingly expected to provide forward-looking assurance and cross-functional insight, not just historical verification. This shift pushes organizations toward platforms that support continuous monitoring, risk-based planning, and issue tracking that connects findings to remediation and governance oversight. Second, collaboration expectations are changing. Audit work increasingly spans internal teams, external auditors, and business process owners. Software that streamlines audit collaboration and improves efficiency gets traction because it reduces handoff friction, shortens review cycles, and improves version control across shared workpapers and assessments. These behaviors are especially pronounced in cloud adoption, where multi-user access, real-time updates, and integration with enterprise data sources become part of the value proposition. As organizations modernize audit operations, they are selecting tools that enable faster planning, more transparent fieldwork, and clearer reporting to audit committees and executive stakeholders.
Cost Structures, Automation, and the Reallocation of Audit Resources
The supply-side cost conversation is evolving as automation reshapes the economics of audit delivery. Manual testing time reductions and lower specialized labor requirements for evidence collection and issue tracking are altering how audit budgets are allocated. Rather than scaling linearly with audit scope, organizations can use automation to expand coverage and maintain quality while moderating the growth in labor intensity. This change benefits both buyers and vendors: buyers can pursue broader assurance programs without proportional cost escalation, and vendors can differentiate through analytics, workflow automation, and intelligent prioritization. However, the transition also raises the importance of change management. Tools that automate portions of the audit process must be introduced in ways that preserve control rigor, align with audit methodology, and support reviewer confidence. The vendors that succeed will be those that package automation within workflows that auditors trust, rather than offering point features disconnected from day-to-day practice.
Competitive Landscape and Leading Strategies
The competitive field in audit software is diverse, spanning established GRC franchises, internal audit specialists, quality and EHS-oriented platforms, and AI-forward analytics vendors. Several companies illustrate the dominant positioning strategies shaping the market.
- One notable trajectory is the move toward AI-powered GRC platforms optimized for audit, risk, and compliance workflows. A recent rebrand of AuditBoard to Optro reflects this direction, introducing a platform designed to centralize audit management, risk assessment, and compliance tools in a more integrated, intelligence-driven experience. The rebrand signals a strategic emphasis on cross-functional assurance, not siloed audit management alone.
- Traditional internal audit management providers continue to play an important role by focusing on the mechanics of planning, fieldwork, and reporting. Platforms such as TeamMate+ remain relevant for teams that value structured audit lifecycle support and mature methodology alignment. The enduring appeal of these solutions lies in their grounding in audit practice and their ability to support standardized workpaper and reporting habits.
- Cloud-native internal audit platforms emphasize controls testing, issue tracking, and a connected cloud experience. These solutions appeal to organizations seeking to modernize audit operations with real-time visibility and streamlined collaboration, particularly where distributed teams and frequent reporting cycles demand accessible, always-on environments.
- Resolver-style platforms bring automated workflows and risk intelligence to internal audit management, highlighting the value of guided workflows, structured issue management, and centralized risk context. This approach is attractive where audit organizations want greater consistency across engagements and stronger linkage between findings and remediation.
- Benchmark Gensuite illustrates the occupational and EHS audit segment, with capabilities for scheduling, staffing, and managing audits alongside repository tools. The emphasis on AI-native EHS audit management in recent positioning underscores how operational audit domains are being reimagined with intelligent workflows and specialized data models.
- Quality management-oriented providers such as Isolocity address audit planning, execution, and compliance certification within QMS and EQMS contexts. Here the audit software value proposition is tightly connected to certification readiness and process quality, not just financial or internal control assurance.
- Caseware showcases the convergence of audit and accounting workflows, with AI-powered platforms supporting engagement workflow and financial reporting. The appeal lies in connecting audit execution with the broader accounting and reporting lifecycle, especially for firms and organizations managing multiple engagements.
- GRC platforms with internal audit modules, such as Onspring, aim to combine automated workflows, analytics, and project management in a single environment. For organizations that want audit functionality embedded in a broader controls and governance framework, this modular approach offers flexibility.
- Oversight Systems represents the analytics-driven angle, using AI-powered financial analytics for risk detection, compliance, and automated audits. This positioning emphasizes anomaly detection and continuous insight, appealing to organizations that want proactive monitoring layered into their audit processes.
The strategic differentiation among these players falls into several recognizable patterns. Some vendors compete on depth of audit methodology and structured lifecycle support, which resonates with audit functions that prioritize rigor, repeatability, and explicit alignment to traditional audit practice. Others compete on platform breadth, embedding audit within GRC, quality, or accounting ecosystems to reduce fragmentation and provide a unified risk and control picture. A third group emphasizes intelligence and automation, seeking to compress manual effort, improve issue prioritization, and enable continuous monitoring through analytics. Each strategy has merit, and the most attractive positioning depends on the buyer's operating model, regulatory exposure, and appetite for workflow consolidation versus modular best-of-breed selection.
Market evolution is playing out through both consolidation and fragmentation dynamics. On one hand, buyers increasingly prefer platforms that reduce tool sprawl and connect audit workflows with risk, compliance, and reporting contexts. This encourages vendors to expand their scope and deepen integrations. On the other hand, specialized segments such as EHS audits, quality certification audits, and engagement-focused accounting workflows continue to support niche solutions with domain-specific functionality. New entrants and repositioning players are also reshaping categories, especially where AI and cloud architecture create opportunities to redefine usability, speed, and insight. Recent product launches and leadership updates in the sector illustrate this activity, including cloud audit releases with next-generation collaboration features and renewed executive emphasis on AI-native audit management in operational contexts. Taken together, the competitive landscape is becoming more application-specific, more intelligence-intensive, and more integrated across related assurance and governance functions.
Future Trends and Commercial Opportunities
From Periodic Audit to Continuous, Risk-Based Assurance
Over the next three to five years, audit software is likely to shift further from periodic, engagement-based execution toward continuous, risk-based assurance embedded in normal business operations. This trend is supported by the growing use of analytics, automation, and unified data models that make ongoing monitoring and testing more feasible. For commercial opportunity, this creates demand for platforms that can prioritize testing based on risk signals, maintain current evidence repositories, and connect control performance to governance dashboards. Organizations that can operationalize continuous insight will be better positioned to manage evolving reporting expectations and to respond faster when control weaknesses emerge. The opportunity lies not just in automation, but in making audit insights more timely, contextual, and actionable for decision-makers.
Platform Consolidation with Domain Depth
A second trend is the continued pressure toward platform consolidation, balanced by demand for domain depth in specific verticals and audit types. Buyers want fewer disconnected tools, but they also want audit workflows that fit financial services, manufacturing, quality management, EHS, or engagement-based accounting contexts. The winning commercial model is likely to combine broad connectivity with strong domain functionality, allowing organizations to standardize core audit processes while retaining the specialized features needed for particular assurance programs. Vendors that can deliver this balance may gain traction in mid-market and enterprise segments alike, especially where evidence integrity, collaboration, and certification readiness matter. Conversely, overly generic platforms risk losing ground to solutions that understand the nuances of specific audit domains and regulatory contexts.
AI as an Operating Assumption, Not a Differentiator
A third trend is the normalization of AI as an operating assumption rather than a standalone differentiator. As AI-assisted tools become more common in audit processes, expectations will rise around reliability, explainability, integration, and auditability of the tools themselves. The commercial opportunity will shift toward vendors that can show how intelligence is embedded in trusted workflows, how data is governed, and how outputs support reviewer judgment rather than replacing it. At the same time, this trend introduces uncertainty. AI adoption can create new questions about model governance, evidence quality, and process ownership, especially in regulated industries where audit integrity is paramount. Organizations will need to evaluate not only what a platform can automate, but how it maintains control over the audit process, supports evidence standards, and remains adaptable as expectations change.
Strategic Implications for Decision-Makers
For executives and strategy teams evaluating audit software, the near-term priority is to align tool selection with the desired operating model of the audit function. Organizations that want faster, more integrated assurance should favor platforms that connect planning, fieldwork, issue management, and reporting in a coherent workflow, with cloud accessibility and collaboration features that match how teams actually work. Those operating in regulated or specialized environments should weigh domain functionality more heavily, including support for relevant certification, controls testing, and evidence standards. In all cases, platform trust matters: buyers should assess how software supports SOC 2 Type II and ISO 27001 orientations and whether its design is compatible with the audit rigor required in their industry.
It Audit Services Market
For investors and market participants, the opportunity is to identify vendors that combine scalable platform economics with credible audit methodology and measurable workflow efficiency gains. The growth trajectory suggests expanding demand, but the more interesting question is which capabilities will become table stakes and which will sustain differentiation. Intelligence-led automation, strong integration, and domain relevance are likely to be durable value drivers, especially where vendors can demonstrate reduced manual effort, better coverage, and clearer issue remediation linkage. At the same time, the market's breadth means that category leadership will be uneven across segments, and the most attractive bets will depend on the specific vertical, deployment model, and regulatory exposure being served.
For procurement and audit leaders navigating vendor selection, the practical focus should be on total workflow fit rather than isolated feature checklists. Key evaluation questions include how well the platform supports risk-based planning, how efficiently it handles evidence collection and issue tracking, how smoothly it enables collaboration with external stakeholders, and how convincingly it supports compliance and security expectations. It is also prudent to consider the vendor's trajectory: recent rebrands, product launches, and leadership shifts can signal where companies are placing bets and how they intend to compete. In a market moving toward AI-enabled, cloud-based, and increasingly consolidated platforms, the most valuable intelligence is the kind that connects product direction with enterprise readiness and segment-specific needs.
For decision-makers seeking a fuller picture of segmentation dynamics, regional adoption patterns, competitive positioning details, and forward scenarios, a comprehensive research report can provide the granularity needed to translate these trends into procurement, investment, and operating decisions. Detailed segmentation splits, company-by-company profiles, and scenario-based sizing help translate market-level momentum into actionable strategy, especially when the choice set spans GRC platforms, internal audit specialists, quality and EHS solutions, and analytics-driven vendors.
For detailed analysis of this topic, please visit the official page: Audit Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com