

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Spectrometer Market 2026: Beyond the 7.97% CAGR—Key Drivers Reshaping Growth to $20.38B

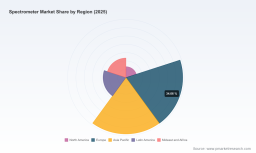
Spectrometer Market: Strategic Trends and Commercial Opportunities Beyond 2030
The global spectrometer market has entered a phase of sustained expansion driven by converging forces in analytical science, regulatory scrutiny, and technological maturation. From a base of approximately $8.05 billion in 2020, the market has grown to an estimated $11.95 billion in 2025, reflecting consistent demand across pharmaceutical research, clinical diagnostics, environmental monitoring, and industrial quality control. Looking ahead to 2032, the sector is projected to reach nearly $20.38 billion, underpinned by a compound annual growth rate of 7.97 percent. This trajectory signals more than incremental adoption; it points to structural shifts in how organizations deploy analytical instrumentation, integrate data workflows, and respond to tightening compliance requirements. For executives and investors, the question is no longer whether spectrometers will remain central to analytical operations, but how to position portfolios, supply chains, and R&D investments to capture the upside while navigating fragmentation and cost pressures.
Mapping the Current Landscape and Core Friction Points
The market expansion documented over the past half-decade masks underlying complexity. Growth has been fueled by higher instrument utilization in drug discovery and development, expanding proteomics and metabolomics programs, and broader adoption of clinical chemistry and toxicology workflows. At the same time, the industry is confronting several inflection points that will shape competitive outcomes over the next several years.
First, concentration dynamics remain moderate, with the top three players holding roughly 30 percent of total revenue and the top five collectively accounting for about 38 percent. This leaves substantial room for specialized vendors, regional specialists, and new entrants that can differentiate on application-specific performance, service models, or total cost of ownership. The presence of meaningful headroom suggests that scale alone will not guarantee dominance; rather, organizations that can align instrument capabilities with end-user workflows and regulatory traceability will capture disproportionate value.
Second, the cost structure of high-resolution systems continues to be shaped by component-level dependencies. Optical gratings and diffraction elements remain the primary raw material and core components for high-resolution spectrometer systems, with pricing influenced by specialized polymer and metal alloy supply chains. Volatility in these inputs can compress margins or delay product rollouts, especially for vendors relying on custom optics and precision-engineered assemblies. Companies that secure multi-source sourcing strategies, standardize modular optical architectures, or invest in alternative fabrication methods will be better positioned to stabilize pricing and maintain delivery reliability.
Nuclear Magnetic Resonance Spectrometer Market
Third, compliance and performance verification requirements are becoming more entrenched. ISO 17025 accreditation standards for spectrometer performance testing require recalibration every 12 to 24 months to maintain traceability in laboratory and industrial use. This creates recurring revenue opportunities through service contracts and calibration programs, but also raises the operational burden for end users who must manage downtime, documentation, and audit readiness. Vendors that embed automated calibration routines, remote diagnostics, and digital traceability into their platforms can reduce friction and strengthen customer retention.
What Is Driving the Next Wave of Growth
Several interlocking drivers explain why the spectrometer market is advancing at a pace that outpaces many adjacent analytical segments.
Technological innovation and platform convergence are central to the momentum. Recent product introductions illustrate how vendors are pushing into higher-throughput, hybrid, and benchtop formats. At analytica 2026, Bruker highlighted a Fourier 80 benchtop FT-NMR spectrometer and a timsMRMS platform aimed at higher-throughput chemistry laboratories, alongside a mobile FT-IR spectrometer that broadens on-site analytical capabilities. In the same period, Thermo Fisher Scientific unveiled the Orbitrap Excedion hybrid mass spectrometer and the Orbitrap Tribrid Apex mass spectrometer, reinforcing the direction toward hybrid architectures that combine resolution, speed, and multi-modal flexibility. SCIEX added to the momentum by unveiling the novus V55 triple quadrupole mass spectrometer at ASMS 2026, an indication of continued investment in triple quadrupole platforms for targeted quantitative workflows. These launches are not isolated events; they reflect a broader push to make advanced spectroscopy and mass spectrometry more accessible, faster, and easier to integrate into routine operations.
Regulatory and accreditation environments are shaping procurement behavior. Stricter expectations for data integrity, method validation, and instrument traceability are prompting laboratories and industrial users to standardize on platforms that support documented calibration cycles and auditable performance records. The requirement for periodic recalibration under ISO 17025 underscores the importance of service ecosystems and software-enabled compliance. Suppliers that can streamline accreditation preparation, reduce manual intervention, and provide clear performance benchmarks will benefit from extended sales cycles that convert into durable multi-year relationships.
Demand-side change is also reshaping the market. Pharmaceutical and biotech organizations are expanding analytical capacity to support drug discovery and development, while proteomics and metabolomics programs continue to drive adoption of high-sensitivity systems. Clinical chemistry and toxicology workflows are growing as point-of-care and centralized testing models mature. At the same time, industrial users in mining, environmental monitoring, and manufacturing are seeking portable or semi-portable formats that can deliver real-time insights without sacrificing reliability. The broadening of use cases is creating opportunities beyond traditional laboratory settings, particularly where portability, automation, and ease of use can reduce dependency on specialized operators.
Supply chain and cost dynamics are influencing both product design and pricing strategies. The reliance on specialized optical components, metal alloys, and polymer-based gratings ties instrument cost to niche supplier networks. In parallel, the integration of AI-enabled auto-calibration software in portable spectrometers is reducing operator dependency and supporting real-time on-site analysis in mining and environmental applications. This software-driven approach to calibration and performance management can partially offset hardware complexity by simplifying installation, routine upkeep, and field deployment. For vendors, the implication is clear: competitive advantage will increasingly come from bundling hardware with intelligent software, service assurance, and application-specific workflows rather than competing on specifications alone.
Competitive Positioning and the Evolution of the Landscape
The current competitive environment is defined by established players that are extending portfolios across complementary modalities while also targeting specific workflow pain points. Each major vendor is pursuing a distinct angle of differentiation.
Bruker Corporation, headquartered in Billerica, Massachusetts, has been emphasizing versatility across chemistry and bioanalysis. Its recent activity centers on benchtop FT-NMR and high-throughput platforms, positioning the company to serve laboratories that need compact footprints without sacrificing analytical depth. The combination of a benchtop FT-NMR system and a timsMRMS platform points to an intent to capture users who want both structural characterization and high-performance mass spectrometry in closely integrated workflows. The addition of mobile FT-IR capabilities further broadens the company's reach into field-deployable applications, aligning with demand for faster, on-site decision-making.
Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, continues to lean into high-end hybrid and tribrid mass spectrometry architectures. The Orbitrap Excedion hybrid and Orbitrap Tribrid Apex systems highlight a strategy built around resolution, multi-dimensional analysis, and the ability to handle complex samples in demanding research and biopharma environments. By advancing hybrid configurations, the company is targeting users who require flexibility across qualitative and quantitative tasks, along with the throughput needed for large-scale programs. The emphasis on premium architectures positions the firm to serve as a cornerstone supplier for organizations that prioritize analytical performance and long-term platform investment.
Agilent Technologies, Inc., located in Santa Clara, California, maintains a strong focus on gas chromatography and mass spectrometry systems for laboratory analysis. Its strategy appears anchored in reliability, broad application coverage, and integration with laboratory information workflows. By strengthening GC and MS system portfolios, Agilent is reinforcing its role in routine and high-throughput analytical operations where consistency, support, and method robustness are paramount. This positioning appeals to customers who value proven performance across diverse sample matrices and want a familiar ecosystem for method development and operational scaling.
SCIEX, operating under Danaher Corporation in Framingham, Massachusetts, has been advancing targeted quantitative capabilities with a focus on triple quadrupole technology. The novus V55 triple quadrupole mass spectrometer launched at ASMS 2026 illustrates continued commitment to platforms that excel in quantification, regulatory-grade workflows, and routine testing environments. The emphasis on triple quadrupole architecture signals a strategic tilt toward customers who need reproducible quantitation and robust performance for compliance-driven applications.
Shimadzu Corporation, headquartered in Kyoto, Japan, continues to offer mass spectrometry and spectroscopy systems for analytical applications across a broad range of industries. Its approach reflects deep application knowledge and a global service footprint, which supports deployment in both research and industrial settings. By maintaining breadth across spectroscopy and mass spectrometry, Shimadzu is positioned to serve organizations that require multi-technique solutions and consistent regional support.
Waters Corporation, based in Milford, Massachusetts, extends its brand around Xevo series mass spectrometers and LC-MS systems. The focus on liquid chromatography-mass spectrometry integration underscores the importance of combining separation and detection in pharmaceutical, biological, and industrial workflows. Waters' positioning emphasizes performance in biological and small-molecule analysis, along with software and service layers that support data interpretation and operational efficiency.
Together, these players reflect a market that is both consolidated at the top and open to differentiation in the long tail. Consolidation pressures are likely to continue through partnerships, selective acquisitions, and ecosystem bundling, especially where vendors can combine instrumentation with software, service, and application expertise. At the same time, the moderate concentration levels suggest that new entrants and niche specialists can succeed by targeting underserved workflows, regional demand, or specific price-performance thresholds. The key differentiator will be the ability to translate instrument performance into measurable operational outcomes, whether through faster turnaround, lower total cost of ownership, simplified compliance, or more seamless integration with existing laboratory infrastructure.
What to Watch Over the Next Three to Five Years
The next phase of development will be shaped by the interplay of technology, regulation, and end-user expectations. Three trends are particularly significant.
Hybridization and modularity will become more central to product roadmaps. As laboratories seek to handle more complex analyses without expanding footprint or operator burden, platforms that combine high resolution with flexible acquisition modes will gain traction. Modular architectures that allow users to scale capabilities as needs evolve can reduce upfront capital risk and support incremental upgrades. The commercial opportunity here lies in offering platforms that can grow with the customer, supported by software and service layers that preserve performance consistency across configurations.
PW Consulting
Software-defined performance and intelligent calibration will become competitive necessities. AI-enabled auto-calibration software in portable spectrometers is already reducing operator dependency and enabling real-time on-site analysis in mining and environmental applications. Extending similar capabilities across broader instrument classes can shorten setup times, improve reproducibility, and reduce the frequency of manual intervention. For vendors, this creates an opening to differentiate through intelligent workflows, predictive maintenance, and remote performance monitoring. For buyers, it can translate into more consistent results and lower training overhead. The risk is that software features become table stakes quickly, so differentiation must be paired with genuine workflow value and reliable execution.
Regulatory traceability and service ecosystems will increasingly influence purchasing decisions. With ISO 17025 expectations anchoring recalibration cycles and performance verification, customers will favor platforms that make compliance manageable and auditable. This dynamic favors vendors with strong service networks, clear documentation, and digital traceability. The upside is recurring revenue and customer lock-in, but the challenge is executing consistently across geographies and instrument types. Companies that can standardize calibration and verification processes while preserving flexibility for local requirements will be better equipped to scale service operations profitably.
These trends create commercial opportunities for organizations that align product strategy with end-user economics. Laboratories and industrial users will reward solutions that reduce downtime, simplify accreditation, and integrate smoothly into existing data environments. Suppliers that can demonstrate measurable improvements in throughput, reproducibility, and total cost of ownership will be in a stronger position to win share, even in a competitive field. At the same time, potential risks include component cost volatility, uneven adoption of automation across regions, and the possibility that rapid software advancement raises expectations faster than hardware can deliver. Monitoring these dynamics closely will be essential for strategic planning.
Actionable Guidance for Decision-Makers
Manufacturers and technology providers should prioritize differentiation through workflow integration rather than specification competition alone. The current landscape shows that leading vendors are expanding into hybrid, benchtop, and portable formats while also emphasizing service, calibration, and software support. Companies that can align product roadmaps with real-world adoption barriers—such as calibration burden, operator dependency, and compliance documentation—will be better placed to capture demand across both premium and mid-tier segments. It is equally important to secure component supply strategies for optical gratings and diffraction elements, given the sensitivity of high-resolution systems to specialized polymer and metal alloy supply chains. Building sourcing resilience and standardizing modular optical designs can help stabilize margins and improve delivery predictability.
Investors should look beyond headline growth and assess where value is likely to accumulate. The market's moderate concentration suggests that both scaled incumbents and focused specialists can create value, but the basis of advantage differs. Premium hybrid and tribrid platforms can support long-term positioning in high-sensitivity research and biopharma applications, while portable and benchtop systems can open faster-growing field and routine analysis segments. Investors should also weigh exposure to recurring revenue from service, calibration, and software, particularly as accreditation requirements and traceability expectations increase. Finally, competitive risk should be evaluated in terms of ecosystem strength: vendors that can combine hardware, software, and service into a coherent value proposition are more likely to sustain pricing power and customer retention.
X-ray Fluorescence Spectrometer Market
Procurement leaders and end-user organizations should focus on total cost of ownership and operational resilience rather than initial purchase price. Instruments that simplify calibration, reduce downtime, and support documented performance verification can lower hidden costs and improve audit readiness. Procurement teams should evaluate vendor support networks, remote diagnostics, and software-enabled workflows as part of the purchasing decision, especially where ISO 17025-related recalibration cycles and traceability requirements are relevant. For organizations deploying instruments in diverse settings, portability, ease of use, and the ability to operate with reduced specialist involvement can be decisive factors. Aligning procurement criteria with long-term operational goals will help avoid underinvestment in service and support, which can erode the value of otherwise capable hardware.
Strategic decision-making in this market depends on access to granular segmentation data, competitor benchmarking, and regional demand patterns that reveal where adoption is accelerating and where pricing pressure is intensifying. Detailed sector breakdowns, application-level demand signals, and vendor-level positioning can sharpen capital allocation, R&D prioritization, and procurement strategy. For organizations seeking a more comprehensive view of the spectrometer market—including detailed segmentation, competitive analytics, and customized scenario planning—PW Consulting's full research report provides the deeper dataset and tailored insights needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com