

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polymer Modified Bitumen Market: Why 4.92% CAGR and Road Construction’s 73.9% Share Signal a New Phase

Polymer Modified Bitumen Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Genesis: Where the Polymer Modified Bitumen Market Stands Today
The polymer modified bitumen (PMB) market has evolved from a specialized performance upgrade into a structural layer of modern infrastructure and building envelope systems. Over the historical window of 2020 through 2025, the market expanded steadily, moving from a base above 105 million USD to a 2025 valuation of approximately 134.5 million USD. This trajectory reflects more than cyclical construction activity. It signals a maturing shift in how roads, roofs, and waterproofing assemblies are specified, validated, and maintained over their service lives. The forward trajectory through 2032 points toward a mid-180 million USD range, with a compound annual growth rate of roughly 4.92 percent. The pace is not explosive, but it is durable, and durability is what matters for capital allocation in materials markets.
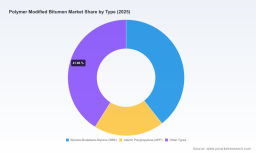
The market is not behaving as a monolith. Growth is uneven across geographies, types, and end uses, and that unevenness is where strategic advantage is created or lost. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each bring distinct demand drivers, regulatory postures, and procurement habits. SBS-based modifiers, APP-based modifiers, and a broader set of specialty formulations carry different performance profiles and cost structures. Road construction, roofing, and waterproofing each impose different service conditions, and those conditions shape which modifier, which membrane architecture, and which application method wins in a given context. The aggregate numbers can be summarized quickly, but the commercial reality lives in the intersections.
Three challenges define the current inflection point for industry participants. First, raw material volatility is moving from an intermittent pressure to a structural factor in cost planning. Polymer feedstocks and resin inputs are no longer passive inputs that can be absorbed through marginal pricing adjustments; they are becoming a strategic variable that influences formulation choices, contract structures, and regional sourcing. Second, performance validation is tightening. Buyers and public agencies are increasingly unwilling to accept generic claims of durability. Sampling protocols, fatigue testing, and lifecycle-oriented evaluation are becoming part of the commercial conversation, not just the technical one. Third, the market is wrestling with a transition from upfront price competition to total cost of ownership thinking. That transition is uneven, but it is real, and it rewards suppliers that can document performance over time rather than compete solely on installed cost.
Worldwide Asphalt Cement Binder Market
Drivers Reshaping the Market: Technology, Policy, Demand, and Supply Economics
Technical Innovation and Material Architecture
One of the most consequential shifts in the PMB space is the move toward hybrid and blended modifier systems. Traditional SBS and APP formulations each have strengths, but neither is universally optimal across thermal cycling, fatigue loading, UV exposure, and installation conditions. Hybrid architectures are gaining attention because they allow formulators to balance flexibility, temperature susceptibility, and long-term fatigue resistance more precisely. This is not a theoretical exercise. It is showing up in product development activity, where newly launched hybrid membranes are being positioned for rooftop and waterproofing systems that must endure wider temperature swings and more frequent thermal shock than earlier generations of membranes were designed for.
Parallel to formulation innovation is a stronger emphasis on durability verification. The reaffirmation and continued active use of standardized sampling and analysis practices for modified bitumen roof systems signals that the industry is anchoring its claims to repeatable test methods. That matters for commercial trust. When manufacturers can point to standardized sampling protocols and cyclic fatigue testing, they are not just proving technical competence; they are reducing the perceived risk for specifiers, contractors, and facility owners. In a market where membrane failure can mean costly repairs and service interruptions, documented performance becomes a differentiator that can support premium positioning and longer-term specification loyalty.
Worldwide Eco-Friendly Bitumen Market
Policy and Regulatory Environment
Policy is no longer a background condition in this market; it is becoming a demand shaper. In India, mandates requiring polymer modified bitumen for high-traffic road tenders, combined with a shift toward life cycle cost evaluation, are changing how projects are won and how materials are selected. When procurement moves from lowest initial bid to lifecycle economics, the calculus changes. A more expensive modified bitumen may be preferred if it reduces maintenance frequency, extends service life, or lowers the probability of early distress under heavy traffic loads. This regulatory direction is significant because it institutionalizes a preference for performance over pure upfront price in a segment that has historically been cost-sensitive.
PW Consulting Automotive & Machinery Research Center
At the same time, standardized specifications and reaffirmed testing practices in other markets are reinforcing a similar effect from a different angle. Specifications do not always force a material choice directly, but they raise the bar for what qualifies. Once standards and sampling protocols are embedded in project requirements, suppliers without robust testing documentation or consistent quality systems find it harder to compete for premium or technically demanding work. Policy and standards, taken together, are quietly narrowing the field for suppliers that rely on claims alone.
Demand-Side Behavior and Application Priorities
Demand is being shaped by two overlapping forces: infrastructure expansion and building performance expectations. Road construction remains the dominant application arena for PMB, and that dominance is sustained by ongoing highway and heavy-traffic network development. But the composition of demand is changing. Projects are increasingly evaluated not just by capacity or speed of delivery, but by resilience, maintenance burden, and expected service life. That changes the buyer’s question from “What can we install now?” to “What will still be performing well a decade from now?”
In roofing and waterproofing, the demand story is more nuanced. Building owners andSpecifiers are pushing for membranes that can better handle thermal cycling, ponding water, and longer exposure without premature aging. This is especially relevant where roof systems are expected to integrate with energy efficiency goals, withstand more extreme weather patterns, or reduce long-term replacement risk. The roofing and waterproofing segments therefore reward products that can combine flexibility with stability, and that can be installed reliably across a range of labor skill levels and site conditions. Where a product can lower installation risk while maintaining performance, it gains a commercial edge beyond raw material properties.
Supply Chain and Cost Structure Dynamics
The supply side of the PMB market is entering a period where cost structure is as strategically important as formulation capability. Polymer inputs are subject to broader chemical market dynamics, and those dynamics can translate quickly into price adjustments for SBS, APP, and related modifiers. When a major polymer supplier announces broad price increases across multiple product lines, the impact is not confined to one region or one end use. It ripples into membrane manufacturing margins, tender pricing, and the relative attractiveness of different modifier choices.
This environment favors companies that have either diversified input strategies, forward-looking procurement arrangements, or formulation flexibility. It also raises the strategic importance of transparency. Buyers are increasingly alert to the possibility that technical superiority can be undermined by unpredictable input costs, while low-cost offerings can be undermined by performance inconsistency. In that context, the most resilient suppliers are those that can articulate not only what their product does, but how their sourcing, manufacturing control, and quality assurance reduce volatility risk for the customer.
Competitive Landscape: Positioning, Differentiation, and the Shape of the Field
The competitive landscape in polymer modified bitumen is characterized by moderate concentration and a mix of integrated membrane manufacturers, polymer suppliers, and regionally specialized producers. The market does not belong to a single dominant bloc. Instead, it is shaped by a handful of companies that compete on different axes: technical documentation, hybrid product architecture, regional distribution strength, application-specific specialization, and polymer supply control. That diversity is important because it means there is no single winning formula. Strategy must match the segment, the geography, and the customer’s decision criteria.
Among membrane manufacturers, several players have built recognizable strengths around SBS-modified systems, APP-modified systems, or hybrid approaches. Companies with strong SBS-based roofing and waterproofing portfolios tend to compete on durability narratives, fatigue performance, and membrane system design. Suppliers emphasizing APP and SBS options for roofing often compete on climate suitability, ease of installation, and product consistency. Hybrid membrane launches indicate a growing willingness to combine modifier types to address broader service conditions rather than optimizing for a single performance attribute. In practical terms, differentiation is moving from “SBS versus APP” toward “which combination of flexibility, stability, and verification best fits the job.”
Polymer suppliers occupy a different but equally important position in the value chain. A polymer producer that supplies SBS and related modifiers influences the market indirectly but powerfully, because its pricing, availability, and product consistency affect downstream membrane economics. When polymer input costs rise, membrane manufacturers must decide whether to absorb cost, pass it through, reformulate, or shift regional purchasing patterns. That makes polymer suppliers strategic nodes in the market, not just upstream vendors. Their actions can reshape margin structures and even redirect demand toward alternative modifier options if the price gap becomes large enough.
Regional specialization also matters. In India, for example, producers focused on polymer modified bitumen for road applications benefit from the intersection of highway expansion demand and regulatory preference for PMB in high-traffic tenders. That regional advantage is not automatically transferable elsewhere, but it shows how a focused product strategy aligned with local procurement rules can create a durable position. Elsewhere, regional players compete by serving local roofing and waterproofing demand with products calibrated to regional climate, labor practices, and specification habits.
Recent developments illustrate how this landscape is evolving in practice. Leadership transitions in established market players can reshape commercial priorities and regional focus. Innovation awards signal that technical differentiation is being recognized, which can strengthen specification momentum. New hybrid product launches suggest that the competitive frontier is moving toward multi-attribute performance rather than single modifier identity. Technical studies on fatigue behavior and membrane performance indicate that leading companies are investing in evidence that supports long-term credibility. At the same time, broad polymer price increases show how quickly cost tension can enter the market and force strategic recalibration. Together, these signals point to a landscape that is not consolidating into one dominant model, but differentiating into several viable models based on technical proof, supply resilience, and application focus.
Market Structure and Evolution Trends
The market structure appears to be moving along three parallel tracks. One is mild consolidation through capability building, where companies acquire or develop hybrid formulations, testing documentation, and application-specific system knowledge rather than simply buying market share. A second track is fragmentation by application and geography, where regional specialists remain relevant because local climate, specification norms, and procurement behavior differ enough to reward localized expertise. A third track is the emergence of new entrants or expanding players in high-growth regions, particularly where infrastructure investment is accelerating and policy is favoring modified bitumen for demanding applications.
For incumbents, the strategic question is whether to defend through specification loyalty and technical proof, expand through hybrid or multi-application portfolios, or deepen regional presence where demand is growing fastest. For new entrants, the question is whether they can win by offering a clearly superior cost-performance combination, by serving an underserved application, or by building credibility through testing and documentation that reduces perceived risk. The market is not so concentrated that one strategy dominates, but it is mature enough that unsubstantiated claims are increasingly punished by informed buyers.
Future Outlook: Three Trends Shaping the Next 3–5 Years
Trend 1: Lifecycle Thinking Becomes a Commercial Standard
Over the next several years, lifecycle cost reasoning is likely to become more common in both public and private procurement. Asmore tenders and large projects adopt evaluation models that account for maintenance frequency, repair risk, and service life, modified bitumen products with stronger durability documentation will gain a structural advantage. This trend creates opportunity for manufacturers that can translate technical performance into procurement language: fewer failures, longer intervals between interventions, lower total cost over the project horizon. The risk side is equally important. Companies that compete only on initial price may retain wins in low-stakes applications, but they could lose ground in demanding road, roofing, and waterproofing projects where long-term performance is increasingly valued.
Trend 2: Hybrid and Application-Tuned Formulations Will Expand
Hybrid modifier systems and application-tuned formulations are likely to gain further traction as customers seek products that perform reliably under wider temperature ranges, repeated thermal cycling, and diverse installation conditions. The opportunity here is not simply launching more products; it is matching formulation to real service conditions and proving the match with credible testing. If hybrid products can demonstrably lower failure risk or extend performance windows in specific climates or usage profiles, they can command stronger specification positions. The uncertainty is that hybrid complexity can also raise manufacturing and quality control demands, so the winners will likely be those with disciplined production and consistent quality rather than those with the widest product list.
Trend 3: Input Cost Volatility Will Reward Supply Resilience
Polymer and resin input dynamics are expected to remain a strategic factor rather than a temporary disruption. Companies that can manage volatility through diversified sourcing, disciplined procurement, or formulation agility will be better positioned to protect margin and customer relationships. Conversely, suppliers with rigid input dependence or limited pricing transparency may face recurring pressure to either compress margins or risk customer pushback. This trend favors organizations that treat supply resilience as a commercial asset and communicate it clearly to buyers who are themselves managing project budgets against uncertain input markets.
Strategic Actions for Decision-Makers
For Manufacturers and Product Developers
Strengthen the link between product claims and verifiable evidence. Standard-aligned sampling, fatigue testing, and lifecycle-oriented performance data are becoming part of the commercial pitch, not just the technical file. Companies should prioritize hybrid and application-tuned formulations where they can prove a meaningful performance advantage, rather than expanding portfolios indiscriminately. Equally important is supply strategy. Polymer input volatility means that formulation flexibility, sourcing diversification, and transparent cost communication can be as valuable as technical features in winning and retaining business.
For Investors and Strategic Backers
Look for value in companies that combine technical credibility with realistic supply chain management. In a market growing with steady but not spectacular pace, the winners are likely to be those that earn specification loyalty through documented performance and manage margin pressure through disciplined procurement and formulation control. Regional demand pockets tied to infrastructure expansion and policy-driven PMB adoption deserve particular attention, especially where lifecycle procurement models are gaining traction. The key risk is overvaluing short-term price positioning without assessing whether that positioning is durable when standards, testing expectations, and input costs tighten.
For Procurement and Specification Leaders
Shift evaluation from installed price to evidenced total cost where the application justifies it. In high-traffic roads, exposed roofing, and critical waterproofing assemblies, the cheapest initial option can become the most expensive over time if it increases maintenance or shortens service life. Procurement teams should request standardized sampling and fatigue evidence, verify consistency across production batches, and assess supplier resilience to input cost volatility. That approach reduces the risk of specification regret and improves the odds of selecting a solution that performs through its intended life.
Closing Perspective
The polymer modified bitumen market is entering a phase where credibility, formulation intelligence, and supply resilience matter as much as raw material cost. Growth is expected to remain steady through the end of the decade, supported by infrastructure demand, evolving roofing and waterproofing expectations, and policy environments that increasingly reward lifecycle performance. The commercial opportunity lies in the details: hybrid formulations that are proven rather than merely announced, testing and documentation that lower perceived risk, regional strategies aligned with local procurement, and supply chains that can withstand input volatility without eroding customer trust. For organizations willing to look beyond headline size and focus on the drivers beneath it, the market offers a clear path to durable positioning. For those seeking a deeper map of segmentation dynamics, regional variation, and company-level benchmarking, the full research report provides the granular detail needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Polymer Modified Bitumen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com