

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Geomembranes Market Forecast 2026-2032: The 5.8% CAGR Trajectory Explained

Geomembranes Market: Strategic Trends and Commercial Opportunities Through 2032
The geomembranes market is entering a phase of steady, demand-led expansion. Valued at approximately $230 million in 2025 and projected to reach roughly $339.8 million by 2032, the sector is tracking a compound annual growth rate of 5.8 percent across the forecast period. This trajectory reflects a maturing industrial ecosystem where containment, environmental protection, and civil infrastructure needs are converging. Historical performance from 2020 through 2025 shows consistent year-over-year gains, with the market moving from $190 million in 2020 to $230 million at the base year. The forward outlook suggests that growth will be underpinned not by speculative cycles but by durable regulatory mandates, infrastructure renewal programs, and the continued scaling of mining and waste management operations.
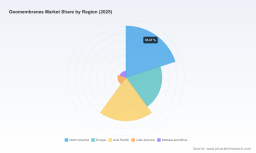
Regional activity is distributed across five major zones, with North America holding the largest share of revenue, followed by Asia Pacific and Europe. Latin America and the Middle East and Africa represent smaller but strategically important markets where mining expansion and municipal infrastructure programs are accelerating demand. The product mix is dominated by high-density polyethylene formulations, which account for the largest revenue pool, while low-density polyethylene, polyvinyl chloride, ethylene propylene diene monomer, and polypropylene collectively serve specialized containment and civil engineering applications. In terms of end use, mining and waste management represent the two largest application segments, with water management and tunnel lining and civil engineering forming meaningful secondary demand streams. The competitive structure remains moderately fragmented, with the top three players capturing roughly 24.6 percent of revenue and the top five reaching 26.2 percent, indicating room for both consolidation and niche differentiation.
Key Challenges and Inflection Points
Three structural challenges are shaping how manufacturers, project owners, and investors approach the geomembranes market. First, raw material volatility is compressing margins and complicating long-term pricing strategies. Polyethylene resin costs have moved upward in recent months, with HDPE prices rising on strong global demand and tight supply, while LLDPE and PVC have experienced region-specific swings tied to construction activity and inventory dynamics. Second, regulatory and certification requirements are raising the bar for product qualification. Stricter waste containment standards and technical specifications for HDPE geomembranes now require virgin resin formulations to achieve high chemical resistance thresholds, which adds a meaningful premium to compliant products. Third, installation quality and field performance remain persistent sources of risk. Even well-specified materials can underperform if welding, seam integrity, and site conditions are not tightly controlled, creating a gap between laboratory standards and real-world outcomes.
These challenges are also inflection points. Raw material pressure is pushing suppliers to explore blended and recycled formulations where standards permit, opening a pathway for cost-competitive sustainability offerings. Certification and compliance demands are favoring manufacturers with robust testing portfolios and documented quality systems, effectively raising barriers to entry for lower-tier competitors. And the growing emphasis on installation standards is creating opportunities for companies that can bundle materials with technical support, training, and warranty-backed execution.
Key Drivers of Market Change
Technological Innovation and Product Performance
Performance differentiation is increasingly tied to material engineering rather than basic containment capability. Manufacturers are advancing UV-resistant formulations, reinforced geometries, and chemical-resistant variants that extend service life in aggressive environments. The industry is also seeing more attention to welding reliability and seam integrity, which directly affects long-term leak prevention. Joint technical workshops and certification-focused initiatives are helping align installation practices with material capabilities, reducing the performance gap between specification and field results. For product leaders, the strategic implication is clear: incremental improvements in durability, weldability, and chemical resistance can command premium positioning, especially in mining and waste containment where failure costs are high.
Policy and Regulatory Environment
Regulatory momentum is one of the most reliable demand drivers in this market. In North America, stricter waste containment expectations and landfill standards continue to require geomembrane liners in the vast majority of new landfill projects to control fluid migration. Standards such as GRI-GM13 and ASTM D6693 reinforce the importance of certified HDPE performance, effectively shaping procurement requirements around tested chemical resistance and virgin resin formulations. These requirements do more than protect the environment; they structure the market by favoring suppliers that can demonstrate compliance at scale. For market participants, regulatory alignment is no longer a checkbox activity. It is a competitive asset that influences specification decisions, tender wins, and long-term contract eligibility.
Worldwide Rubber Membrane Market
Demand-Side Shifts in Mining, Waste, and Water Applications
Demand is being reshaped by how core end-use sectors approach containment and resource management. Mining operations continue to require robust liner systems for tailings, heap leach, and process water containment, particularly where environmental scrutiny and operational scale are increasing. Waste management remains a major application area, with landfill expansion and closure projects sustaining demand for durable liner and cover systems. Water management is an important secondary driver, supported by municipal water storage, treatment facilities, and infrastructure programs that need reliable containment solutions. Tunnel lining and civil engineering applications contribute additional specialty demand, particularly where structural durability and chemical exposure are concerns. The overall pattern is one of steady, application-diverse growth rather than reliance on a single vertical.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as raw material markets respond to demand and supply imbalances. Polyethylene pricing has shown upward pressure in recent periods, with resin costs moving higher in North America and Europe and spot prices reflecting tight conditions in key regions. PVC has experienced rebounds in parts of Asia tied to short-term construction demand, even as broader oversupply considerations persist. These dynamics matter because geomembranes are material-intensive products, and pricing sensitivity varies by application and procurement model. Suppliers that can manage resin sourcing strategically, optimize production lines, and offer formulation flexibility are better positioned to navigate price swings without losing specification share. At the same time, capacity expansions in key manufacturing locations are beginning to reshape regional availability and lead-time expectations.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of global specialists and regional players, each pursuing distinct positioning strategies. Solmax International Inc., headquartered in Canada, is widely recognized for HDPE and LLDPE geomembranes used in landfills, mining, and water containment, with product lines that emphasize UV resistance and recycled-material formulations alongside GRI-GM13 certification. Agru America Inc., based in the United States, focuses on advanced HDPE and LLDPE offerings, including eco-friendly recycled and blended variants for industrial and environmental applications. NAUE GmbH & Co. KG, in Germany, specializes in high-performance PVC and HDPE geomembranes with enhanced UV and chemical resistance for infrastructure and containment projects. Officine Maccaferri Spa, in Italy, manufactures reinforced and PVC geomembranes used in geotechnical engineering, waste containment, and erosion control. PLASTIKA KRITIS S.A., in Greece, supplies high-performance HDPE and PVC geomembranes with strong chemical resistance for industrial and mining uses.
PW Consulting
Additional participants broaden the competitive canvas. Carlisle SynTec Systems, in the United States, provides multi-layered and water-treatment facility geomembranes with an emphasis on durability and building code compliance. GSE Environmental Inc., also in the United States, produces HDPE and LLDPE geomembranes for landfill containment, mining, and aquaculture, supported by an extensive certification portfolio. Atarfil SL, in Spain, manufactures HDPE geomembranes for civil engineering and waste management applications. Firestone Building Products Company LLC, in the United States, specializes in EPDM and multi-layered geomembranes for roofing, water treatment, and environmental containment. JUTA Ltd., in Slovakia, offers geosynthetic solutions including HDPE and PVC geomembranes for infrastructure and environmental protection.
Strategic Positioning and Differentiation
Leading players are differentiating along three main axes. The first is certification and specification credibility. Companies with strong testing documentation and recognized certifications are better positioned to win tenders where compliance is non-negotiable. The second is application specialization. Some manufacturers concentrate on mining and waste containment, where chemical resistance and seam reliability are critical; others emphasize civil engineering, water treatment, or roofing-related containment where durability and code alignment matter more. The third is material flexibility. Suppliers that can offer virgin, blended, and recycled options, where permitted by standards, are able to serve a wider range of budget and sustainability requirements without sacrificing performance in approved use cases.
Market Evolution: Consolidation, Fragmentation, and New Entry
The market is showing signs of gradual consolidation among established players, but it is not becoming tightly concentrated overnight. Capacity expansions, such as the addition of a manufacturing line in Houston and the groundbreaking of a new production plant in Pune for civil engineering applications, indicate that incumbents are investing to capture regional demand and reduce lead times. At the same time, certification-focused activity and technical workshops point to an industry that is professionalizing installation and quality assurance, which benefits suppliers with stronger technical service capabilities. New entrants and regional specialists can still succeed by targeting niche applications, local project ecosystems, or specific material blends, but they face rising expectations around compliance, documentation, and field support. The likely trajectory is a layered competitive structure: a core group of globally certified suppliers competing on specification trust and scale, alongside regional and application-focused players competing on responsiveness, customization, and service proximity.
Future Trends and Commercial Opportunities
Trend 1: Compliance-Led Specification kesehatan Will Deepen
Over the next three to five years, specification decisions are likely to become even more tightly linked to certified performance and documented chemical resistance. As regulatory expectations remain firm and project owners seek to reduce long-term liability, procurement teams will continue to favor products with clear certification pathways and established testing records. The commercial opportunity here lies in building specification trust through transparency, repeatable quality, and strong field validation. Suppliers that can demonstrate consistent compliance across geographies and application types will be better positioned to secure recurring project flow, especially in waste containment and mining.
Trend 2: Regional Capacity and Service Models Will Redefine Competition
Capacity additions in North America and India signal a push toward closer-to-market production and faster response times. This trend is likely to intensify competition on lead time, supply reliability, and local technical support. For commercial teams, the opportunity is to pair material supply with installation guidance, seam quality assurance, and post-installation support. In practice, projects increasingly value a supplier that can help reduce installation risk, not just deliver rolled product. Companies that invest in technical service networks and structured training can convert capacity into higher-margin relationships rather than competing solely on price.
Fuel Cell Membranes Market
Trend 3: Material Innovation and Cost Navigation Will Separate Leaders from Followers
As resin markets remain volatile, the ability to manage formulation strategy will become a more visible competitive advantage. Opportunities will emerge for suppliers that can offer compliant virgin products where required, while also providing approved blended or recycled alternatives for applications that allow them. This dual approach can help customers balance sustainability goals, budget constraints, and performance requirements. The risk is that raw material swings and regional price divergence may pressure margins and create uneven competitiveness across geographies. Companies that lack sourcing flexibility or formulation options may find it harder to hold specification share when input costs move quickly.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Invest in certification clarity and application-specific messaging. The market rewards documented performance, so product communications should make compliance, testing, and suitability for specific environments easier to evaluate. Equally important is building installation support capability. Suppliers that help customers reduce seam and field risks can differentiate beyond material specs and create stronger project-level relationships. Finally, review formulation and sourcing strategies to ensure you can respond to resin price movements without losing competitiveness in approved use cases.
For Investors and Corporate Development Teams
Focus on companies with durable specification positions, recognized certifications, and the ability to serve multiple application segments without diluting quality. Capacity expansion can be a positive signal, but it should be evaluated alongside technical service strength and regional demand visibility. The most attractive opportunities are likely in businesses that combine material credibility with the ability to support installation and compliance needs, since those capabilities are becoming part of the competitive moat. Monitor regional capacity shifts and raw material trends, as they will influence margin trajectories and localization strategies.
For Procurement and Project Owners
Treat geomembrane selection as a total-project decision rather than a unit-price comparison. Evaluate certified performance, installation support, warranty structures, and long-term containment risk alongside initial cost. Where standards require virgin resin formulations, ensure that compliance claims are backed by appropriate documentation. Where blended or recycled options are acceptable, verify that performance expectations for the specific application are still met. Building a shortlist around technical fit and service reliability can reduce downstream risk and improve project outcomes.
Closing Perspective
The geomembranes market is evolving from a commodity-adjacent containment category into a more specification-driven, compliance-shaped, and service-sensitive market. Growth is expected to remain steady through 2032, supported by regulatory mandates, infrastructure and mining activity, and ongoing demand for reliable environmental containment. The companies that stand out will be those that combine certified product performance with strong installation support, formulation flexibility, and regional responsiveness. For decision makers, the most valuable next step is to align sourcing, investment, and product strategies with these shifting value drivers rather than relying on static assumptions. A detailed review of segment-level revenue splits, regional growth paths, and company-specific developments can sharpen those decisions further and help teams act with greater confidence as the market matures.
For detailed analysis of this topic, please visit the official page: Geomembranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com