

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Patient Infotainment Terminals Market: Why the 6.9% CAGR Signals Real Growth Beyond Hardware

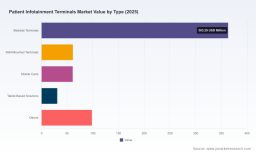
Patient Infotainment Terminals Market: Strategic Trends & Commercial Opportunities (2025–2032)
Hospitals and care facilities are no longer treating in-room technology as a luxury. The patient infotainment terminal has evolved into a critical interface connecting clinical workflows, patient satisfaction, and digital service delivery. From a market size of approximately $450 million in 2020, the sector has expanded to $614.2 million in 2025, with projections pointing toward $972.8 million by 2032 at a compound annual growth rate of 6.9%. This trajectory reflects more than incremental hardware upgrades; it signals a structural shift in how healthcare environments balance patient experience, operational efficiency, and connectivity demands. Understanding where the market is heading requires looking beyond headline growth figures and examining the forces reshaping procurement behavior, competitive positioning, and technology roadmaps.
Market Landscape and Core Challenges
A Mature but Still Expanding Sector
The patient infotainment terminal market has moved past its early adoption phase and entered a period of steady, infrastructure-driven expansion. Growth over the 2020–2025 period was propelled by hospital modernization programs, rising expectations for connected care environments, and the gradual normalization of digital bedside services across both acute and long-term care settings. The forecast horizon through 2032 indicates continued momentum, though the pace and shape of that growth will be uneven across regions, care models, and procurement cycles. North America currently represents the largest share of revenue, reflecting mature reimbursement frameworks, established hospital IT budgets, and a high density of integrated health systems. Europe follows as a significant contributor, shaped by national health digitization initiatives and evolving standards for medical-grade equipment. Asia Pacific, Latin America, and Middle East/Africa markets remain smaller in aggregate but are gaining attention as public and private providers invest in facility upgrades and patient-facing digital services.
Three Structural Challenges Shaping Decision-Making
First, the market operates under a misaligned cost-and-reimbursement dynamic. Advanced infotainment terminals require meaningful upfront capital for hardware, software platforms, and electronic health record (EHR) integration. At the same time, many healthcare systems lack dedicated reimbursement pathways for these devices, which places greater pressure on facilities to justify purchases through operational savings, patient satisfaction metrics, or bundled service contracts rather than direct revenue recovery. This gap between capital intensity and financial return creates longer procurement cycles and heightens sensitivity to total cost of ownership.
Second, compliance and certification requirements add complexity to product design and market entry. Medical-grade terminals must satisfy safety and performance expectations in clinical environments, including relevant electrical safety standards and device clearance pathways. For manufacturers, this means balancing feature innovation with documentation, testing, and regional conformity requirements. For procurement teams, it means evaluating not only user-facing capabilities but also the supplier’s ability to support installation, maintenance, and lifecycle compliance across multiple jurisdictions.
Third, the market is not highly consolidated, which creates both flexibility and fragmentation. The top three players account for roughly a quarter of revenue, and the top five expand that share only modestly. This level of concentration leaves room for regional specialists, integrated health IT partners, and new entrants to compete on niche capabilities, service models, or vertical-specific workflows. At the same time, it complicates standardization for large hospital networks that want consistent platforms across multiple facilities without sacrificing local customization.
Key Drivers of Market Change
Technology Innovation and the Infotainment-to-Clinical Continuum
The line between patient entertainment and bedside clinical utility continues to blur. Modern terminals increasingly combine media access, communication tools, and service functions with interfaces that support staff workflows or patient self-service tasks. Touchscreen interfaces, wireless remotes, integrated voice communication, and anti-microbial surface treatments have become baseline expectations rather than differentiators. More recent product activity points toward mobility and form-factor diversification, including compact medical-grade tablets designed for flexible clinical use alongside traditional bedside and wall-mounted configurations. This expansion matters because it changes the purchasing conversation: terminals are evaluated not only as fixed entertainment endpoints but as part of a broader device ecosystem that must interoperate with room controls, hospital applications, and connectivity infrastructure.
Policy, Standards, and the Satisfaction-Reimbursement Link
Policy and regulatory context plays a quiet but powerful role in shaping demand. Patient experience measurement influences a portion of Medicare reimbursement under value-based purchasing programs, which encourages hospitals to invest in services and environments that improve the patient journey. For infotainment terminals, that means capabilities such as intuitive content access, communication options, and reliable room integration can indirectly support financial performance by contributing to satisfaction outcomes. At the same time, medical-grade certification requirements and safety standards raise the bar for suppliers and create a higher barrier for low-cost, non-clinical-grade alternatives. The practical effect is a market where credible compliance positioning, documentation quality, and post-deployment support increasingly determine competitive endurance, especially in larger health systems that prioritize risk reduction.
Demand-Side Shifts in Patient Expectations and Care Models
Patients and families now expect digital convenience as part of the care experience. Access to entertainment, internet, communication tools, education materials, and service functions such as meal ordering has shifted from a value-add to a baseline expectation in many facilities. In long-term care and rehabilitation settings, the demand profile can be even broader, combining entertainment with communication, cognitive engagement, and simple service interactions. Concurrently, hospitals are looking for devices that reduce friction for staff by consolidating functions into a single bedside interface, supporting patient requests without excessive manual intervention, and maintaining compatibility with existing hospital applications. This dual pressure—patient-facing experience plus operational practicality—pushes vendors to design systems that are both user-friendly and clinically appropriate.
Supply Chain and Cost-Structure Realities
Hardware-led healthcare categories remain sensitive to component availability, build quality requirements, and installation complexity. High-touch deployments often depend on durable enclosures, anti-bacterial materials, and structured wiring approaches such as power-over-Ethernet installations. These requirements reinforce the importance of reliable sourcing, rigorous device testing, and service-level commitments. On the cost side, buyers are increasingly scrutinizing not just unit price but integration effort, training, warranty terms, and the potential need for software updates or expansion modules over time. In practice, this favors suppliers that can offer predictable deployment models, clear upgrade paths, and strong downstream support, especially in markets where hospitals are balancing capital budgets with operational continuity.
Competitive Landscape and Leading Strategies
Differentiation Through Medical-Grade Positioning and Workflow Fit
Competitive advantage in this market is less about offering the most features and more about offering the right combination of clinical appropriateness, usability, and integration readiness. Leaders tend to distinguish themselves through several recurring strategies. One is medical-grade hardware design, including anti-microbial surfaces, durable enclosures, and certifications aligned with clinical safety expectations. Another is software and service integration, where compatibility with patient portals, hospital applications, and communication platforms reduces deployment friction and improves user adoption. A third is form-factor breadth, spanning bedside terminals, wall-mounted units, carts, tablets, and other configurations that let facilities match devices to room types and care models.
Worldwide In-Car Infotainment Market
Several companies illustrate these strategic postures. Advantech focuses on medical-grade patient information terminals with anti-bacterial housing, touchscreen interfaces, voice integration, and bedside entertainment, and has continued expanding into mobile clinical use with compact tablet form factors. Onyx Healthcare offers compact healthcare infotainment terminals built around Intel processors, slim form factors, wireless remotes, voice communication with webcam capabilities, and anti-microbial surfaces aimed at patient wards and long-term care. PDi Communication Systems emphasizes healthcare-grade patient televisions and interactive bedside solutions with pillow speaker control, built-in entertainment, and compatibility with patient portal ecosystems such as Epic MyChart. Teguar positions around medical-grade all-in-one touchscreen PCs and infotainment terminals with antibacterial coatings and safety certifications, supporting both patient entertainment and staff-facing functions. ClinicAll International delivers integrated bedside infotainment terminals combining television, internet access, games, and digital hospital apps for patients, doctors, and staff. ITI Technology manufactures patient TV and bedside smart media devices with touchscreen interfaces that support internet access, entertainment, and specialized clinic applications such as dialysis settings. ARBOR Technology develops rugged patient infotainment terminals in multiple screen sizes that support menu ordering, bed controls, media, and access to patient record functions.
Market Evolution: Consolidation Pressures and Specialized Entry Points
The competitive field is evolving along two parallel tracks. On one hand, larger health systems and integrated device suppliers are pushing for more standardized platforms that can scale across sites, simplify support, and connect cleanly with existing IT and building infrastructure. That trend favors suppliers with broad portfolio depth, strong integration capabilities, and the ability to handle multi-site deployments. On the other hand, the relatively modest top-tier concentration leaves space for specialized players to win on vertical-specific features, regional service coverage, or differentiated user experiences. Recent market activity underscores this dynamism: new product introductions are extending device flexibility into mobile clinical use, while notable organizational changes, including acquisitions, are reshaping deployment scale and regional reach for established bedside terminal offerings. The implication for buyers and investors is that the market is not moving toward a single dominant architecture; instead, it is fragmenting by use case, care setting, and integration requirement, with consolidation likely to occur through partnerships, regional expansion, and selective acquisitions rather than outright dominance by a few global incumbents.
Forward-Looking Trends and Commercial Opportunities
Trend One: Convergence of Entertainment, Communication, and Care-Adjacent Services
Over the next three to five years, infotainment terminals are likely to be evaluated less as isolated entertainment screens and more as connected bedside hubs. The commercial opportunity lies in building platforms that can flexibly support media, communication, digital services, and light workflow interactions without overcomplicating the user experience. Suppliers that can modularize these capabilities—allowing facilities to enable or disable functions based on room type, patient population, or compliance requirements—will be better positioned to meet diverse procurement needs. For healthcare operators, the opportunity is to reduce device sprawl by consolidating functions into fewer, more capable endpoints that still respect clinical safety and usability constraints.
Trend Two: Wider Adoption of Mobile and Flexible Form Factors
Mobility and adaptability will become more important as care delivery continues to vary by ward, procedure type, and patient flow. Compact medical-grade tablets and cart-based solutions can extend bedside functionality into environments where fixed terminals are less practical, including consultation areas, mobile rounding, and certain long-term care scenarios. The strategic opportunity here is not simply smaller screens but more adaptable deployment models that preserve clinical-grade durability and hygiene considerations while supporting changing room configurations. Vendors that can prove reliability across mobile and fixed use cases may gain traction with organizations seeking to standardize on fewer hardware families.
Trend Three: Integration-Led Value Propositions replacing Spec-Led Competition
As basic hardware features become more commoditized, differentiation will increasingly depend on integration quality, support models, and measurable impact on the patient experience and staff workflow. Commercial opportunities will favor suppliers that can articulate a clearer path from device deployment to satisfaction outcomes, fewer service interruptions, and smoother connection with hospital applications and room systems. The risk is that buyers may struggle to compare offerings if integrations are highly customized or if value claims are not backed by deployment evidence. In that environment, transparent implementation requirements, well-defined compatibility scopes, and dependable post-sale support will become important decision criteria, not secondary considerations.
PW Consulting
Strategic Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Position products around clinical-grade credibility, usability, and integration readiness rather than feature volume alone. Investing in clear certification alignment, durable and hygienic design, and compatibility with common hospital applications can open more doors than adding marginal entertainment functions. In parallel, expanding form-factor options—especially mobile or hybrid configurations—can help capture demand in settings where fixed bedside placement is insufficient. Equally important is building a repeatable deployment and support story, since procurement teams increasingly weigh lifecycle cost and implementation risk alongside upfront pricing.
For Investors and Strategic Partners
The market’s moderate growth rate and fragmented structure suggest that value creation will come from targeted expansion, capability consolidation, and service-led differentiation rather than broad speculation on uniform demand. Attention should focus on suppliers with credible medical-grade positioning, evidence of integration momentum, and the ability to serve multiple care settings without diluting quality. Regional dynamics also matter: while North America and Europe represent established revenue bases, growth opportunities in other regions may depend on local partnerships, facility modernization timing, and the capacity to navigate varying compliance expectations. A phased, use-case-specific approach typically offers more clarity than betting on a single device category across all healthcare environments.
For Healthcare Procurement and Planning Teams
When evaluating infotainment terminals, the priority should be alignment with the facility’s broader digital and operational goals. That means assessing not only content and interface features but also EHR or portal compatibility, installation requirements, hygiene and safety certifications, and the supplier’s ability to support multi-site standardization if needed. Total cost of ownership should include integration effort, training, maintenance, and potential future expansion rather than hardware price in isolation. Where possible, pilot deployments in representative care settings can reveal whether a solution genuinely improves patient experience and reduces staff friction before broader rollout.
Patient Infotainment Terminal Market
Why Deeper Intelligence Matters Now
The patient infotainment terminal market is growing, but its shape is being defined by compliance demands, integration requirements, and diverse care settings rather than by a single product wave. For organizations making capital allocation, product strategy, or partnership decisions, broad market figures are useful only as a starting point. More useful are segment-level demand patterns, regional procurement nuances, competitive move analysis, and scenario-based estimates that account for variations in hospital budgets, certification requirements, and deployment models.
PW Consulting’s full research report provides a more detailed breakdown of market segments, regional dynamics, company strategies, and forward-looking estimates that can support more precise planning. The complete publication is designed for teams that need to move from general market awareness to actionable choices about where to invest, what capabilities to prioritize, and how to benchmark against evolving competitor activity.
For detailed analysis of this topic, please visit the official page: Patient Infotainment Terminals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com