

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why Titanium Dioxide Market's 6.5% CAGR and Asia's Dominance Redefine Supply Strategy for 2026-2032

Navigating the Titanium Dioxide Market: Strategic Trends and Commercial Opportunities in a Reshaping Industry
The global titanium dioxide (TiO2) market enters the mid-2020s as a commodity-defined sector undergoing structural repositioning. Total market revenue expanded from approximately $15.2 billion in 2020 to an estimated $21.8 billion in 2025, reflecting sustained demand growth across building, packaging, and consumer segments. The trajectory continues upward through the forecast window, with revenue projected to reach $23.54 billion in 2026 and climb gradually toward $33.7 billion by 2032, representing a compound annual growth rate of 6.5 percent over the full historical and forecast horizon. This expansion is not evenly distributed across geographies or applications. A handful of large-volume producers account for roughly 45 percent of global output when measured through the top three players, and the top five collectively hold about 55 percent of market share, underscoring a moderately concentrated landscape where scale, process efficiency, and vertical integration shape competitive advantage.
Market Snapshot and Structural Tension
Growth in the TiO2 sector has been supported by steady construction activity, packaging demand, and durable goods manufacturing. The pigment remains a core input wherever brightness, opacity, and weatherability intersect with cost-performance trade-offs. Yet the market is operating at a structural inflection rather than a simple cyclical upturn. Several overlapping forces are compressing margins in legacy operations while opening differentiated opportunities in specialty grades and region-specific supply configurations.
One of the most consequential tensions lies in the divergence between volume economics and value positioning. Standard chloride- and sulfate-based production continues to benefit from established infrastructure, but the cost base for ilmenite sourcing, energy-intensive refining, and waste management has become increasingly rigid. At the same time, buyers in coatings, plastics, and specialty applications are not solely pursuing the lowest-cost pigment; they are increasingly sensitive to consistency, regulatory compliance, formulation compatibility, and environmental footprint.
A second pressure point is the reconfiguration of trade and tariff flows. Import duties and anti-dumping measures have altered the relative attractiveness of different origin points, raising the cost of accessing lower-priced material in several major consuming regions. This has widened the effective cost gap between domestic or allied supply and import-dependent alternatives, particularly where shipping volatility and currency exposure compound tariff effects.
A third challenge is operational consolidation pressure. Select legacy sites face economic and regulatory headwinds that make continued operation less viable without significant capital investment or repositioning. Where site-level economics no longer align with demand geography or product mix, owners are choosing to divest, repurpose, or integrate assets into broader networks. This pattern is reshaping capacity availability and shifting where the next marginal ton of supply is likely to be added.
Key Drivers Shaping the TiO2 Market
Technological Innovation and Grade Differentiation
Process improvements and product innovation are moving beyond sheer volume toward tailored performance. Chloride process optimization remains a core lever for producers seeking lower specific energy use, improved particle morphology, and tighter control over surface treatment. These refinements translate into measurable benefits for end users: sharper tinting strength in architectural coatings, improved dispersibility in plastics, and more predictable rheology in inks and laminates.
Equally important is the expansion of formulation-friendly specialty grades. Developments such as TMP-free and TME-free pigment options reflect a broader industry push toward cleaner chemistries and reduced downstream processing burden. Removing or replacing auxiliary components can simplify compliance documentation, reduce customer exposure to restricted substances, and improve downstream compatibility in applications where additive load and clarity matter. In a market where specifications increasingly carry regulatory and sustainability meaning, grade differentiation is becoming a legitimate margin driver rather than a minor technical feature.
Policy and Regulatory Dynamics
Regulatory frameworks are no longer peripheral constraints; they are shaping where capacity is cheapest, where products can move, and how quickly new investment can be justified. Stringent rules on mining practices, tailings management, and waste disposal raise the operating cost floor for ilmenite-derived supply and tighten the economics of legacy sites with older environmental controls. For producers, this means capex must increasingly account for compliance infrastructure, monitoring, and closure obligations, not only plant throughput.
Trade measures add another layer of complexity. Additional duties on titanium ores and concentrates, along with tiered tariffs on imported TiO2 from certain origins, alter the cost comparison between domestic processing, regional production, and import substitution. Where anti-dumping duties limit the flow of lower-cost pigment into western markets, buyers and producers alike face a narrower set of economically viable sourcing options. The practical effect is a slower, more regionally anchored supply response, with investment tending to follow demand centers that offer both price stability and regulatory predictability.
Demand-Side Shifts in Coatings, Plastics, and Specialty End Uses
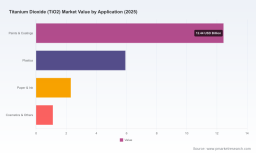
Demand composition is evolving as end-use industries adjust to new performance and sustainability expectations. Architectural and industrial coatings remain a foundational volume driver, but within this category, specifications are increasingly influenced by low-VOC formulations, durability targets, and color consistency under variable climate exposure. Plastics applications continue to draw substantial volume, yet the sector is increasingly attentive to dispersion stability, UV resistance, and the interaction of titanium dioxide with recycled resin streams. In packaging, inks, and paper, even small improvements in opacity or brightness can translate into material savings and improved print quality, reinforcing value-in-use arguments for higher-specification grades.
A notable shift is the growing weight of procurement committees evaluating total cost rather than pigment price alone. Formulation efficiency, coating adhesion, weatherability, and regulatory documentation now contribute to purchasing decisions. This behavioral change rewards suppliers who can demonstrate repeatable performance and offer technical support across multiple application families, rather than competing purely on headline pricing.
PW Consulting
Supply Chain and Cost Structure Realities
The cost structure of TiO2 production is increasingly influenced by upstream mineral economics, logistics, and the strategic positioning of processing assets. Raw material movement and import valuation have gained visibility as a macro indicator of supply-side exposure. In the United States, for example, the import value of titanium mineral and synthetic concentrates reached approximately $720 million in 2025, reflecting both demand strength and the sensitivity of domestic processing to feedstock availability and origin mix.
Energy intensity remains a defining cost driver for chloride routes and for certain sulfate operations. Where energy prices are volatile or where carbon-related charges and reporting requirements tighten, the relative economics of older versus newer assets can shift materially. Producers with access to integrated feedstock, stable energy sourcing, and modern process controls are better positioned to absorb cost shocks without passing through disruptive price moves that erode customer relationships. Meanwhile, logistics constraints and port volatility can amplify regional supply tightness, especially when combined with tariff structures that already limit arbitrage across origins.
Competitive Landscape and Leading Strategies
Scale, Integration, and Brand Positioning
The leading producers in this market share a few common strategic anchors: process leadership, vertically integrated feedstock access where feasible, and the ability to serve multiple application families with consistent quality. The Chemours Company operates one of the largest chloride-based TiO2 platforms under the Ti-Pure™ brand, supplying grades across coatings, plastics, laminates, and paper. Its positioning emphasizes broad application coverage and formulation reliability, leveraging a large-scale process footprint to support volume demand while maintaining technical service for specification-driven customers. This type of multi-application scale is valuable when buyers seek a single supplier capable of standardizing pigment performance across several product lines.
Tronox Holdings plc takes a different structural advantage through vertical integration across mining and processing of ilmenite and rutile, with multiple pigment plants supporting architectural, industrial, and specialty applications. The integration thesis is straightforward: closer control of raw material supply can reduce exposure to third-party price swings and improve the cost predictability of the pigment stream. In a market where feedstock economics and compliance obligations increasingly shape operating costs, vertical integration can provide a defensive moat, provided the company can manage capital intensity and environmental stewardship across the value chain.
Venator Materials plc focuses on TiO2 pigments and performance additives, offering TIOXIDE® grades for coatings, plastics, inks, and paper. Its strategy reflects a growing industry tilt toward product differentiation and portfolio agility. Recent actions illustrate the balance between portfolio optimization and innovation: the company introduced a TMP- and TME-free TIOXIDE® TR85 pigment grade, aiming to address formulation and regulatory preferences, while also pursuing site-level asset rationalization through the sale of its Greatham, UK TiO2 site and associated assets. This combination signals a pragmatic approach: invest in grades that create value and reduce exposure where assets no longer fit the demand or cost profile.
Established Technical Leadership and Regional Strengths
Other major players illustrate how long-standing process heritage and regional focus continue to matter. Kronos Worldwide, Inc. has built a reputation over more than a century as a specialized producer of high-performance TiO2 pigments for coatings, plastics, and industrial applications, with a focus on consistency and technical service. LB Group Co., Ltd. competes with high-performance pigments under the BILLIONS™ brand, using both chloride and sulfate processes to serve coatings, plastics, inks, and laminates across demanding specifications. Ishihara Sangyo Kaisha Ltd. holds a leading position in Japan’s TiO2 market, with chloride-process production supporting paints, coatings, and industrial uses where regional demand quality and service expectations remain elevated. Cristal Global operates as a large global producer with manufacturing plants in multiple countries and a dual process strategy spanning chloride and sulfate routes.
Worldwide Pigment-grade Titanium Dioxide Market
Rather than competing on a single dimension, these companies typically differentiate through combinations of process control, application engineering, and customer proximity. In practice, the most defensible positions often come from the ability to provide reliable particle morphology, surface treatment consistency, and technical guidance that helps customers reduce cost-in-use rather than simply lower pigment price.
Where the Landscape Is Heading
The market is likely to see continued selective consolidation and portfolio reconfiguration rather than uniform expansion. Some assets will be sold or closed as their economics diverge from core demand geography, process modernization needs, or environmental obligations. At the same time, product innovation will increasingly reward companies that can combine performance differentiation with regulatory alignment. New entrants face a meaningful barrier not only because of capital intensity but because customer qualification cycles, supply reliability expectations, and application-specific testing create inertia around incumbent suppliers. The practical result is a market where scale and process credibility matter, but where specialty positioning can still generate meaningful separation within a moderately concentrated structure.
Future Trends and Commercial Opportunities
1. Regional Supply Realignment Around Tariff and Compliance Realities
Over the next three to five years, supply geography is likely to continue adjusting to duty structures, environmental requirements, and logistics efficiency. In consuming regions where import costs are elevated by duties and where domestic or allied production benefits from freight and compliance advantages, there may be stronger incentives for regional capacity investment and long-term supply agreements. For commercial teams, this trend signals an opportunity to secure more predictable input costs by aligning sourcing with the geography of demand and the origin mix most resilient to policy shifts.
The risk is that tightening supply in certain corridors could increase volatility for buyers who rely heavily on import-dependent alternatives without qualifying secondary sources. Companies that lock in diversified origin coverage and contractual flexibility will be better positioned to manage price swings and maintain formulation continuity.
2. Premiumization Through Specialty Grades and Cleaner Formulations
As end users increasingly weigh regulatory exposure, downstream safety, and formulation compatibility, there is room for value capture in specialty grades that reduce processing burden or improve performance in targeted applications. The emergence of cleaner auxiliary chemistries and more application-specific surface treatments suggests a path where margin is earned through specification leadership rather than only through volume efficiency. For pigment suppliers, this implies a strategy of targeted R&D investment, stronger technical marketing, and closer engagement with formulators in coatings, plastics, and inks.
For downstream manufacturers, the commercial opportunity lies in leveraging such grades to improve end-product durability, reduce defect rates, or simplify compliance documentation. The trade-off is that premium grades usually carry higher unit costs, so the value case must be demonstrated through total cost, throughput improvement, or finished-product performance rather than pigment price alone.
3. Cost Optimization and Asset Rationalization as a Competitive Filter
Where energy, feedstock, waste handling, and compliance costs are rising, the gap between modern and legacy operations may widen further. This will likely function as a competitive filter: well-capitalized producers with efficient process design and disciplined asset portfolios will be better equipped to maintain service levels and pricing stability, while weaker assets may be divested or repurposed. For investors and corporate strategists, this means the next wave of meaningful value creation may come less from broad market growth alone and more from selecting assets and portfolios that align with the cost and compliance profile of the coming cycle.
The uncertainty here is timing and magnitude. Demand growth can partially offset cost pressure, but if construction or packaging activity softens, or if energy prices spike, capacity rationalization could accelerate faster than new investment can respond, creating short-term tightness followed by adjustments once new supply comes online.
Strategic Implications for Decision Makers
For Manufacturers and Producers
Focus on process efficiency and grade differentiation as parallel priorities. Volume economics still matter, but they are increasingly intertwined with compliance readiness, energy resilience, and application engineering. Where portfolio composition allows, prioritizing grades that reduce downstream friction or address regulatory preferences can support pricing power and customer retention. At the same time, review asset portfolios for sites where operating economics, logistics, or environmental obligations create structural drag, and consider whether divestiture, upgrading, or integration into a broader network offers better long-term value. In practical terms, the winning posture is likely to be one that combines disciplined cost control with credible performance advantages that customers can validate in their own formulations.
For Investors
Evaluate exposure through the lens of integration, process modernity, and regulatory resilience rather than headline revenue alone. Vertically integrated producers may offer cost predictability and feedstock control, while firms with differentiated specialty grades can provide exposure to higher-value segments. Pay close attention to geographic exposure relative to duty and compliance regimes, because the economic profile of a plant can change materially depending on origin mix, logistics costs, and local environmental requirements. Diversification across processes and end-use families can reduce vulnerability to single-cycle shocks, but it should not come at the expense of losing visibility into where margin is actually being earned.
For Procurement and Formulation Teams
Treat pigment sourcing as a total-cost and continuity problem. If current sourcing depends heavily on a single origin or a narrow cost band, consider qualification of alternative grades or secondary origins that can step in when tariff or logistics conditions shift. Build supplier relationships that include technical support, specification stability, and documentation for regulatory compliance, because these capabilities increasingly contribute to avoided costs in formulation and downstream processing. When evaluating premium grades, test them against real process constraints—dispersibility, coating consistency, UV stability, and compatibility with recycled or blended resins—so that purchasing decisions are anchored in performance and operational reliability, not just unit price.
Closing Perspective
The TiO2 market is moving through a period in which growth, cost pressure, and regulatory adjustment are reshaping who competes effectively and how value is created. Demand continues to expand across major application families, and the long-term trajectory points toward higher global revenue, but the character of that growth is changing. Suppliers that combine scale with process discipline, differentiation with compliance readiness, and geographic flexibility with customer proximity are likely to capture the most durable advantages.
TiO₂ Pigment Market
For organizations making sourcing, investment, or product strategy decisions, the most useful intelligence is not just the size of the market but the interplay of tariffs, compliance costs, grade innovation, and asset rationalization that determines where supply will be available and at what cost structure. Detailed segmentation data, region-specific cost modeling, and application-level demand profiles can sharpen those decisions significantly. A full market study can provide that level of granularity, including breakdowns by region, type, and application, along with scenario analysis for tariff and compliance shifts, so decision makers can translate broad trends into concrete portfolio, sourcing, and investment moves.
For detailed analysis of this topic, please visit the official page: Titanium Dioxide (TiO2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com