

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Spinal Fusion Market: Why the 7.19% CAGR Signals a Strategic Shift

Strategic Shifts and Commercial Opportunities in the Global Spinal Fusion Market
The global spinal fusion market has matured into a multi-billion-dollar sector defined by steady growth, technological differentiation, and evolving reimbursement landscapes. From 2020 through 2025, the market expanded from approximately 4.1 billion USD to 5.98 billion USD, reflecting a compound annual growth rate of 7.19 percent through 2032. This trajectory signals sustained demand for fusion technologies across cervical, thoracolumbar, interbody, and biologic applications. While the absolute figures indicate a healthy industry, the underlying dynamics reveal a market at an inflection point. Decision-makers navigating this space must look beyond headline growth rates to understand where value is being created, which segments are consolidating, and how regulatory and reimbursement shifts are reshaping competitive positioning.
Market Landscape and Structural Challenges
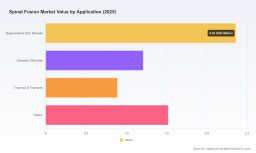
The market's expansion over the past half-decade has been broad-based, with mature regions continuing to dominate revenue generation while emerging markets contribute incremental growth. North America remains the largest revenue contributor, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but increasingly relevant footprints. The revenue distribution across device categories shows thoracolumbar and biologic segments commanding significant share, while cervical and interbody devices maintain strong, steady demand. Application-wise, degenerative disc disease continues to drive the largest volume, with complex deformity, trauma, and other indications rounding out the clinical demand profile.
Despite the favorable growth trajectory, the industry faces structural headwinds that will define competitive outcomes over the next several years. Three challenges stand out as particularly consequential for strategy formulation.
Reimbursement Pressure and Procedural Migration
Cost containment efforts across public and private payers have intensified scrutiny on spinal procedures. The removal of over 75 spine and cranial procedures from the Inpatient Only list as of January 2026, alongside the addition of more than 100 codes expanding outpatient payment options, reflects a deliberate shift toward ambulatory and outpatient settings. While this migration can reduce system-wide costs, it also compresses hospital revenue per case and alters the purchasing dynamics for device manufacturers. Vendors that rely heavily on inpatient volume must adapt their commercial models, clinical education, and product portfolios to support outpatient workflows and shorter length-of-stay protocols.
Hospital Cost Escalation and DRG Restructuring
Annual hospital costs for inpatient lumbar fusion increased by more than 265 percent between 2002 and 2023, a trend that has drawn sharp attention from health system finance leaders. Recent DRG revisions that separate one-level from multilevel fusions further complicate reimbursement predictability and encourage hospitals to scrutinize implant pricing, surgical efficiency, and total episode costs. This environment rewards technologies that demonstrably reduce operating time, minimize complications, or enable less invasive approaches. It also creates friction for premium-priced implants that lack robust health economic evidence or clear differentiation in clinical outcomes.
Regulatory Velocity and Evidence Expectations
The pace of 510(k) clearances has accelerated, with multiple intervertebral stabilization and interbody systems receiving clearance in 2025 and 2026. While this regulatory openness encourages innovation, it also raises the bar for post-market evidence and clinical differentiation. Clinicians and hospital value analysis committees increasingly expect peer-reviewed data, real-world evidence, and functional outcome metrics rather than reliance on predicate comparisons alone. Companies that cannot articulate a clear clinical value proposition risk commoditization, particularly in crowded interbody and fixation categories.
Key Drivers Shaping Market Evolution
Several interconnected forces are propelling the spinal fusion market forward while simultaneously reshaping competitive dynamics. Understanding these drivers is essential for identifying where commercial opportunities will concentrate and which strategic bets are likely to pay off.
Technological Innovation and Enabling Platforms
Innovation in spinal fusion has moved beyond incremental implant improvements to encompass enabling technologies that change how procedures are planned, navigated, and executed. AI-enabled navigation systems, minimally invasive access platforms, and expandable interbody devices are reducing soft tissue disruption, improving placement accuracy, and supporting faster recovery trajectories. The recent FDA 510(k) clearance of the LOGIC Titanium Expandable Interbody System and the limited market launch of the Ventana A Anterior Lumbar Interbody Fusion System illustrate how new entrants and established players alike are pursuing differentiation through expandable and anterior approaches. These technologies appeal to surgeons seeking greater procedural control and to hospitals aiming to reduce length of stay and complication rates.
Regenerative Therapeutics and Biologic Integration
The fusion category is being reshaped by advances in biologics and regenerative therapeutics that aim to improve arthrodesis rates and reduce pseudarthrosis risk. Protein-based regenerative platforms, such as OsteoAdapt, are advancing through pivotal clinical trials, signaling a potential shift toward adjuncts that enhance bone healing and support complex cases. Simultaneously, electromagnetic bone growth stimulators and interbody fixation systems continue to serve as complementary tools in fusion protocols. The integration of biologics with device portfolios is becoming a strategic lever for companies seeking to offer comprehensive solutions rather than standalone hardware. As clinical evidence matures, biologics may become a key differentiator in value analysis discussions, particularly for multilevel and complex deformity procedures where fusion success is paramount.
Worldwide Spinal Orthosis Market
Policy, Reimbursement, and Coding Dynamics
Policy and reimbursement changes are acting as both enablers and constraints. Updated CPT code sets for SI joint fusion with new billing and reimbursement guidelines have clarified pathways for a historically niche but growing indication. At the same time, broader outpatient migration and DRG restructuring are pushing providers to optimize procedural economics. For manufacturers, these shifts create opportunities to align product design and clinical programs with outpatient-friendly workflows, to support coding and billing education for ambulatory surgery centers, and to develop evidence packages that justify premium positioning in cost-conscious environments. Companies that proactively engage with coding updates and reimbursement education can influence adoption curves more effectively than those relying solely on product features.
Supply Chain Reconfiguration and Portfolio Rationalization
Strategic portfolio actions are reshaping the competitive map. The completion of the sale of Stryker's U.S. spinal implants business to VB Spine, LLC, while retaining its interventional spine portfolio, highlights a broader pattern of asset realignment. Highridge Medical's acquisition of porous interbody cages and fixation systems from a prior Zimmer Biomet portfolio further illustrates how legacy assets are being repositioned. These transactions reflect a market in which some large platforms are focusing on adjacent high-growth areas, while specialized entities and acquirers seek to build coherent fusion franchises. For suppliers, this landscape means shifting distribution relationships, evolving service expectations, and opportunities for companies that can offer reliable supply, technical support, and localized account management.
Competitive Landscape and Strategic Positioning
The spinal fusion market is characterized by a concentrated leadership group alongside a dynamic cohort of specialized innovators. The top players collectively account for a substantial share of revenue, with the top three holding approximately 62 percent and the top five around 65 percent. This concentration reflects the advantages of scale, established surgeon relationships, integrated navigation and imaging platforms, and broad product lines spanning cervical, thoracolumbar, interbody, and biologic categories. Yet concentration masks significant variation in strategic posture, with leaders pursuing different paths to differentiation.
Mature Leaders and Integrated Platforms
Medtronic exemplifies the integrated platform approach, offering a comprehensive spine portfolio that combines AI-enabled navigation, bone grafting technologies, and fusion solutions across multiple anatomical segments. Its strategic advantage lies in the ability to position fusion procedures within a broader ecosystem of planning, navigation, and intraoperative support, which can deepen hospital relationships and create switching costs. Globus Medical has carved a distinct position through a focus on minimally invasive spine solutions, including lateral interbody fusion systems, TLIF spacers, and enabling technologies. Its differentiation centers on procedural efficiency, surgeon preference for minimally invasive workflows, and targeted clinical education. Orthofix contributes a focused set of interbody fixation systems, biologics for fusion promotion, and electromagnetic bone growth stimulators, positioning itself at the intersection of hardware and biologic adjuncts.
Specialized Innovators and New Entrants
A second tier of companies is pursuing niche differentiation through device design, material innovation, and indication-specific focus. SI-BONE has built recognition around minimally invasive sacroiliac joint fusion with the iFuse Implant System, targeting SI joint dysfunction with a specialized platform. Spine Innovation and Spinal Elements represent innovators advancing expandable and 3D-printed titanium interbody systems, with recent FDA clearances supporting limited market launches and expanded indications. Spinal Elements' 3D-printed titanium interbody systems and ALIF and cervical platforms reflect a broader industry interest in surface architecture and porous designs intended to support osseointegration. ChoiceSpine and Highridge Medical illustrate how focused interbody portfolios and acquired legacy assets can establish footholds in cervical and lumbar categories. Theradaptive's protein-based regenerative therapeutics, currently advancing through pivotal trials, signal the potential for biologic adjuncts to reshape fusion protocols over the medium term.
Portfolio Transactions and Market Realignment
The market is experiencing both consolidation and fragmentation simultaneously. Stryker's divestiture of its U.S. spinal implants business while retaining an interventional spine portfolio, alongside acquisition activity involving porous interbody cages and fixation systems, indicates that large players are recalibrating exposure while specialists and mid-sized entities seek to assemble coherent product lines. K2M's integration into Stryker's interventional spine business further underscores the value of navigation, fixation, and implant platforms that support fusion techniques. These transactions create shifting account relationships, renegotiated distribution agreements, and opportunities for companies that can rapidly integrate acquired assets, preserve customer relationships, and maintain clinical support. For investors, such realignment often signals where management teams believe value lies and where they intend to concentrate resources.
Worldwide Spinal Traction Market
Forward-Looking Trends and Commercial Implications
Looking ahead over the next three to five years, several trends are likely to shape where growth concentrates and how competitive advantage is built. These trends carry direct implications for product strategy, commercial execution, and investment allocation.
Outpatient and Ambulatory Expansion
The migration of spinal fusion procedures toward outpatient and ambulatory settings is expected to continue, driven by reimbursement incentives, patient preference, and enabling technologies that support safer same-day discharge. This trend favors devices and workflows optimized for shorter operative times, reduced blood loss, and simpler postoperative management. Companies that provide navigation, minimally invasive access, and implant designs compatible with outpatient environments are positioned to capture adoption as ASC volume grows. The expanding outpatient payment options introduced in 2026 broaden the addressable footprint for fusion procedures, but they also require commercial teams to engage ASCs, support coding education, and tailor pricing and service models to lower-volume, higher-throughput environments.
Differentiation Through Evidence and Health Economics
As cost pressure intensifies and DRG restructuring separates one-level from multilevel fusions, evidence will become an increasingly decisive factor in procurement and value analysis. Technologies that can demonstrate reduced complications, shorter length of stay, fewer revisions, or improved functional outcomes will be better positioned to defend premium pricing. The trend toward biologic adjuncts and regenerative therapeutics also raises the importance of clinical data; pivotal trial results and real-world registries will influence whether new biologics become standard adjuncts or remain niche options. Manufacturers and investors should anticipate that health economic evaluations and outcomes data will function as gatekeepers to formulary inclusion and contract negotiations.
Material and Design Innovation as a Moat
Advancements in implant materials and architecture, including porous titanium, 3D-printed structures, and expandable interbody designs, are likely to remain a source of differentiation. These features appeal to surgeons seeking improved biocompatibility, osseointegration, and intraoperative flexibility. Recent clearances for trabecular PEEK systems, expandable interbody implants, and dynamic stabilization devices indicate sustained innovation activity. While material and design innovations can create meaningful clinical appeal, their commercial success will depend on the strength of clinical evidence, ease of use, and integration with surgical workflows. Companies that combine innovative engineering with robust training, clinical support, and outcomes messaging are more likely to convert technical advantage into market share.
Potential Risks and Uncertainties
The outlook is not without risk. Reimbursement uncertainty persists, particularly if payers respond to outpatient expansion by recalibrating payment rates or if cost pressures lead to stricter utilization management. Regulatory clearance velocity can be offset by post-market scrutiny and evolving clinical evidence requirements, creating execution risk for new entrants. Concentration in the leadership group may limit bargaining power for smaller players and increase competitive intensity for share in mature categories. Finally, portfolio transactions can disrupt established supply relationships and account coverage, creating transition risk for hospitals and surgeons reliant on legacy products. Stakeholders should monitor these uncertainties and build flexibility into product, pricing, and commercial strategies.
PW Consulting
Actionable Guidance for Decision-Makers
Different stakeholder groups face distinct strategic priorities in this evolving market. The following considerations can help align organizational actions with the trends shaping spinal fusion.
For Manufacturers
- Align product development and lifecycle planning with outpatient and ASC workflows, including instrumentation that supports efficient cases and implants suited to less invasive access.
- Invest in health economic evidence and outcomes data that can support value analysis committees, particularly for multilevel and complex deformity procedures where cost scrutiny is highest.
- Evaluate biologic and regenerative adjacencies as potential portfolio complements, and ensure clinical programs and reimbursement education keep pace with coding updates for SI joint fusion and other indications.
- Strengthen surgeon and hospital engagement through training, navigation integration, and service reliability to deepen loyalty in a concentrated market.
For Investors
- Assess opportunities based on clinical differentiation, evidence readiness, and reimbursement alignment rather than device category growth alone.
- Watch portfolio transactions and asset transfers as signals of where platform owners are concentrating resources and where specialized acquirers are building coherent fusion franchises.
- Consider the timing of pivotal trial readouts for regenerative therapeutics and the potential for biologic adjuncts to expand addressable use cases in complex fusion scenarios.
- Evaluate commercial execution capabilities, including account management in transitioning distribution landscapes and the ability to engage ASC and outpatient Channels effectively.
For Procurement and Health System Leaders
- Structure value analysis to weigh total episode costs, including operative efficiency, complication avoidance, and length of stay, rather than unit price in isolation.
- Engage suppliers on coding and reimbursement education, especially as outpatient expansion and SI joint fusion coding updates change billing pathways.
- Request evidence packages that differentiate products in your specific procedural mix, and consider pilot programs for enabling technologies that may reduce downstream costs.
- Monitor supply continuity and service support during portfolio transitions to avoid disruption in high-volume fusion programs.
The spinal fusion market is expanding steadily, but the most consequential opportunities are emerging at the intersection of technology, reimbursement, and evidence. Companies and investors that understand where procedural migration is heading, which innovations can withstand cost pressure, and how portfolio realignment is reshaping account relationships will be better positioned to capture value. For decision-makers seeking deeper segmentation, pricing dynamics, and tailored strategic recommendations, accessing the full research report provides the detailed data and scenario analysis needed to convert market insight into actionable planning.
For detailed analysis of this topic, please visit the official page: Spinal Fusion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com