

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LFT Market Trends: How 7.2% CAGR and Asia Pacific Growth Reshape Competition by 2032

Strategic Trends and Commercial Opportunities in the Long Fiber Thermoplastics Market
The global Long Fiber Thermoplastics (LFT) market has entered a phase of structural expansion, driven by the confluence of lightweighting mandates, electrification waves, and material science breakthroughs. Valued at approximately 1.8 billion USD in 2020, the market reached 2.58 billion USD by 2025, reflecting a compound annual growth rate (CAGR) of 7.2% over the review period. Projections indicate sustained momentum, with revenues expected to climb from 2.83 billion USD in 2026 to 4.2 billion USD by 2032. This trajectory is not merely a volume story; it represents a fundamental shift in how industries approach structural material selection, balancing performance, processability, and lifecycle economics.
Central to this growth is the market's concentration profile, which underscores the strategic importance of early movers and technology holders. The top three players command over half of the market value, while the top five collectively capture nearly two-thirds. Such concentration reflects high barriers to entry, including proprietary compounding technologies, long-term customer validation cycles, and capital-intensive processing infrastructure. Yet, the landscape is not static. Regional dynamics reveal divergent maturity levels and application adoption speeds, while new entrants are testing niche formulations and localized supply chains. For decision-makers, this environment demands a clear mapping of where value is created, where margins are pressured, and where partnerships can accelerate commercialization.
Market Snapshot and Core Challenges
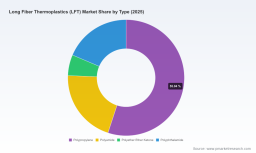
The LFT market's expansion is anchored by consistent demand from structural and high-performance applications that require a favorable strength-to-weight ratio, impact resistance, and recyclability compared to traditional composites. Polypropylene-based formulations lead the type segmentation by volume and revenue, reflecting their cost efficiency, wide processing window, and broad compatibility with existing injection molding and compression tooling. Polyamide and polyphthalamide grades capture significant demand in under-hood and load-bearing components, while polyether ether ketone (PEEK) remains a specialized segment for extreme thermal and chemical environments. Application demand is led by automotive, where lightweight structural components and battery enclosure requirements are accelerating adoption, followed by electrical and electronics, industrial equipment, and diversified end-use segments. Regionally, Asia Pacific represents the largest revenue share, supported by manufacturing scale and rapid OEM localization, while Europe and North America sustain steady growth through stringent emissions targets and advanced engineering specifications. Latin America and the Middle East/Africa contribute smaller but strategically relevant volumes, often tied to regional automotive production hubs and infrastructure modernization.
Despite favorable momentum, the industry faces three interconnected challenges that will shape competitive outcomes over the next five years:
- Raw material cost volatility and fiber mix decisions. Glass fiber remains the dominant reinforcement by value, favored for its cost profile and processability. However, carbon fiber prices have experienced significant downward pressure due to overcapacity, with Chinese market prices approaching 18 USD per kg in 2023 and continued softness extending into 2026. This dynamic creates both opportunity and risk: compounding players can lower input costs but must navigate margin compression if end-users assume price declines will persist. Formulation strategy is increasingly about matching fiber type to performance requirements without over-engineering cost.
- Regulatory and trade friction in supply chain design. Evolving trade policy, including recent tariff actions affecting LFT products in the United States, has introduced new complexity into sourcing logic. Export scenarios, regional content requirements, and localization incentives are prompting OEMs and compounders to reconsider plant footprints, qualification pathways, and inventory buffers. Companies that treat trade exposure as a structural variable rather than a transient disruption are better positioned to maintain service levels and margin integrity.
- Qualification timelines and performance validation. LFT adoption in structural and safety-relevant applications requires prolonged testing, OEM endorsement, and tooling adaptation. The gap between material capability and production qualification can slow revenue conversion even when technical merit is clear. This creates a market where differentiation is built not only on polymer chemistry but also on application engineering, processing support, and co-development models that reduce time-to-production.
For executives, the practical implication is clear: demand is robust, but profitable growth will be determined by how well organizations manage input cost volatility, navigate trade-related sourcing shifts, and compress qualification cycles through closer customer collaboration.
Key Demand Drivers and Underlying Dynamics
The LFT market's trajectory is shaped by several reinforcing forces that go beyond cyclical demand. Understanding these drivers helps frame where investment and capability-building will yield the highest return.
Lightweighting, Electrification, and Structural Performance Requirements
The push for fuel efficiency and emissions reduction has long supported LFT adoption, but electrification has altered the value proposition. Electric vehicles require weight management to extend range, while battery packs and structural enclosures demand components that combine stiffness, impact resistance, and thermal stability. LFT compounds are increasingly specified for load-bearing parts, interior structural elements, and under-hood assemblies where metal replacement can reduce system weight without sacrificing durability. This trend is not limited to passenger vehicles; industrial equipment and electrical/electronics applications also benefit from components that resist vibration, fatigue, and environmental stress. The core insight for strategists is that lightweighting is no longer a single-market story; it is becoming a cross-industry engineering standard, expanding the addressable base for reinforcement-rich thermoplastics.
Technological Innovation in Fiber Reinforcement and Compound Design
Material innovation is shifting from incremental improvements to targeted performance architectures. Enhanced carbon fiber-reinforced grades are expanding the envelope for stiffness-critical applications, while long glass fiber concentrates continue to optimize cost-performance trade-offs. Product introductions spanning long glass and carbon fiber reinforcements, high-fiber concentrates for demanding automotive specifications, and specialized granules for rigid, impact-resistant components reflect a broader industry move toward application-tailored compounding. Recent platform launches have also emphasized large-scale part production and advanced functional materials, signaling a focus on manufacturing throughput and part consistency alongside mechanical properties. For suppliers, the strategic lesson is that differentiation now depends on combining fiber architecture, base resin selection, and processing support into a cohesive solution that reduces downstream trial-and-error.
Policy, Regulatory, and Trade Environment
Regulatory mandates around emissions, fuel economy, and material circularity continue to influence material selection, but trade policy is increasingly a first-order planning variable. Tariff adjustments on LFT products have altered export economics and prompted supply chain re-evaluation, especially for companies operating across multiple regions. The practical effect is a tighter coupling between technical performance and commercial feasibility: a compound that meets specification may still underperform commercially if sourcing costs, logistics, or regional content rules are misaligned. This environment rewards organizations that build regional flexibility, maintain dual-sourcing options for key reinforcements, and integrate trade scenario planning into product launch roadmaps.
Supply Chain Reconfiguration and Cost Structure Shifts
Cost structures in LFT are being reshaped by fiber pricing trends, resin availability, and regional manufacturing capacity. The relative affordability of glass fiber versus carbon fiber continues to steer volume decisions, while carbon fiber price softening in key producing regions introduces new possibilities for stiffness-intensive designs at lower cost. At the same time, supply chain localization is gaining importance as OEMs and compounders seek resilience against logistics volatility and policy shifts. Companies that can align resin sourcing, fiber supply, compounding capability, and customer-facing application engineering within a coherent geographic and commercial framework are better equipped to protect margins and accelerate adoption.
Competitive Landscape and Strategic Positioning
The LFT market features a mix of global specialty players, regional compounders, and technology-focused entrants. Their strategies reveal distinct approaches to differentiation, customer alignment, and geographic expansion.
PW Consulting
Celanese Corporation emphasizes structural automotive and industrial applications through long carbon and glass fiber-reinforced product lines, with recent portfolio expansion focused on enhanced carbon fiber-reinforced grades. This positions the company around performance-intensive applications where stiffness and durability justify premium value. SABIC has advanced its MEGAMOLDING platform to support large-scale, high-performance thermoplastic parts using LFT materials, highlighting a focus on manufacturing efficiency and tooling scalability for transportation applications. Avient Corporation brings long fiber technology with pultruded glass and carbon fiber-reinforced thermoplastics, targeting metal replacement and structural components where integration and mechanical performance are critical. RTP Company contributes engineered LFT pellet portfolios, including high glass fiber concentrates for demanding automotive specifications, reinforcing a capability set centered on specification compliance and processing reliability.
Short Fiber Reinforced Thermoplastic Composite Market
Daicel Corporation's LFT offering targets rigid, impact-resistant components for automotive and industrial uses, aligning with applications where toughness and dimensional stability matter. In Asia, KINGFA Science & Technology and Xiamen LFT Composite Plastic are expanding the regional supply base, with the latter emphasizing long glass and carbon fiber polymer pellets for aerospace, drones, and high-rigidity structural applications, reflecting an appetite for higher-performance niches beyond mainstream automotive volumes. TechnoCompound GmbH provides long glass fiber granules and custom LFT compounds for automotive and industrial structural parts, underscoring a customization-oriented model that suits regionally concentrated OEM relationships. BGF Group and Lotte Chemical Corporation support the market with reinforced thermoplastic offerings focused on impact strength, processability, and advanced functional materials, while Borealis AG contributes LFT compounds for high-performance automotive and technical applications with long fiber reinforcements.
Recent developments illustrate how competition is being shaped by both product expansion and collaboration. In 2025, one major player introduced a platform for manufacturing large-scale high-performance thermoplastic parts, signaling a push toward throughput and part size optimization. Another expansion added enhanced carbon fiber-reinforced grades to an existing LFT portfolio, reflecting continued investment in stiffness-critical segments. Collaborations with leading automotive manufacturers are also accelerating advanced thermoplastic composite solutions for lightweight structures, demonstrating that co-development and customer proximity are becoming as important as material formulation. At the same time, new advanced long glass fiber-reinforced thermoplastics have been introduced for EV and structural applications, reinforcing the broader industry pivot toward electrification-driven performance requirements.
Market structure appears likely to evolve along two parallel tracks. On one hand, consolidation pressure will persist among players seeking scale in compounding, fiber integration, and regional service coverage. On the other, differentiation will intensify around application-specific formulations, processing support, and regional localization. New entrants that can demonstrate rapid qualification, cost-competitive reinforcement strategies, or access to specialized end-markets may carve out defensible positions even in a concentrated landscape. For incumbents, the key is to balance scale advantages with the flexibility to serve customer-specific performance and sourcing requirements.
Forward Outlook: Trends Shaping the Next Three to Five Years
Broadening Beyond Automotive into Multi-Industry Structural Use
While automotive remains the leading demand engine, LFT adoption is expected to deepen across electrical/electronics, industrial equipment, and specialized performance segments. The common thread is the need for components that combine strength, impact resistance, and processing practicality. Over the next several years, this broadening should support more diversified revenue bases for compounders that can transfer automotive-grade expertise into adjacent markets. Commercial opportunity lies in building application-specific value propositions that reduce customer risk and accelerate qualification, rather than competing solely on price per kilogram.
Material Mix Optimization in Response to Fiber Pricing Dynamics
The cost gap between glass and carbon fiber, combined with ongoing price softness in certain carbon fiber markets, will likely encourage more deliberate material mix optimization. Engineers may select carbon fiber for stiffness-critical load paths while relying on glass fiber for broader structural parts where cost and processability dominate. This creates an opportunity for compounders to offer performance-tiered portfolios that help customers balance mechanical targets with total part cost. The risk is that persistent overcapacity or trade friction could compress margins if pricing expectations become unstable, making scenario planning and formulation agility essential.
Long Glass Fiber Reinforced Polypropylene Market
Localization, Regional Qualification, and Supply Chain Resilience
Trade policy and logistics volatility are expected to continue influencing LFT supply chains, with regional content considerations and qualification pathways gaining importance. Companies that invest in localized compounding, regional technical support, and flexible sourcing for reinforcements will be better positioned to meet OEM expectations for resilience and responsiveness. At the same time, qualification speed will remain a competitive differentiator; organizations that can co-develop solutions and support downstream processing will capture share more rapidly than those relying solely on material supply. A potential uncertainty is that policy shifts or fiber supply disruptions could alter regional cost advantages quickly, requiring continuous reassessment of sourcing and production footprints.
Strategic Implications for Decision-Makers
For Manufacturers and Compounders
- Build application-engineered portfolios rather than generic grade lists. Customers in structural and EV-related applications value processing support, validation data, and part performance predictability as much as raw material properties. Aligning product tiers with clear use cases can shorten qualification and broaden adoption.
- Design supply chains for flexibility. Given fiber price volatility and trade-related sourcing changes, maintain optionality in reinforcement sourcing and consider regional compounding capacity where service expectations or content requirements are shifting.
For Investors
- Focus on margin durability, not only top-line growth. Market expansion is strong, but profitability will increasingly depend on formulation differentiation, customer lock-in through co-development, and the ability to manage input cost swings. Evaluate whether target companies have defensible technical positions and regional service capabilities.
- Watch for consolidation and niche specialization as dual paths. Scale players may pursue integration and geographic coverage, while specialized entrants may capture higher-value segments in aerospace, drones, or high-rigidity structural applications. Both can create value if execution aligns with end-market needs.
For Procurement and Sourcing Leaders
- Treat fiber mix and trade exposure as strategic levers. Evaluate total part cost and performance trade-offs across glass and carbon fiber options, and incorporate regional sourcing and tariff scenarios into long-term agreements to reduce disruption risk.
- Prioritize supplier partnerships that shorten qualification cycles. In structural applications, the cost of delay often exceeds the cost of material. Suppliers that provide robust testing support, processing guidance, and predictable supply can improve program timing and reduce downstream risk.
The LFT market is moving from a performance niche to a broader structural material platform, but the path to capture value is becoming more complex. Success will depend on how effectively organizations align formulation strategy, regional supply logic, and customer co-development. For leaders seeking deeper segmentation data, regional demand breakdowns, and tailored competitive assessments, a comprehensive research report can provide the detail needed to translate these trends into concrete operating and investment decisions.
For detailed analysis of this topic, please visit the official page: Long Fiber Thermoplastics (LFT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com