

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Soldering Robot Market 2026: Why 6.98% CAGR and Electronics Assembly Redefine Growth

Strategic Trends and Commercial Opportunities in the Soldering Robot Market
Market Landscape and Core Challenges
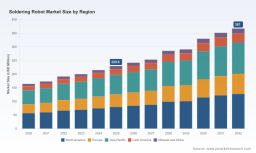
The soldering robot market has transitioned from a niche automation segment to a structural component of modern electronics and industrial manufacturing. Revenue has expanded consistently from approximately 164 million USD in 2020 to an estimated 229.6 million USD in 2025, with a projected trajectory reaching 367 million USD by 2032. This growth reflects a compound annual growth rate of roughly 6.98% across the 2026 to 2032 forecast window. The pace is steady rather than explosive, signaling an industry that is maturing while still expanding its addressable base through broader adoption, newer applications, and incremental automation penetration in legacy processes.
A defining characteristic of the market is its moderate concentration. The top three players account for a combined share near 35% of revenue, while the top five approach just under half. This structure suggests a landscape where established leaders hold meaningful positioning but do not dominate to the point of blocking innovation or new entry. Fragmentation below the top tier leaves room for specialized systems, regional integrators, and application-focused solutions to carve out sustainable niches. For decision makers, that means no single vendor dictates procurement outcomes, and competitive differentiation often comes from integration capability, service depth, and application fit rather than raw hardware cost alone.
Three challenges are reshaping how manufacturers and investors should interpret this growth. First, the labor equation is shifting from a cost concern to a capability concern. Factory floors in several regions face skilled shortages, and the transfer of soldering expertise from experienced workers to newer staff has become harder as turnover accelerates and shop-floor practices become less standardized. Automation is increasingly evaluated not only to reduce throughput variance but to preserve process knowledge in a repeatable form. Second, material volatility is compressing planning confidence. Solder paste and alloy inputs, where tin dominates the composition, have experienced price instability that ripples into production scheduling, quotation accuracy, and margin forecasting. This makes deterministic automation investments more attractive, yet also raises the stakes around integration timing and total cost models. Third, the adoption curve is uneven across applications and regions, creating pockets of rapid deployment alongside slower-moving segments where change management, validation, and qualification cycles delay procurement.
The market is therefore not simply expanding; it is recalibrating around reliability, traceability, and process continuity. That shift changes the buying criteria. Equipment is being evaluated less as a standalone efficiency tool and more as part of a broader quality and documentation architecture, especially where external standards and customer expectations increasingly require demonstrable process control.
Key Drivers Shaping the Market
Several interlocking forces are pulling the market forward. The most visible is technology innovation in precision, flexibility, and system intelligence. Selective soldering platforms continue to gain relevance where board complexity and mixed technology assemblies make traditional batch methods less suitable. Desktop and tabletop systems with refined motion control, Z-axis and angular adjustments, and integrated vision are expanding the feasible use cases beyond high-volume lines to lower-volume, higher-mix production. Laser-assisted and induction-based variants add speed and localized heat control, reducing thermal stress on sensitive components and enabling tighter process windows. These capabilities matter because they lower the barrier to automation in environments that were previously considered too variable or too small for conventional soldering lines.
A second driver is the alignment between automation and regulatory or standards-driven expectations. Manufacturing footprints that must demonstrate consistent solder appearance, documentation, and traceability are increasingly viewing robotic soldering as an enabler rather than a luxury. External adoption of recognized soldering appearance standards by major customers illustrates how expectations can propagate through supply chains. When influential buyers formalize acceptance criteria, tier suppliers must respond, and automation becomes a practical route to meet those requirements with less dependence on individual operator skill. The value here is not only compliance; it is the ability to reduce subjective inspection outcomes and make process results more predictable across shifts and sites.
Demand-side behavior is also changing the equation. Electronics assembly remains the largest application context, but interest is broadening into automotive, aerospace, and medical devices, where the tolerance for variation is lower and the cost of rework is higher. These segments do not necessarily require the highest volumes; they require controlled repeatability, material traceability, and documented process integrity. As product portfolios become more diversified and as manufacturers face pressures to shorten changeovers while maintaining quality, the appeal of programmable soldering systems increases. In parallel, consumer and industrial product cycles continue to reward faster ramp-up and more flexible reconfigurability, which favors equipment that can be reprogrammed and redeployed with less downtime.
The supply-side dynamic rounds out the driver set. Automation is increasingly weighed against labor availability and continuity risk, especially where aging workforces, training gaps, or regional skill transfer challenges make manual soldering less sustainable over the medium term. At the same time, raw material fluctuations add a subtler but real pressure: when input costs are unstable, manufacturers place greater value on equipment that minimizes waste, reduces rework, and supports consistent deposition and profile control. This does not eliminate the importance of cost, but it tilts the evaluation toward total cost of ownership, process stability, and the ability to maintain throughput when skilled labor is scarce.
The combined effect is that technology, standards, demand complexity, and labor economics are reinforcing one another. The strongest growth opportunities are emerging where these forces converge: applications that need repeatability, documentation, flexible volume handling, and lower dependence on hard-to-sustain manual expertise.
Competitive Landscape and Leading Strategies
The competitive set blends original equipment manufacturers with integrators and distributors, and the strategic positioning varies along the line from high-speed mass production to precision desktop work. Japan Unix has built a presence around desktop and laser soldering robots, with product families oriented to high-speed electronics production. Its recent public-facing activity emphasizes hardware refresh and working-environment considerations, such as fume extraction, signaling an interest in making automated soldering practical for floor-level deployment where operator safety and workspace management matter. This suggests a strategy centered on broadening the practical envelope of automation, not only improving throughput.
Apollo Seiko emphasizes selective soldering with specialized heating approaches, including induction-based wave systems and precision automated platforms. That combination points to a different strategic angle: addressing applications where heat control and selective deposition are more important than brute throughput. In markets where boards mix through-hole and surface-mount components, or where thermal management around sensitive elements is critical, this type of differentiation can become a key purchase factor.
ELMOTEC has positioned around desktop and tabletop robotic soldering with integrated vision and traceability. That positioning is strategically telling because it links soldering execution with data capture and process documentation. In segments where traceability is tied to customer qualification or internal quality governance, this integration can be more valuable than marginal speed gains. It reflects a broader shift in which soldering equipment is increasingly expected to contribute to the record of how a joint was made, not merely the joint itself.
Selective Soldering Equipment Market
Fancort operates partly through distribution and integration services, focusing on selective soldering and tinning automation. Its model highlights an important part of the market: many buyers do not want a standalone machine; they want a validated solution integrated into existing lines with support for setup, training, and process adjustment. In fragmented markets, the integrator value proposition can be as influential as the hardware brand, especially for mid-size manufacturers that need a practical path from pilot to production.
I.C.T. represents a more automation-oriented entry in the desktop space with control features designed for SMT-adjacent production environments. This signals continued diversification at the lower-cost and higher-accessibility end of the market, where refinements in control axes and ease of deployment can open opportunities in smaller lots and more varied assemblies. Taiyo Electric rounds out the field with automatic soldering systems and dedicated robots for electronics assembly, reinforcing the presence of established electronics tooling players in this segment.
Wave Soldering Machine Market
The strategic patterns among these players point to several differentiation paths. One is application specialization, where vendors tailor platforms to selective, wave, reflow, or assisted soldering needs rather than competing on a single universal proposition. Another is integration of vision, traceability, and documentation, which becomes more valuable as expectations for process transparency rise. A third is service and integration depth, where distribution and deployment support help reduce the operational burden of automation. A fourth is usability and floor-level practicality, including safety accessories and ease of programming, which broadens adoption beyond highly specialized engineering teams.
Market evolution appears to be moving along two tracks simultaneously. On one track, leaders are deepening their propositions around precision, documentation, and line integration to defend and expand share in demanding applications. On the other, new and lower-cost entrants continue to expand accessibility, particularly in desktop and small-batch settings. This dual dynamic suggests that the market will remain plural rather than consolidating quickly into a single dominance pattern. Consolidation may occur more in the form of regional strength and service networks than in a handful of global platform monopolies. Buyers should expect continued choice, with differentiation increasingly determined by how well a vendor aligns with a specific application, volume profile, and documentation requirement.
Future Trends and Commercial Opportunities
The next three to five years are likely to be shaped by three trends, each carrying a distinct commercial implication. The first is broader adoption beyond high-volume electronics into higher-mix, higher-stakes applications. As platforms become easier to program and reconfigure, the opportunity set expands to manufacturers who need repeatable soldering without committing to large fixed lines. This favors vendors and integrators who can package flexible automation with quick changeover support and practical training. For buyers, the commercial opportunity lies in lowering the automation threshold for lower-volume runs while improving consistency across product family changes.
The second trend is the deepening connection between soldering execution and process data. Vision-assisted inspection, traceability capture, and standardized documentation are becoming part of the equipment value proposition, not merely add-ons. As customer expectations and internal quality governance increasingly require evidence of process control, systems that natively support traceability should command stronger positioning in regulated or qualification-driven segments. The commercial opportunity is in solutions that reduce the burden of documentation and make quality evidence a byproduct of normal operation, rather than a separate administrative effort.
The third trend is the continued influence of labor structure and material volatility on procurement strategy. Where skilled labor is hard to sustain, the case for automation strengthens on continuity grounds, not just unit cost. Where solder material prices remain volatile, manufacturers gain from deposition consistency, reduced rework, and better process control that can partially offset uncertainty. This creates a more defensive case for adoption that can be just as compelling as the efficiency case, especially in regions or segments where workforce stability is a real constraint. The commercial opportunity here is to frame automation investments around resilience and process control, aligning procurement with medium-term operational risk reduction.
These trends intersect with risks. One risk is material-driven cost pressure affecting both equipment payback calculations and production planning, which can slow decisions if organizations lack clear total-cost models. Another is the potential for uneven standards adoption across supply chains, where expectations differ by customer and region, making qualification timelines less predictable. A third risk is integration complexity: the benefits of automation are easier to capture when deployment, programming, and maintenance are well handled, and weaker integration can erode the advantages that motivated the investment. These uncertainties do not negate the direction of travel, but they raise the importance of selection discipline and implementation readiness.
PW Consulting
For organizations looking for opportunity, the most actionable space is where flexibility, traceability, and labor continuity align. That includes applications with mixed assembly formats, tighter quality expectations, variable lot sizes, and skilled-labor exposure. Vendors and investors who can connect hardware capability to these operational outcomes are likely to find stronger traction than those competing primarily on headline speed or price alone.
Strategic Actions for Decision Makers
For manufacturers evaluating soldering automation, the priority is to define the operational problem before the equipment category. If the real driver is quality consistency and traceability, then selection should emphasize vision, documentation, and process control rather than throughput in isolation. If the driver is labor continuity and repeatability across shifts, then usability, programming simplicity, and changeover efficiency become central. If the driver is mixed-technology complexity, then selective or induction-based approaches may matter more than generic automation. A clear problem definition reduces the risk of buying a capable system that does not map to the constraints that matter most on the floor.
For investors and strategic planners, the market warrants attention as a steady-growth segment with differentiated value pools rather than a homogeneous commodity play. The moderate concentration structure suggests room for specialized leaders to outperform in their chosen niches, while continued entry at the accessible end of the market supports broader adoption. Monitoring which vendors are strengthening traceability, integration services, and application-specific platforms can provide early signals about where durable positioning is being built. It is also worth tracking material-price dynamics and labor availability as context for adoption timing, since these factors shape both demand urgency and payback confidence.
For procurement and engineering leads, the most valuable next step is to align pilot selection with the evidence requirements of internal quality and external customers. Where documentation, traceability, and consistent appearance are part of the acceptance criteria, the evaluation should include how the system supports those outcomes in day-to-day operation. Where deployment speed and flexibility matter, the emphasis should be on changeover burden, training needs, and integration with existing line architecture. In both cases, the decision is strengthened by access to detailed segment data, vendor-specific positioning, and application-level benchmarks that make it possible to compare solutions against real operational constraints rather than generic specifications.
Detailed research covering regional dynamics, type-based segmentation, application-specific demand, and company-level strategic positioning can help narrow these choices with greater precision. The broader trend is clear, but the actionable details vary widely by application, volume profile, and compliance context. Targeted intelligence is what turns a market direction into a practical procurement or investment decision.
For detailed analysis of this topic, please visit the official page: Soldering Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com