

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Glass Wafers Market: 9.8% CAGR Trajectory and the PC, Semiconductor Demand Shifts Reshaping 2032

Strategic Shifts and Commercial Opportunities in the Glass Wafers Market
The global glass wafers market is entering a period of structural expansion, driven by converging demands across semiconductor packaging, photovoltaic manufacturing, and precision optics. Recent market trajectories show a total revenue pool growing from approximately $284.87 million in 2020 to $454.63 million in 2025, reflecting sustained capital deployment and technology adoption cycles. Forward projections indicate the market will reach $831.08 million by 2032, anchored by a compound annual growth rate of 9.8 percent. This growth trajectory is not merely incremental; it reflects a recalibration of material choices in high-performance electronics and energy systems, where glass substrates are increasingly displacing traditional alternatives to meet stricter thermal, optical, and dimensional requirements.
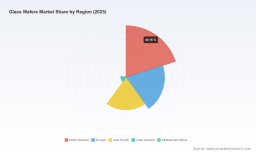
Regional revenue distribution points to a concentrated but shifting global footprint. North America and Europe together account for a substantial share of current demand, while Asia Pacific continues to expand its manufacturing and downstream application base. This geographic pattern is closely tied to localized semiconductor packaging hubs, renewable energy deployment rates, and the clustering of precision optics manufacturers. At the same time, market concentration remains moderate, with the top three players holding roughly 42.3 percent of revenue and the top five approaching 58.1 percent. Such a structure suggests a market that is neither fully commoditized nor monopolized, leaving room for differentiated positioning, regional specialization, and targeted partnerships.
PW Consulting
Several inflection points are reshaping how market participants plan capacity, product portfolios, and customer engagements. First, the transition toward advanced packaging and wafer-level integration is altering substrate specifications, pushing suppliers to deliver thinner, flatter, and more dimensionally stable glass wafers with tighter tolerance bands. Second, the simultaneous expansion of photovoltaic throughput and semiconductor content is creating competing pulls on glass material grades, requiring clearer segmentation of production lines and supply commitments. Third, the industry is navigating a phase where raw material availability, precision processing costs, and qualification cycles increasingly determine margin outcomes, making operational discipline as important as product innovation. These dynamics are setting the stage for a more nuanced competitive environment in which scale alone will not guarantee leadership.
Key Demand Drivers Reshaping the Market
Technological Innovation and Material Performance
The most persistent driver of demand is the ongoing push for higher performance in semiconductor packaging and micro-optics. Glass wafers offer advantages in thermal expansion behavior, surface quality, and electrical isolation, which makes them attractive for applications requiring precise alignment, reduced signal loss, and improved mechanical stability. As devices become more compact and integration levels rise, the tolerance for substrate variability narrows, favoring suppliers that can consistently deliver refined surface finishes, controlled thickness, and reliable batch-to-batch uniformity. Innovation in thinning processes, polishing techniques, and defect control is thereby becoming a core differentiator rather than a supporting capability.
Technological progress is also expanding the boundaries of where glass wafers can be used. In micro-electromechanical systems and micro-optical assemblies, specialized glass formats enable smaller form factors and more complex optical paths. In semiconductor packaging, increasing interest in through-glass interconnect approaches and wafer-level assembly is stimulating demand for substrates that can support fine feature formation while maintaining structural integrity during processing. These developments are not isolated product trends; they represent a broader shift toward materials that can support denser integration without compromising reliability.
Policy and Regulatory Environment
Policy priorities are reinforcing demand in select end markets. Semiconductor sovereignty initiatives, domestic packaging capacity investments, and incentives for advanced manufacturing are encouraging both regional supply and localized substrate sourcing. In parallel, energy transition policies continue to support photovoltaic expansion, which indirectly strengthens demand for glass materials used in related manufacturing processes and equipment. Regulatory emphasis on supply chain resilience and traceability is also raising the bar for qualification, documentation, and quality assurance, particularly in applications where downstream device performance depends heavily on substrate consistency.
This regulatory backdrop favors organizations that can demonstrate stable compliance practices, transparent sourcing, and the ability to support customer validation processes. In many cases, the pace of policy-driven investment creates temporary demand spikes, but the more lasting effect is the establishment of higher baseline expectations for quality, accountability, and regional responsiveness. Suppliers that treat regulatory alignment as a strategic capability rather than an administrative task are better positioned to retain customers through qualification cycles and procurement reviews.
Demand-Side Behavior and Application Mix
Customer behavior is increasingly shaped by performance trade-offs rather than price alone. Semiconductor OEMs, packaging houses, and optics manufacturers are evaluating glass wafers based on total system outcomes, including yield, reliability, thermal management, and integration complexity. This shift encourages longer qualification conversations and deeper technical cooperation, especially when a substrate choice can influence downstream packaging yield or optical alignment precision. As a result, the purchasing process is becoming more consultative, with engineering teams playing a larger role in material selection.
Silicon Wafer Market
Application mix is also diversifying in ways that create both opportunity and planning complexity. Semiconductor-related demand remains the largest contributor to market revenue, reflecting the centrality of glass wafers in packaging and related high-precision processes. Photovoltaic applications represent a meaningful secondary channel, supported by continued production scale-up and equipment ecosystem growth. Optics and other specialized uses add further nuance, often requiring customized specifications and smaller, more flexible production runs. The practical implication is that successful market participants must balance volume-oriented process stability with the agility to serve technically demanding niche requirements.
Supply Chain and Cost Structure Dynamics
Cost structures in the glass wafers market are influenced by the interplay of precision processing, equipment utilization, and material-grade differentiation. Producing wafers that meet stringent flatness, subsurface quality, and dimensional requirements typically demands controlled manufacturing environments and well-managed process parameters. As specifications tighten, the marginal cost of quality can rise, making yield management and process reproducibility critical to commercial performance. Suppliers that invest in process control, inspection capability, and consistent operator expertise can convert technical reliability into pricing resilience.
Supply chain resilience is another increasingly important factor. Customers in semiconductor and optics ecosystems often prioritize predictable delivery, validated quality records, and the ability to support rapid issue resolution. Fluctuations in input availability, logistics constraints, or capacity bottlenecks can therefore carry outsized consequences for customer planning. This environment rewards manufacturers that maintain disciplined inventory approaches, clear lead-time communication, and flexible capacity allocation strategies, particularly when serving customers with tightly sequenced production schedules.
Competitive Landscape and Strategic Positioning
The competitive field includes a mix of established specialty glass manufacturers, engineering-driven processors, and packaging-focused suppliers. SCHOTT AG remains closely associated with specialty glass wafers for MEMS, micro-optics, and semiconductor packaging, leveraging broad technical glass expertise and application breadth. Corning Incorporated has emphasized semiconductor glass wafers, including carrier glass concepts for through-glass interconnect and wafer-level packaging applications, aligning its portfolio with advanced packaging trends. AGC Inc. and Nippon Electric Glass Co., Ltd. both operate from strong positions in glass substrates and technical wafers, serving semiconductor packaging, electronic mounting, MEMS, and micro-optical applications with specialized process knowledge.
In the precision processing segment, companies such as Plan Optik AG, Swift Glass, Sydor Optics, Bullen, Coresix Precision Glass, Inc., and Samtec, Inc. illustrate the importance of downstream fabrication capability. Their profiles reflect a focus on polished glass wafers, fused silica and borosilicate options, and substrates tailored for semiconductor interconnect and wafer-level packaging. This segment matters because many end customers evaluate not only the base glass material but also the readiness of the wafer for integration, including surface quality, dimensional consistency, and the supplier's ability to support specialized processing requirements.
Strategic differentiation in this market tends to emerge along several axes. Some players compete on material breadth and application coverage, seeking to address multiple end markets with a shared technical platform. Others concentrate on process precision, qualification support, and close customer collaboration, building advantage through reliability and engineering responsiveness. A third orientation emphasizes regional proximity and service agility, which can be decisive when customers require faster turnaround, localized technical support, or closer coordination with nearby packaging and assembly operations. The most effective positioning often combines elements of these approaches rather than relying on a single strength.
Market structure appears likely to evolve through selective consolidation and targeted specialization rather than uniform consolidation. Larger suppliers may pursue broader portfolios and global reach, while smaller or regionally focused processors can thrive by serving high-specification niches that require flexible production, faster iteration, or specialized surface and thickness control. New entrants typically face meaningful barriers in qualification, consistency, and customer trust, but they may gain traction where existing supply is constrained by technical demands, lead times, or capacity limitations. In this environment, competitive advantage will increasingly depend on how well a company can match product capability with customer integration needs and supply reliability.
Semiconductor Silicon Wafer Market
Future Trends and Commercial Implications
Trend One: Higher-Integration Packaging Will Raise Substrate Expectations
Over the next three to five years, advanced packaging and wafer-level integration are expected to place continued pressure on substrate specifications. As interconnect density rises and assembly architectures become more complex, glass wafers will need to support finer processing tolerances, improved surface consistency, and stronger thermal and mechanical stability. This trend creates commercial opportunity for suppliers that can offer not only suitable base materials but also repeatable processing quality and validation support. Companies that can reduce variability and accelerate qualification are likely to secure more durable customer relationships in packaging-intensive segments.
Trend Two: Application Diversification Will Reward Portfolio Flexibility
The market is likely to see continued diversification across semiconductor, photovoltaic, and optical applications, with each channel imposing distinct specification priorities and volume profiles. Semiconductor demand will remain central, but photovoltaic and optics channels can provide meaningful growth and diversification, especially where regional manufacturing expands or where specialized optical and precision requirements create differentiated demand. Suppliers that can manage multiple product grades, balance capacity between high-volume and customized work, and adapt to shifting demand rhythms will be better positioned to capture value across cycles. This flexibility also helps mitigate exposure to any single application's slowdown or qualification delay.
Trend Three: Qualification, Traceability, and Service Responsiveness Will Become More Decisive
As downstream industries place greater emphasis on reliability, documentation, and supply continuity, commercial success will increasingly depend on the quality of customer-facing capabilities. Technical sales, validation support, quality records, and lead-time transparency are becoming part of the competitive equation. Suppliers that can communicate clearly, resolve issues quickly, and support customer qualification without disrupting production schedules will differentiate themselves in a market where product specs alone are often insufficient. The risk side of this trend is that any lapse in consistency, documentation, or responsiveness can have disproportionate consequences, especially for customers operating with tight integration schedules and limited buffer capacity.
These trends point to a market where commercial opportunity is closely tied to execution quality. Growth is not simply a function of expanding end-market demand; it also depends on whether suppliers can meet more demanding specifications, support diverse applications, and deliver dependable service. Organizations that align product development, manufacturing discipline, and customer engagement with these expectations are more likely to convert market growth into durable share and margin improvement.
Strategic Actions for Decision-Makers
For Manufacturers and Material Suppliers
- Prioritize process control and reproducibility as strategic assets. In a market where tighter tolerances and higher consistency increasingly determine customer choice, yield stability and inspection rigor can translate directly into pricing leverage and retention.
- Align product portfolios with the specification profiles of the most promising applications. This may mean separating high-volume standard grades from higher-spec.custom lines, while ensuring capacity can flex without compromising quality in either segment.
- Build qualification support and technical collaboration into the commercial model. Engineering engagement, transparent quality documentation, and responsive issue resolution can shorten customer decision cycles and strengthen long-term partnerships.
For Investors and Corporate Development Teams
- Focus on companies with demonstrated ability to serve precision applications, not just broad product lists. In this market, differentiation often comes from process capability, repeatability, and the credibility to pass customer validation.
- Evaluate exposure to application mix and regional demand patterns. Growth prospects can vary significantly depending on how closely a company's capabilities align with localized packaging capacity, photovoltaic expansion, or specialized optics demand.
- Watch for consolidation opportunities where scale, regional reach, or technical complementarity can strengthen a supplier's position, but avoid overpaying for volume without evidence of specification leadership or customer loyalty.
For Procurement and Supply Chain Leaders
- Treat substrate selection as a system-level decision. The best glass wafer choice may depend on downstream yield, thermal behavior, alignment precision, and processing compatibility rather than unit price alone.
- Require clear qualification roadmaps, quality documentation, and contingency planning from suppliers. Predictable delivery and transparent process control are especially valuable when production schedules are tightly linked to device assembly or equipment throughput.
- Diversify strategically where specifications allow, balancing primary suppliers with backup options that can meet critical tolerance and surface requirements, reducing exposure to single-source risk without compromising quality.
Glass wafers are moving from a specialty input to a strategically important enabler in several high-value technology chains. The combination of advanced packaging needs, energy-related manufacturing expansion, and increasing expectations for precision and reliability is creating a market where technical execution and commercial discipline both matter. For organizations operating in or adjacent to this space, the most valuable next step is to map the specific specification, qualification, and supply requirements that will shape demand in the coming years, then align product strategy and customer engagement accordingly. More granular segment data, company-level benchmarking, and customized scenario analysis can help decision-makers convert these market-level insights into concrete plans. The full research report provides deeper breakdowns across regions, material types, applications, and competitive profiles, along with tailored guidance for different strategic objectives.
For detailed analysis of this topic, please visit the official page: Glass Wafers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com