

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
The Hidden Drivers Behind the Central Venous Catheters Market 6.8% CAGR Growth

The Central Venous Catheter Market: Strategic Trends and Commercial Opportunities in a Maturing Landscape
The global market for central venous catheters (CVCs) has entered a phase of steady, structurally driven growth. With a base-year valuation of USD 215.0 million in 2025 and a forecasted compound annual growth rate of 6.8 percent extending through 2032, the segment is projected to reach USD 341.17 million by the end of the forecast period. The trajectory reflects a decade of consistent expansion from a 2020 baseline of USD 163.15 million, underscoring the essential role CVCs play in critical care, oncology, and interventional procedures. Yet beneath the headline figures lies a more nuanced reality: the market is no longer growing simply because demand exists. Growth is increasingly shaped by device innovation, regulatory tightening, supply chain realignment, and evolving inpatient care pathways. For manufacturers, investors, and hospital procurement teams, the next several years will reward those who can align product strategy with clinical economics and operational resilience rather than relying on incremental volume gains alone.
Market Snapshot and Core Dynamics
The CVC market’s expansion is anchored in consistent utilization across acute and post-acute settings. Revenue growth over the 2020–2025 period averaged roughly 5.8 percent annually, accelerating into the 6.8 percent CAGR projected for 2026–2032 as capacity constraints ease and higher-value product configurations gain clinical preference. The market structure is moderately concentrated: three leading firms account for approximately 35 percent of total revenue, while the top five collectively represent about 52 percent. This concentration signals a mature competitive arena where scale, regulatory credibility, and clinical integration differentiate winners, yet it also leaves meaningful share for specialized players who can compete on design advantage, regional agility, or insertion-technology differentiation.
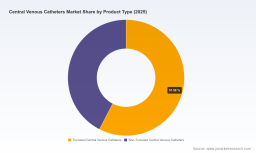
The product mix continues to reflect the balance between established short-term use and longer-duration access needs. Tunneled CVCs command a larger revenue footprint, reflecting their role in therapies requiring durable vascular access, while non-tunneled alternatives remain central to emergency, surgical, and short-stayCritical care workflows. By design, double-lumen configurations capture the largest share of current demand, driven by the need to support simultaneous infusion, monitoring, and blood draw capabilities without multiplying puncture sites. Single-lumen devices retain relevance for focused therapy protocols, and multiple-lumen options serve specialized interventions where channel separation reduces cross-contamination risk and procedural complexity.
Geographically, the market spans mature healthcare systems with entrenched procurement cycles and emerging regions where capacity growth is reshaping utilization patterns. North America holds the largest revenue baseline, followed by Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than treating regional shares as static figures, decision-makers should interpret them as indicators of differing clinical adoption curves, reimbursement maturity, and supply-chain localization efforts. The same product architecture that performs well in a high-volume academic center may require material adaptation in settings where staffing models, sterilization infrastructure, or procurement fragmentation constrain uptake.
Medical Catheters Market
Key Challenges and Inflection Points
Despite steady growth, the CVC market faces several structural friction points that will shape competitive outcomes over the coming years.
Regulatory and quality expectations are intensifying. Standards development is moving more explicitly toward defined performance thresholds rather than broad safety principles. Recent guidance under the prEN ISO 10555-3 (2026) framework, for example, introduces testing requirements for sterile, single-use central venous catheters, including peak tensile force criteria. This kind of specification raises the bar for design validation and manufacturing consistency, particularly for smaller producers or new entrants who must demonstrate compliance without the benefit of long-standing procurement relationships. For all companies, the operational implication is clear: regulatory readiness now influences both speed to market and tendering credibility.
PW Consulting
Quality events continue to disrupt procurement confidence. Even established product lines are not immune to process or supply-chain disruptions. A Class 2 recall of an Arrowg+ard Blue Plus Four-Lumen CVC Kit initiated in March 2026 due to supplier-notice-related issues illustrates how upstream dependencies can trigger downstream market effects, including formulary reassessment and temporary sourcing shifts. In a moderately concentrated market, such events can create short-term opportunities for alternative suppliers, but they also heighten buyer sensitivity to traceability, vendor oversight, and contingency planning. Buyers increasingly treat quality records and supplier transparency as procurement criteria rather than back-office checks.
Clinical preferences and cost pressure are pulling in different directions. Hospitals are under sustained pressure to reduce device-related complications, shorten length of stay, and streamline supply costs. That combination pushes demand toward catheters that reduce insertion failures, support preferred site access, and integrate cleanly with securement and disinfection workflows. At the same time, procurement teams remain highly attentive to price stability and catalog standardization. The tension between clinical value and total cost of ownership is not new, but it is becoming more consequential as value-analysis committees weigh device performance alongside labor efficiency and infection-control outcomes.
Key Drivers Reshaping the Market
The CVC market is being shaped by a set of overlapping drivers that extend beyond simple volume growth. Understanding these forces helps clarify where profitable differentiation is possible.
Innovation in insertion and access technology is changing how catheters are deployed. One of the most visible recent developments is the commercial launch of the CentroVena One Insertion System for acute central venous catheters, following its FDA 510(k) clearance in April 2025 and subsequent market introduction in 2026. Device designs that simplify placement, improve first-attempt success, and reduce reliance on operator-dependent technique are increasingly relevant in busy care environments where procedural efficiency and consistency matter. Even when the catheter itself is the core product, the insertion system can become a meaningful differentiator by linking device performance to workflow reliability. This shift encourages manufacturers to think beyond the catheter as an isolated component and toward the access episode as a whole.
Regulatory standardization is pushing quality upstream. The adoption of more explicit testing and performance criteria for sterile, single-use catheters is influencing product development cycles and supplier selection. Standards that define peak tensile force and other mechanical performance measures reduce ambiguity in validation but also raise the baseline for what procurement groups expect from approved vendors. Companies that invest early in standardized testing, design controls, and documented quality systems are better positioned to navigate audits, tenders, and international market entry. For buyers, this environment supports more apples-to-apples evaluation; for suppliers, it raises the cost of compliance but also creates a barrier that can protect established players with mature quality infrastructure.
Demand-side behavior is evolving as care pathways shift. Critical care utilization, oncology infusion needs, and interventional procedures continue to anchor CVC demand, but the context around those uses is changing. Hospitals are increasingly attentive to catheter-related complications, line longevity, and the downstream costs of premature failure or replacement. That has elevated interest in antimicrobial-coated lines, securement technologies, and catheters designed to reduce manipulation once placed. At the same time, clinical teams are looking for devices that fit into existing protocols without creating additional training burden. The net effect is a market where clinical utility, reduction of complications, and ease of use are becoming more important than device attributes considered in isolation.
Cost structures and supply chain expectations are being recalibrated. Following several years of volatility in component sourcing and logistics, many manufacturers and buyers are rethinking where value is captured in the CVC supply chain. Localization, dual sourcing, and tighter supplier oversight are now part of the conversation for both large and mid-tier players. Cost pressure does not simply mean lower pricing; it increasingly means predictable availability, fewer line disruptions, and stronger documentation around product integrity. Suppliers that can demonstrate reliable lead times, clear quality traceability, and contingency readiness are gaining leverage in procurement discussions, especially where previous disruptions have left hospital supply chains wary of single-point dependencies.
Competitive Landscape and Leading Strategies
The competitive field includes large multinational suppliers with broad vascular access portfolios as well as focused companies that compete through specialized design, regional presence, or technology-led insertion solutions. The market’s moderate concentration means that incumbents benefit from scale and established formulary positions, but it also leaves room for challengers who can win on specific clinical or operational advantages.
Leadership through portfolio breadth and regulatory credibility. Becton Dickinson and Company continues to position itself strongly in acute and short-term CVC use, supported by the recent commercialization of the CentroVena One Insertion System following FDA clearance. Its strength lies in combining a well-known catheter platform with an insertion approach designed for acute care workflows, along with pressure-injectable and standard CVC kits. That combination gives BD a credible narrative around both device performance and procedural efficiency. For a large diversified supplier, the strategic advantage is not only product breadth but also the ability to integrate CVC offerings into wider hospital purchasing relationships and clinical programs.
Critical-care focus and antimicrobial differentiation. Teleflex draws on its Arrow-branded vascular access portfolio, including pressure-injectable models and antimicrobial-coated lines relevant to critical care. This positioning supports hospitals seeking to address infection risk and line durability in high-acuity settings. Teleflex’s strategy illustrates how a strong brand heritage in vascular access can support premium positioning when paired with features aligned to specific clinical concerns. In a market where complication avoidance is a growing purchasing consideration, antimicrobial and securement-related capabilities can form the center of a differentiated value proposition.
Regional integration and vascular therapy system thinking. B. Braun, Vygon, Terumo, Nipro, and others emphasize the role of CVCs within broader vascular therapy and infusion ecosystems. For these players, competitive advantage often comes from combining catheters with compatible administration sets, infusion components, and regional service support. This systems-level approach can be especially effective in markets where integrated procurement, local clinical education, and after-sales reliability influence formulary decisions. It also allows suppliers to compete on total workflow fit rather than catheter unit price alone.
Specialty positioning around interventional and oncology use. Companies such as Cook Medical, AngioDynamics, Merit Medical, and ICU Medical have carved out roles around interventional radiology, oncology, and vascular access solutions that incorporate securement or disinfection technologies. Their strategies tend to emphasize application-specific design, targeted clinical support, and product configurations that match specialized procedural needs. In areas where catheter selection is closely tied to procedure type or patient population, application expertise can be a stronger differentiator than general catalog breadth.
Innovation-led entry and insertion technology. Access Vascular represents a newer angle in the market by focusing on midlines and CVCs paired with advanced insertion technologies. This model reflects a broader trend: new and expanding entrants are not necessarily trying to win solely on commodity catheter production. Instead, they aim to differentiate through placement reliability, design simplicity, or integrated access systems that reduce procedural friction. In a market where established players already hold substantial share, insertion technology and workflow integration provide one of the more credible paths to carve out position without competing only on price.
The competitive landscape is likely to continue evolving along two parallel tracks. One track will see consolidation and partnership activity as larger players seek to broaden portfolios, strengthen regional coverage, or acquire specialized technology. Another track will favor smaller or niche participants who can compete by solving specific clinical pain points, serving regional demand more responsively, or offering devices with meaningful design distinctions. The companies most likely to retain pricing power will be those that can tie their products to measurable workflow or outcome benefits rather than competing as interchangeable catalog items.
Near-Term Future Trends and Commercial Implications
Looking across the current data and recent industry developments, three interrelated trends are likely to shape the CVC market over the next three to five years.
Insertion reliability will become a more explicit purchasing criterion. As more products and insertion systems enter the market, buyers will increasingly compare not only catheter specifications but also the consistency and training burden associated with placement. Devices that reduce first-attempt failures, standardize technique, or fit cleanly into existing insertion workflows can command preference even when unit pricing is not the lowest. Commercial opportunity here lies in packaging device and insertion support as a coherent solution rather than selling the catheter in isolation. The risk is that overclaiming procedural ease without supporting clinical evidence or training infrastructure can undermine trust during value analysis and post-market evaluation.
Quality documentation and standards alignment will increasingly influence sourcing decisions. With clearer testing expectations for sterile single-use catheters and continued scrutiny following quality events, procurement teams are likely to weigh supplier quality systems, traceability, and compliance history more heavily. Companies that can present robust validation data, consistent manufacturing controls, and transparent supplier oversight will have an advantage in both tender processes and ongoing purchasing relationships. The commercial upside is clearer credibility in regulated and institutional settings; the downside for slower-moving competitors is that compliance gaps, even when unrelated to direct device performance, can translate into lost formulary standing.
Demand for complication-reducing and workflow-compatible designs will deepen. Antimicrobial coatings, securement strategies, lumen configurations aligned to therapy complexity, and designs that limit manipulation after placement will remain central to product conversation. As hospitals continue to balance infection prevention, staff efficiency, and cost containment, there is room for products that demonstrate a credible link between device attributes and reduced downstream burden. The opportunity is strongest for manufacturers that can support their designs with clinical rationale and practical implementation guidance. The uncertainty lies in the fact that reimbursement and procurement environments may not always reward clinical nuance equally across regions, so success may depend on tailoring value propositions to local economic and institutional incentives.
What This Means for Decision-Makers
The strategic implications vary by role, but all stakeholders should be thinking about how CVC purchasing and supply decisions intersect with clinical outcomes, operational reliability, and long-term portfolio positioning.
For manufacturers, the priority is differentiation that holds up in real procurement environments. Product development should not stop at catheter geometry or coating technology. Companies should evaluate how insertion support, securement compatibility, documentation readiness, and regional service capabilities influence adoption. Where possible, design investments should target the access episode as a whole, because buyers increasingly compare total workflow impact rather than individual component attributes. Manufacturers should also treat standards alignment and quality documentation as competitive tools rather than compliance overhead, since these factors increasingly shape tendering credibility and international market access. A practical strategic question is whether the business is competing as a commodity supplier or as a solutions provider; the answer should drive investment in evidence generation, clinical education, and supplier transparency.
For investors, the market offers steady growth but rewards selective exposure. The 6.8 percent CAGR and expanding revenue base through 2032 indicate a durable underlying demand environment, yet top-line growth alone will not distinguish winners. Investment theses should account for companies that demonstrate clear clinical positioning, credible quality infrastructure, and the ability to win beyond price competition. Particular attention should go to firms that can translate device innovation into measurable workflow or complication reduction, as well as those with resilient supply-chain practices and strong documentation discipline. Investors should also monitor where consolidation or technology acquisition could accelerate portfolio value, especially if larger players seek to strengthen insertion-technology capabilities or regional coverage. The main risk is assuming that broad market growth will lift all participants equally; in a moderately concentrated field, share gains and margin stability will likely be uneven.
Inferior Vena Cava (IVC) Filters Market
For procurement and supply-chain leaders, the focus should shift toward total cost of ownership and resilience. CVC sourcing decisions should reflect more than unit price or catalog convenience. Value-analysis processes have an opportunity to weigh insertion reliability, complication risk, securement and disinfection compatibility, supplier quality history, and contingency readiness. Recent quality events and evolving testing expectations reinforce the value of supplier transparency and defined oversight. Procurement teams can also benefit from standardizing evaluation criteria that capture clinical performance and operational dependability, rather than treating quality records as a separate administrative issue. In practice, that means building supplier assessments that combine product specifications with evidence of consistent manufacturing controls, traceability, and response capability when disruptions arise. The strongest purchasing strategies will be those that align clinical preference with supply reliability, reducing the likelihood that short-term cost savings create longer-term operational exposure.
Conclusion
The central venous catheter market is moving from steady volume expansion toward a more competitive, quality-sensitive, and workflow-driven environment. Growth remains healthy, but the decisive factors are increasingly tied to insertion reliability, standards alignment, complication reduction, and supply-chain resilience. Companies that can articulate and demonstrate how their products improve the access episode, while maintaining rigorous quality and documentation practices, are best positioned to defend share and capture value. For hospital buyers, the opportunity lies in evaluating CVCs through a total-cost and total-reliability lens rather than catalog price alone. For investors, disciplined attention to differentiation and operational maturity will matter more than broad market tailwinds. The strategic window is open for players who treat CVCs not as interchangeable disposables but as integral components of a high-stakes clinical workflow where consistency, safety, and reliability carry direct commercial consequences.
For detailed analysis of this topic, please visit the official page: Central Venous Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com