

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Airborne Particle Counter Market: Why Cleanroom Monitoring Drives 7.25% CAGR Growth

The Airborne Particle Counter Market: Strategic Shifts and Commercial Opportunities Through 2032
The global airborne particle counter market operates at the intersection of precision engineering, regulatory compliance, and industrial quality control. Over the 2020 to 2025 historical period, the market expanded from 850.0 million USD to 1,170.0 million USD, reflecting a compounding trajectory that accelerated notably after the 2022 baseline. Forward projections from 2026 to 2032 indicate a sustained compound annual growth rate of 7.25 percent, pushing total revenue from 1,267.85 million USD in the base year to 1,903.0 million USD by the close of the forecast window. This expansion is not merely volume-driven; it reflects a structural reorientation in how industries approach air quality validation, contamination control, and environmental monitoring. For executives and capital allocators, the index of growth alone is insufficient. The strategic value lies in understanding which segments are maturing, which are entering inflection points, and where competitive positioning will determine margin resilience over the next cycle.
The market remains moderately fragmented, with the top three companies capturing approximately 32.5 percent of total revenue and the top five holding around 41.2 percent. This concentration pattern suggests a landscape where scale, technological differentiation, and compliance certification create meaningful moats, yet leaves substantial runway for specialized players, regional expansion, and niche application capture. The strategic question for decision-makers is no longer whether the market is growing, but how growth will be distributed across form factors, application verticals, and geographies, and what capabilities will separate durable performers from commoditized suppliers.
Current Market Dynamics and Structural Challenges
The trajectory of the airborne particle counter industry is shaped by several interlocking pressures that define both opportunity and risk.
First, the market is navigating a transition from episodic compliance testing toward continuous, integrated monitoring. Historically, many cleanroom and manufacturing environments relied on periodic manual verification. Rising regulatory expectations, coupled with the operational cost of deviations in pharmaceutical and semiconductor environments, are pushing organizations toward real-time data streams and networked instrumentation. This shift compresses sales cycles for standalone devices but expands opportunities for systems integration, data architecture, and long-term service relationships. Companies that treat particle counters as isolated measurement tools risk being displaced by vendors offering analytics, calibration management, and workflow integration.
Second, supply chain stability and component availability have emerged as a recurring operating constraint. Precision optical sensors, laser modules, and detector housings depend on specialized manufacturing processes and qualified suppliers. Periods of component scarcity or lead-time volatility can delay product rollouts, pressure pricing, and complicate service-level commitments. The practical implication is that inventory strategy, multi-sourced component design, and service network density now influence competitive positioning as much as core detection performance.
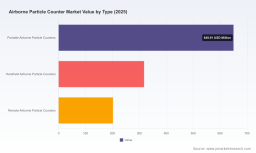
Third, the industry faces a divergence in application requirements that complicates product portfolio strategy. A handheld unit optimized for quick cleanroom verification differs substantially in design priorities from a remote, continuously operating counter deployed for environmental monitoring or aerosol research. Portables emphasize mobility, battery endurance, and rapid deployment. Handhelds prioritize ergonomics, ease of operation, and targeted spot checks. Remote systems require long-term stability, connectivity, and minimal maintenance. Manufacturers that attempt to serve all form factors without clear architectural separation often dilute engineering focus and after-sales support quality. The market is gradually rewarding companies that define a primary use case, master its compliance and performance requirements, and extend into adjacent applications through deliberate platform expansion rather than broad, unfocused lineups.
These dynamics create a clear strategic fork: growth will favor players who align product architecture with measurable operational outcomes, who can navigate component and service constraints, and who can translate detection accuracy into compliance assurance and process confidence.
Worldwide Andersen Cascade Impactor Market
Key Growth Drivers Redefining the Competitive Field
Several structural forces are accelerating demand and reshaping the value proposition of airborne particle counters.
Technological innovation in detection and data integration is moving the market beyond raw count accuracy toward actionable environmental intelligence. Advanced optical designs, improved particle sizing resolution, and lower noise thresholds are enabling devices to meet increasingly stringent validation requirements. Equally important is the shift toward connected instruments. Data logging, remote configuration, automated calibration reminders, and compatibility with facility management or quality systems are becoming baseline expectations rather than premium add-ons. For end users, the value proposition has expanded from "does this device measure particles" to "does this device integrate into our documentation, audit readiness, and continuous improvement workflow." Vendors that embed connectivity, software interoperability, and user-friendly reporting into the core offering are gaining traction with procurement and quality teams who must reduce manual overhead and improve traceability.
Policy and regulatory pressure continues to anchor demand across multiple sectors. Cleanroom standards, pharmaceutical manufacturing controls, and semiconductor process requirements all depend on reliable airborne contamination monitoring. Regulatory compliance is not a one-time purchase driver; it creates recurring demand through verification cycles, equipment qualification, recalibration, and replacement programs. In pharmaceutical and biotech environments, contamination control is directly tied to product safety, batch integrity, and audit outcomes. In semiconductor and electronics manufacturing, particle control influences yield and process stability. These realities make airborne particle counters part of a broader risk-management infrastructure, which supports more resilient demand than discretionary equipment categories. The regulatory environment also rewards suppliers that can demonstrate standardized performance, clear documentation support, and adherence to recognized cleanliness classification frameworks.
Demand-side shifts in industrial and environmental behavior are broadening the use base. Beyond traditional cleanroom certification, organizations are increasing attention to indoor air quality, aerosol monitoring, and environmental research. Facilities that previously treated air monitoring as a compliance checkbox are beginning to view it as an operational hygiene and process quality function. This evolution expands the addressable market and introduces new buying criteria, including ease of deployment, sensitivity to varying particle sizes, and suitability for different environments. At the same time, procurement teams are comparing total cost of ownership more aggressively, weighing instrument price against service frequency, consumable requirements, training burden, and the cost of measurement uncertainty. The result is a market where performance credibility and support economics increasingly determine purchase decisions.
Supply-side and cost structure evolution is also shaping strategy. As optical and electronic subsystems mature, some performance capabilities are becoming more accessible, which can lower barriers to entry for competent regional manufacturers and increase price competition in standardized categories. At the same time, differentiation through software, calibration services, application expertise, and compliance support is becoming a more reliable path to margin protection. Companies that compete solely on hardware specifications in saturated segments face greater commoditization risk, while those that build repeatable service models and application-specific configurations can sustain stronger returns.
Competitive Landscape and Strategic Positioning
The competitive set in this market is defined by a mix of established instrumentation specialists, diversified testing-equipment providers, and focused cleanroom compliance vendors. Several strategic positioning patterns stand out.
TSI Incorporated has built a reputation around precision particle measurement, with portable and handheld condensation particle counter models aimed at pharmaceutical and semiconductor cleanroom compliance. Its positioning reflects deep measurement engineering and a focus on applications where accuracy and repeatability are non-negotiable. Lighthouse Worldwide Solutions emphasizes real-time airborne particle counters for cleanroom certification and monitoring in pharmaceutical and biotech settings, leaning into workflow relevance and operational readiness. RION Co., Ltd. competes with an emphasis on precision and compliance across airborne and liquid particle counting, appealing to users who value measurement consistency and technical rigor. Particle Measuring Systems targets contamination monitoring and cleanroom particle counter solutions for pharmaceutical and semiconductor manufacturers, aligning closely with regulated process environments.
Other players extend the landscape across different use cases. Kanomax USA focuses on handheld and portable counters for cleanroom verification and real-time monitoring. Climet Instruments offers portable and industrial particle counters for healthcare and pharmaceutical cleanroom applications. Met One Instruments serves indoor air quality and cleanroom environmental monitoring with portable and handheld units. Beckman Coulter, through the Danaher Corporation, provides airborne particle counters that support ISO 14644 and GMP compliance, often integrated into broader contamination-control and laboratory workflows. Fluke Corporation targets HVAC, indoor air quality, and cleanroom testing with air particle counters that emphasize field usability and serviceability. PAMAS contributes laser particle counters with applications in contamination analysis, including airborne use cases alongside liquid measurement.
These profiles reveal a market where differentiation is increasingly multidimensional. The most effective positioning tends to combine three elements: measured performance credibility, application-specific configuration, and support infrastructure that reduces risk for the buyer. Some leaders compete on measurement heritage and engineering depth. Others compete on user workflow, service coverage, or integration into broader compliance and quality systems. The most resilient players are those that can articulate a clear primary application, demonstrate compliance-support value, and maintain consistent field performance across that segment.
The competitive landscape is gradually evolving along three directions. Consolidation remains plausible as larger instrumentation or life-sciences platforms seek to expand contamination-monitoring portfolios through acquisition or cross-selling. At the same time, specialization continues to create room for focused competitors that serve high-compliance verticals with tailored configurations and strong application support. New entrants are most likely to succeed when they bring a distinct advantage in connectivity, usability, niche application expertise, or regional service density rather than attempting to win solely on general-purpose hardware.
Worldwide Liquid Borne Particle Counters Market
Forward Outlook: Trends Shaping the Next Three to Five Years
The next phase of market development is likely to be defined by integration, segmentation discipline, and application-driven growth.
First, continuous monitoring and data-centric operations will become the dominant growth narrative. Devices will increasingly be evaluated not just for detection performance but for their ability to feed reliable data into quality systems, support trending analysis, and reduce manual verification burden. This creates commercial opportunities in software-compatible hardware, service contracts that include calibration and performance verification, and bundled offerings that lower the operational friction of compliance. Companies that treat the instrument as a data node within a broader contamination-control strategy will capture more durable relationships than those competing only on standalone measurement specs.
Second, application specialization will sharpen. Cleanroom monitoring, semiconductor and electronics manufacturing, pharmaceutical manufacturing, and aerosol monitoring and research each impose different performance, robustness, and documentation requirements. Over the next several years, vendors are likely to face pressure to clarify which applications they serve best and to configure products accordingly. The commercial opportunity lies in building repeatable application packages, strengthening compliance documentation support, and tailoring training and service models to the operational realities of each vertical. Broad, undifferentiated product lines will increasingly struggle against purpose-built solutions that reduce deployment risk and simplify qualification.
Third, regional expansion and localized service capability will matter more as demand diversifies. Growth in Asia Pacific, alongside continued strength in North America and Europe, suggests that proximity to end users, technical support coverage, and regional compliance familiarity will be important competitive variables. In practical terms, companies that invest in service networks, local calibration and qualification support, and regional application expertise can convert demand into market share more effectively than those relying primarily on centralized distribution. The risk is that rapid geographic expansion outpaces service readiness, which can undermine trust in regulated environments where response time and documentation reliability are critical.
Potential uncertainties should be acknowledged. Regulatory frameworks can tighten or shift interpretation, influencing qualification requirements and purchase timing. Macroeconomic pressure may cause procurement cycles to lengthen, particularly in discretionary or non-regulatory applications. Component availability and manufacturing consistency can affect product launch timing and service reliability. Finally, if connectivity and software expectations rise faster than some suppliers can execute, a gap may open for new entrants or for more agile players that can deliver integrated data workflows more effectively. These risks do not weaken the market outlook; they raise the strategic importance of execution discipline and application alignment.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the priority is to define where measurement excellence, compliance support, and operational usability intersect most profitably. Product strategy should emphasize a clear application focus, dependable field performance, and connectivity that reduces the buyer's administrative and compliance burden. Service and calibration support should be treated as part of the core offering rather than an afterthought, because regulated buyers increasingly weigh long-term support reliability alongside instrument price. Where portfolios span multiple form factors, companies should ensure that each category has a distinct purpose, clear target user, and appropriately aligned engineering and service model.
For investors, the most attractive exposure is likely to come from companies that combine credible measurement capability with recurring revenue potential through service, calibration, and integration relationships. The market's moderate concentration and application diversity create opportunities in targeted vertical focus, regional service expansion, and data-enabled offerings. Capital allocation should favor business models that can demonstrate compliance relevance, customer retention economics, and a clear path to margin defense beyond hardware price competition. Equally important is assessing whether a company's product roadmap aligns with the shift toward continuous monitoring and connected data workflows, because those directions will shape demand quality over the forecast period.
For procurement and quality leaders evaluating equipment strategies, the decision should extend beyond instrument specifications to include qualification support, calibration and service expectations, integration with documentation workflows, and the supplier's ability to reduce operational risk. Total cost of ownership is best assessed through the lens of compliance readiness, measurement confidence, and ongoing support rather than purchase price alone. Organizations that standardize on instruments with strong application alignment and dependable service coverage can reduce qualification friction, improve audit readiness, and streamline ongoing environmental monitoring programs.
The strategic picture is clear: the airborne particle counter market is moving from a compliance-driven purchase category toward a more integrated, data-aware, and application-specific market. Growth will be sustained, but durable advantage will depend on how well companies align technology, service, and workflow value with the needs of regulated and quality-sensitive environments. Decision-makers who map their strategy to these structural shifts will be better positioned to capture opportunity and manage risk through the remainder of the decade.
PW Consulting
Accessing Deeper Segment-Level Intelligence
Strategic choices in this market benefit from detailed visibility into segment-level demand patterns, regional dynamics, and application-specific purchasing behavior. A full research report can provide the additional granularity needed to evaluate product-portfolio fit, identify underserved application pockets, and benchmark competitive exposure with more precision. Readers looking to translate these market-level insights into operational plans, investment theses, or procurement strategies should consider accessing the complete study for deeper segmentation data and customized guidance aligned to their specific operating context.
For detailed analysis of this topic, please visit the official page: Airborne Particle Counter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com