

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Glass Fiber Prepreg Market: 5.5% CAGR Growth and Strategic Shifts Through 2032

The Glass Fiber Prepreg Market: Strategic Trends and Commercial Opportunities Through 2032
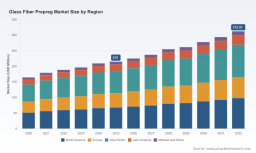
The glass fiber prepreg market has entered a phase of steady, structurally supported expansion. Valued at approximately USD 215.0 million in 2025, the market is projected to reach USD 312.5 million by 2032, reflecting a compound annual growth rate of 5.5 percent. This trajectory is not the result of a single tailwind but rather the convergence of technology maturation, regulatory standardization, and shifting demand patterns across high-performance composite applications. As noted in recent industry data, glass fiber prepreg is also identified as the fastest-growing reinforcement segment within the broader prepreg market, expanding at a 7.62 percent CAGR through 2031. For executives and investors evaluating advanced materials portfolios, the question is no longer whether the market will grow, but how to position operations, capital, and supply chains to capture disproportionate value within a consolidated and technically demanding landscape.
Glass Fiber Composites Market
Concentration levels underscore the maturity of the sector. Three manufacturers account for roughly 60 percent of revenue, while the top five capture approximately 80 percent. This structure signals both barriers to entry and advantages for incumbents that have invested in qualification pipelines, production scale, and application-specific resin systems. The following sections outline the core challenges shaping the market, the primary drivers accelerating adoption, the competitive dynamics among leading producers, and the strategic implications for manufacturers, investors, and procurement teams over the next three to five years.
Market Context and Structural Challenges
A Consolidated Baseline with Steady Growth
The market’s expansion from 2020 through 2025 was marked by consistent year-over-year gains, with revenue moving from 164.5 million to 215.0 million. The forecast period through 2032 sustains this momentum, with the 2030–2032 window showing accelerating increments as downstream applications scale. Growth is distributed across regions, with Asia Pacific and North America representing the two largest demand centers, followed by Europe and Latin America, while the Middle East and Africa contribute a smaller but developing base. This geographic spread reflects the global nature of composite-intensive infrastructure, aerospace development, and industrial manufacturing, but it also means that pricing dynamics, logistics, and qualification requirements vary significantly by market.
The type and application splits further illustrate where value concentrations lie. Epoxy resin systems dominate the resin mix, reflecting the material’s balance of processability, mechanical performance, and compatibility with established curing cycles. Wind energy and aerospace remain the most demanding application segments, requiring prepregs that meet stringent qualification standards and consistent fiber architecture. Automotive and other industrial uses contribute meaningful volume but often operate under different cost and performance thresholds. This segmentation matters because it determines who sets the requirements, who absorbs the qualification cost, and where margin profiles are sustainable.
Three Structural Challenges Defining the Current Inflection Point
First, raw material cost volatility and supply constraints are reshaping margin planning. U.S. glass fiber prices reached USD 1,482 per metric ton in March 2026, up from USD 1,458 per metric ton in Q4 2025, reflecting moderate upward pressure amid constrained supply. While the move is not dramatic, repeated increments of this nature can compress margins for producers who have not locked in feedstock agreements or invested in fiber efficiency on the preform side. For buyers, especially those operating on fixed-price contracts or program timelines that span multiple quarters, these cost trends create budget forecasting risk and can delay qualification programs if alternative grades must be re-evaluated.
Second, qualification and standardization complexity remains a persistent bottleneck. The March 2025 revision of NMS 765 established Class 3 requirements for woven glass fiber prepreg fabric within NCAMP specifications for epoxy-based prepregs. This is not a trivial administrative change; it reshapes what counts as qualified material for design allowables and, by extension, which products can enter aerospace and certain industrial structural programs. Compliance with NCAMP specifications and the maintenance of ISO 9001 quality systems are now baseline expectations among major producers. The implication is clear: qualification capability is a competitive asset, and companies that cannot navigate the documentation, testing, and design-allowable process will face longer sales cycles and narrower addressable demand.
PW Consulting
Third, the market is navigating application diversification beyond its traditional cores. While wind energy and aerospace continue to anchor demand, the fastest-growing reinforcement segment within prepregs is being driven by electronics substrates, including 5G electronics and LED applications. This shift introduces new processing requirements, different thermal and electrical performance targets, and a customer base that may evaluate cost and lead time more aggressively than aerospace primes. Manufacturers rooted in high-spec structural programs need to decide whether to extend into these high-growth electronics-adjacent applications, and if so, whether to adapt existing lines or build new capabilities, without diluting their core qualification position.
Key Drivers Shaping the Market Trajectory
Technology Innovation and Resin System Maturation
Advances in resin formulation, fiber architecture, and process control are expanding the addressable performance envelope of glass fiber prepregs. Epoxy systems continue to lead because they offer predictable cure behavior, strong interfacial bonding, and broad compatibility with automated layup and out-of-autoclave processes. At the same time, phenolic and other resin types maintain relevant niches where temperature resistance, cost positioning, or specific end-use environments favor their properties. The practical outcome is that producers are no longer competing on fiber content alone; differentiation increasingly comes from resin system design, uniformity of impregnation, vacuum integrity during storage, and the ability to deliver consistent mechanical performance across wide formats.
Recent operational moves reflect this emphasis on capability expansion. New facility groundbreakings and wide-format UD prepreg and film coating line commissions point to investment in format flexibility, throughput, and finer process control. These investments matter because wider formats reduce handling waste and improve layup efficiency for large structural parts, while continuous fiber thermoplastic and thermoset capacity expansions increase the options available to design engineers. In this environment, technical credibility is built through demonstrated consistency and the ability to support customers through design, testing, and production ramp.
Policy, Standards, and Regulatory Environment
Standardization is acting as both a gate and an enabler. NCAMP qualification pathways and the maintenance of ISO 9001 systems are widely expected among leading producers, and compliance with NCAMP specifications for basis design allowables is becoming a practical requirement for materials that feed into certified programs. The March 2025 NMS 765 revision is a concrete example of how standards evolve to reflect product realities and application needs, and it signals that the bar for woven glass fiber prepreg fabric in epoxy-based systems is being refined, not relaxed.
Thermoplastic Prepreg Market
For the market, this dynamic has two effects. It raises the threshold for credible participation, favoring firms with established testing infrastructure and documentation discipline. At the same time, it reduces uncertainty for buyers, because qualified materials with defined allowables shorten downstream engineering risk. Strategic suppliers are therefore investing in qualification not merely as a compliance exercise, but as a commercial differentiator that enables entry into higher-value programs.
Demand-Side Shifts in Core and Adjacent Applications
On the demand side, wind energy remains a foundational driver for glass fiber prepregs, particularly where blade structures and associated components require durable, cost-effective reinforcement. Aerospace demand continues to be shaped by commercial aircraft programs and industrial structural components that value weight efficiency and certified material performance. Automotive demand is growing as lightweighting objectives intersect with cost-conscious material selection, and this segment often rewards suppliers that can provide consistent quality at scale without requiring the full complexity of aerospace-grade qualification for every part.
Equally important is the growth signaled in electronics-adjacent applications. The identification of glass fiber prepreg as the fastest-growing reinforcement in the prepreg market, with a 7.62 percent CAGR through 2031 and drivers tied to 5G electronics and LED substrates, indicates that the material is gaining relevance where dimensional stability, surface quality, and thermal behavior matter. This does not replace structural demand, but it broadens the customer base and creates opportunities for producers that can adapt resin systems and fiber formats to electronics processing needs. The strategic lesson is that application breadth can be a growth lever, but only when supported by the right product architecture and customer support model.
Supply Chain and Cost Structure Realignment
The supply chain for glass fiber prepregs is being reshaped by the interplay of fiber availability, resin sourcing, and regional production footprints. Rising fiber prices, such as the USD 1,482 per metric ton level recorded in March 2026, are prompting both producers and buyers to re-examine sourcing strategies, inventory buffering, and the economics of regional manufacturing. Producers with integrated or strategically aligned supply chains can protect margins more effectively, while those dependent on spot procurement may face more volatile input costs and less predictable program pricing.
Capacity expansions and line commissions also reflect a broader realignment toward throughput and format flexibility. Wide-format UD prepreg and film coating capabilities reduce downstream processing constraints and can improve yield for large parts, while continuous fiber thermoplastic and thermoset expansions increase the range of solutions available to engineering teams. These moves do not just add volume; they change the cost structure and customer value proposition by reducing handling losses, improving process reliability, and enabling more efficient layup and cure cycles. In a market where qualification and consistency are valued, these operational improvements can be as commercially significant as the product specs themselves.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The leadership group in glass fiber prepregs is defined by a combination of scale, qualification depth, and application focus. Hexcel Corporation operates as a major producer of aerospace-grade glass fiber prepregs under its established trademarked product families, supplying woven and unidirectional glass fiber-reinforced epoxy prepregs for commercial aerospace and industrial applications. Its strategic emphasis includes strengthening application support and customer collaboration, illustrated by the May 2026 groundbreaking of a new applications center in partnership with Wichita State University’s NIAR, an investment that reinforces technical support, testing, and qualification enablement.
Toray Industries stands out for its breadth across thermoset UD and fabric glass fiber prepregs, including E-glass and S2-glass systems used in aerospace and industrial structural components. Its recent NCAMP qualification for a new high-performance prepreg system, announced in March 2026, demonstrates a continued focus on qualification advancement as a commercial lever. Toray also expanded continuous fiber thermoplastic composite capacity in late 2025, signaling a dual strategy of deepening thermoset capabilities while broadening thermoplastic options for customers seeking processing flexibility.
SGL Group maintains a European manufacturing base and supplies composite materials across wind energy, automotive, aerospace, and industrial applications. A strategic partnership announced in August 2025 with a leading European automaker underscores how established producers are embedding themselves into customer roadmaps for lightweight composite solutions, using glass fiber prepreg technologies as part of a broader value proposition that includes application engineering and supply reliability.
Niche and specialty players add texture to the landscape. Axiom Materials formulates and manufactures high-performance glass fiber prepregs with epoxy, phenolic, and other resin systems, targeting demanding environments such as deep-sea, space, and aerospace composites. Park Aerospace Corp. specializes in aluminum-coated glass fiber prepregs and advanced composite materials for aerospace and lightning strike protection applications. These firms illustrate how differentiation can come from specialized resin architectures, protective coatings, and application-specific performance characteristics rather than scale alone.
Operational activity among other producers also reflects the market’s direction. A February 2026 commissioning of wide-format UD prepreg and film coating lines by SHD Composites points to continued investment in format and throughput capabilities, reinforcing the industry-wide emphasis on layup efficiency and process consistency.
How the Landscape Is Evolving
Three patterns are shaping the future structure of the market. First, consolidation pressures are likely to persist because qualification depth, quality systems, and application support create real barriers for new entrants seeking to compete in structurally demanding segments. Second, differentiation is shifting from resin type alone toward integrated value propositions that combine product consistency, format flexibility, customer qualification support, and supply reliability. Third, the market is gradually diversifying as electronics-adjacent demand grows, which may encourage both specialization and selective entry by firms that can align product architecture with new processing requirements.
For incumbents, the strategic priority is to protect and extend qualification-based advantage while investing in capabilities that improve customer throughput and reduce total cost of ownership for end users. For new or smaller players, the opportunity lies in targeted differentiation—such as specialized coatings, resin systems for niche environments, or format-specific solutions—rather than head-to-head competition in broadly dominated structural segments.
Future Trends and Commercial Implications (2026–2032)
Trend One: Qualification-Driven Competition Becomes the Norm
Over the next three to five years, the practical importance of NCAMP-aligned qualification and ISO 9001 system discipline will increase rather than diminish. As specifications evolve and more programs require defined design allowables, suppliers that can deliver qualified materials with documented consistency will capture a larger share of higher-value demand. The commercial implication is that qualification is not just a technical requirement but a market-access strategy. Companies that invest early in testing infrastructure, documentation rigor, and customer co-development are likely to enjoy shorter qualification cycles and stronger positioning in aerospace and industrial structural programs.
The associated risk is that qualification investment is costly and time-intensive, and not all product lines will justify the same level of commitment. Firms will need to prioritize which systems and applications warrant full qualification pathways versus which can be served through alternative quality assurances or lower-specification segments.
Trend Two: Application Diversification Broadens the Growth Base
The growth signal from 5G electronics and LED substrates indicates that glass fiber prepreg demand will increasingly span structural and functional application domains. This diversification can stabilize revenue streams by reducing reliance on a narrow set of end markets, but it also introduces new performance targets and customer expectations. Suppliers that can extend into electronics-adjacent applications without losing discipline in their core structural businesses may benefit from higher growth rates and broader demand resilience.
The risk here is execution complexity. Extending into electronics substrates often requires different fiber architectures, surface quality controls, and resin behaviors, as well as sales and support models tuned to electronics procurement cycles. Without careful product mapping and process adaptation, attempting to serve divergent segments can strain operations and dilute focus.
Trend Three: Cost and Supply Chain Discipline Differentiate Margin Performers
With fiber prices trending moderately upward and capacity expansions adding supply in select regions, margin performance will increasingly depend on supply chain design, process efficiency, and format optimization. Producers that secure feedstock arrangements, minimize handling losses through wide-format and UD capabilities, and improve cure and layup efficiency can protect margins more effectively than those competing primarily on price in commoditizing segments. For buyers, this environment rewards suppliers that can demonstrate consistent quality, reliable delivery, and total-cost benefits rather than lowest unit price alone.
The uncertainty lies in the rhythm of raw material pricing and regional supply constraints. If constraints intensify or regional imbalances widen, producers with more flexible sourcing and localized production may outperform those dependent on single-source inputs or long logistics chains. Planning for this uncertainty means stress-testing cost assumptions and building optionality into supplier relationships and capacity allocation.
Strategic Implications for Decision Makers
For Manufacturers and Producers
Prioritize qualification and application support as commercial assets. In a market where standards are increasingly specific and design allowables matter, the ability to guide customers through qualification and demonstrate consistent performance is a durable advantage. Invest in format flexibility and process control that reduce downstream waste and improve layup efficiency, because these improvements translate into better total cost of ownership for buyers and stronger positioning against price-only competitors. Decide deliberately where to expand application breadth. High-growth electronics-adjacent demand can be attractive, but success depends on matching resin systems and fiber formats to new processing needs and building the right technical support model, rather than repurposing structural lines without sufficient adaptation.
For Investors
Evaluate exposure to qualification-intensive segments with care. Companies that hold or are advancing NCAMP-aligned capabilities, maintain disciplined quality systems, and serve applications with defined performance requirements are better positioned to defend margins and secure program participation. Consider the strategic value of capacity and format investments that improve throughput and reduce handling losses, as these can support both margin resilience and customer retention. Watch for application diversification as both an opportunity and a risk; businesses that expand into high-growth electronics and LED-related demand with clear product-market fit may offer stronger growth profiles, while those that stretch too broadly without the right capabilities may face operational drag.
For Procurement and Supply Chain Leaders
Assess suppliers on total program value rather than unit price alone. In a market shaped by qualification requirements, consistency, and moderate raw material cost pressure, the reliability of supply, documentation quality, and alignment with design allowables can materially affect program risk and downstream engineering effort. Where possible, secure multi-source options for critical prepreg grades, especially if program timelines are long or if regional supply constraints could affect availability. Engage early with suppliers that can support qualification and process optimization, because collaboration on material selection, layup efficiency, and cure behavior often yields savings that outweigh small unit-price differences.
Closing Perspective
The glass fiber prepreg market is moving through a period where growth is visible, but the real differentiation lies in how companies navigate qualification, application breadth, and supply chain discipline. The projected expansion from USD 215.0 million in 2025 to USD 312.5 million by 2032, at a 5.5 percent CAGR, provides a strong directional backdrop. Yet the commercial winners will be those who treat product consistency, standards alignment, and format efficiency as strategic levers, not just operational details. For organizations seeking to act on these dynamics with greater precision, more detailed segmentation, regional nuance, and scenario analysis can sharpen the decision process. A complete research report is available for teams that want to translate these trends into segment-level priorities, competitive benchmarks, and tailored action plans.
For detailed analysis of this topic, please visit the official page: Glass Fiber Prepreg Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com