

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ferric Chloride Market: How 5.2% CAGR and Water Treatment Demand Reshape Growth to 2032

Strategic Shifts and Commercial Opportunities in the Ferric Chloride Market
Market Trajectory and Core Dynamics
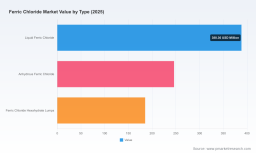
The global ferric chloride market is entering a phase of measured but steady expansion, with projected revenue expected to reach USD 1,175.0 million by 2032, representing a compound annual growth rate of 5.2 percent over the 2026–2032 forecast horizon. This growth trajectory reflects compounding investments in water infrastructure, sustained industrial demand for metal surface conditioning, and gradual modernization of treatment protocols across municipal networks. Starting from approximately USD 820.0 million in 2025, the market is positioned to add meaningful revenue layers as downstream capital expenditures accelerate and regulatory frameworks tighten.
Despite this favorable outlook, the sector sits at a strategic inflection point. Infrastructure spending cycles increasingly demand batch consistency and cost predictability, yet upstream feedstock variability introduces margin pressure for producers reliant on hydrochloric acid and chlorine feedstocks. Simultaneously, stricter potable water certification requirements and evolving environmental discharge limits are altering procurement criteria, forcing suppliers to reconfigure quality assurance workflows and product positioning. These shifts are not merely operational; they are reshaping competitive advantage and determining which players can scale reliably across regions.
For executives and investors, the implication is clear: growth will increasingly differentiate between companies that treat ferric chloride as a commodity input and those that position it as a certified, application-tuned solution. The market’s expansion trajectory remains intact, but value capture will depend on how effectively stakeholders navigate feedstock exposure, compliance friction, and application-specific demand patterns.
Key Demand Drivers Reshaping the Landscape
Technological evolution in water treatment chemistry is one of the most compelling forces behind ferric chloride demand growth. Municipalities and industrial operators are prioritizing coagulation efficiency, sludge minimization, and phosphorus reduction, which collectively favor coagulants with predictable dosing characteristics and high removal performance. Innovation efforts are increasingly centered on purity control, concentration optimization, and formulation adjustments that align with specific treatment plant conditions. These advances do not simply improve performance; they expand the addressable use cases, allowing producers to justify premium positioning in regulated segments where reliability carries direct operational value.
Regulatory pressure continues to act as both a constraint and an accelerator. Drinking water applications require compliance with NSF/ANSI Standard 60, and certification by an ANSI-accredited organization remains a non-negotiable procurement prerequisite for many municipal contracts. This regulatory layer is pushing the market toward consolidation of qualified suppliers and elevating the importance of audit-ready production practices. At the same time, environmental discharge standards and phosphorus reduction mandates are reinforcing demand for coagulants that help treatment facilities meet tightening effluent targets, linking regulatory compliance directly to demand resilience.
Demand-side behavior is shifting as well. Water utilities and industrial processors are increasingly evaluating total cost of treatment rather than unit price alone, which expands the relevance of product consistency, logistics dependability, and technical support. In PCB etching and metal surface treatment, demand remains tied to manufacturing productivity and process precision, meaning that price sensitivity is frequently offset by the need to avoid production disruptions or quality failures. As procurement teams place greater weight on supply reliability and compliance documentation, suppliers that can demonstrate certified quality, stable batch performance, and responsive service models gain a meaningful competitive edge.
Supply chain dynamics add another layer of strategic importance. Hydrochloric acid pricing has experienced notable volatility, with prices in China reaching approximately 15 USD per metric ton in December 2025 amid constrained supply from chlor-alkali production. Upstream feedstock availability and cost fluctuations directly influence ferric chloride production economics, making procurement strategy, inventory planning, and regional sourcing decisions central to margin protection. In practical terms, cost volatility is less a temporary disruption than a structural factor that will keep supplier flexibility and supply diversification in focus for the foreseeable future.
Competitive Positioning and the Evolving Market Map
The competitive landscape is defined by a mix of large-scale water treatment specialists, chlorinated product manufacturers, and regional distribution-focused players. Kemira Water Solutions stands out for its focus on liquid ferric chloride products designed for water and wastewater treatment, including phosphorus removal applications. Its strategy emphasizes application-specific formulation and integration with broader water treatment offerings, which supports a position grounded in reliability and treatment performance rather than commodity pricing alone. Kem One reinforces a similar strategic logic within its chlorinated product portfolio, supplying ferric chloride for industrial and water treatment end uses while leveraging manufacturing footprint and product breadth.
Tessenderlo Group takes a different structural approach by producing ferric chloride through byproduct repurposing at sites in France, Belgium, and Switzerland. This model aligns cost efficiency with resource circularity, creating an advantage in segments where sustainability positioning and feedstock management matter. PVS Technologies has carved out a specialized role with NSF-certified liquid ferric chloride intended for potable water and wastewater coagulation, highlighting how certification and product-grade differentiation can support targeted market participation. In the Middle East, Basic Chemical Industries supplies ferric chloride solutions for wastewater treatment, sewage purification, and industrial etching, reflecting regional demand intensity and the importance of localized supply where infrastructure and industrial activity intersect. Hawkins, Inc. operates with a distribution and supply emphasis, offering high-purity ferric chloride in multiple concentrations and grades for water treatment and industrial use, which illustrates the continuing role of agile, grade-flexible suppliers in meeting varied specification requirements.
Recent industry actions underscore how incumbents are adapting to these dynamics. In March 2026, Kemira Chemicals launched a new high-purity ferric chloride solution specifically for municipal water and wastewater treatment applications, signaling a continued push toward product purity and application alignment in regulated markets. Earlier, in April 2024, KERN Strategies & Developments introduced modular 40% ferric chloride production plants capable of converting iron and chlorine, or iron oxides with hydrochloric acid, into ferric chloride on-site for decentralized applications. That development points to a broader strategic possibility: decentralized or semi-decentralized production may become more relevant where logistics costs, regional feedstock conditions, or remote infrastructure needs create friction in centralized supply models.
Industrial Grade Ferric Chloride Market
The market structure remains relatively concentrated, with the top three players accounting for roughly 58 percent of revenue and the top five reaching approximately 65 percent. This level of concentration suggests that scale, certification readiness, and established municipal or industrial relationships continue to confer advantages. However, the landscape is not static. Modular production concepts, regional feedstock economics, and application-specific certifications could lower barriers for specialized entrants in select niches, especially where decentralized supply or differentiated product grades solve specific customer pain points. At the same time, broader consolidation may persist where scale efficiencies, compliance infrastructure, and long-term contract visibility reinforce incumbency.
Worldwide Ferric Oxide Market
Forward Outlook: Trends That Will Define the Next Three to Five Years
One of the most durable trends will be the continued pull toward certified, application-tuned ferric chloride products in potable and wastewater treatment. As municipalities modernize treatment assets and regulators maintain or tighten water quality expectations, procurement will increasingly reward suppliers that can standardize quality, document compliance consistently, and align product specifications to process requirements. This shift should strengthen demand for liquid ferric chloride formulations that offer dosing reliability and treatment efficiency, while also reinforcing the strategic value of certification readiness as a market entrance criterion.
A second trend is the growing relevance of production flexibility in response to feedstock volatility and regional logistics conditions. Because hydrochloric acid and chlorine availability can influence production economics, suppliers that can adapt sourcing strategies, manage inventory buffers, or explore alternative production pathways will be better positioned to protect margins. Modular and decentralized production approaches may gain traction in specific contexts, not as a wholesale replacement for centralized manufacturing, but as a tactical option where supply distance, site-specific demand, or feedstock access makes localized production economically attractive. This does not eliminate the importance of scale; rather, it introduces a more nuanced competitive dimension in which flexibility can complement scale.
A third trend concerns demand concentration across applications. Water and wastewater treatment is expected to remain the dominant demand center, supported by infrastructure renewal, phosphorus management priorities, and compliance-driven procurement. Meanwhile, printed circuit board etching and metal surface treatment should sustain their share of demand, though their growth pattern will likely be more cyclical and tied to electronics manufacturing and industrial activity. For commercial planning, this implies that segment exposure matters: strategies optimized for municipal compliance-driven demand differ materially from those targeting industrial process performance or cyclical manufacturing output.
These trends also carry uncertainty. Feedstock price swings, regulatory interpretation shifts, and changes in municipal budget timing can influence near-term demand pacing. Additionally, any disruption in chlor-alkali supply or regional acid availability may create cost shocks that affect both pricing and availability. Companies that prepare for variability rather than assume stability will be better equipped to convert long-term demand growth into consistent earnings and market share gains.
Strategic Implications for Decision-Makers
Manufacturers should treat product certification, batch consistency, and application alignment as strategic assets rather than operational checkboxes. Investments that strengthen NSF/ANSI Standard 60 readiness, improve purity controls, and support formulation flexibility can help differentiate offerings in regulated procurement environments where compliance and reliability carry commercial weight. At the same time, building supply chain resilience through feedstock diversification, inventory planning, and regional sourcing options can reduce exposure to cost volatility and improve margin predictability. Companies should also evaluate whether modular or decentralized production models could add value in select geographies or customer segments where logistics and localized demand justify a different supply approach.
Investors should focus on the alignment between a company’s product mix, regulatory exposure, and end-use demand durability. Businesses with strong positions in water and wastewater treatment, robust certification infrastructure, and flexible feedstock handling are likely to capture demand more consistently over the forecast period. Equally important is assessing whether a target company’s competitive advantage is tied primarily to price competition or to application-specific value, service reliability, and compliance positioning. In this market, durable growth is increasingly associated with the ability to serve regulated, specification-driven segments rather than compete solely on volume.
PW Consulting
Procurement teams and downstream users should prioritize supply reliability, documentation transparency, and total treatment performance over narrow unit-cost comparisons. Given that certification requirements and feedstock-driven cost variability can influence both availability and pricing, contracting strategies that account for supply continuity, grade flexibility, and technical support may reduce operational risk. Evaluating suppliers on their ability to meet specification requirements consistently, manage delivery dependability, and adapt to evolving treatment goals can create more resilient procurement outcomes over time.
The broader takeaway is that the ferric chloride market is not simply expanding; it is evolving in ways that reward preparedness, compliance discipline, and application focus. Stakeholders who understand where demand is structurally strongest, how regulatory and feedstock dynamics affect cost and access, and which competitive strategies are most sustainable will be better positioned to act ahead of market shifts. For decision-makers seeking deeper segmentation detail, company-level benchmarking, and customized strategic scenarios across regions and applications, the full PW Consulting research report provides the additional granularity needed to translate these trends into concrete business moves.
For detailed analysis of this topic, please visit the official page: Ferric Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com