

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bus Validator Market: Why 9.7% CAGR Through 2032 Changes Everything

Strategic Trends and Commercial Opportunities in the Bus Validator Market
The bus validator market is entering a phase of sustained expansion, driven by the intersection of urban mobility modernization, payment technology evolution, and operational reliability mandates. With the market valued at approximately 3.26 billion USD in 2025 and projected to reach over 6.2 billion USD by 2032, the sector is on track for a compound annual growth rate of 9.7 percent across the 2026 to 2032 forecast window. This trajectory reflects more than incremental improvement; it signals a structural shift in how public transit agencies collect fares, manage passenger flow, and integrate hardware with cloud-based financial ecosystems.
The growth is not evenly distributed across all segments, and that unevenness itself is a source of strategic insight. Certain hardware configurations are outpacing others, while application contexts tied to public transportation dominate revenue generation. Regional dynamics further complicate the picture, with mature markets focusing on replacement cycles and smart upgrades, while emerging corridors prioritize foundational deployments. For enterprise decision-makers, the key question is no longer whether bus validators will continue to grow, but how to position around the specific drivers, constraints, and competitive moves that will shape profitable participation in the next cycle.
Market Snapshot: Scale, Trajectory, and Structural Imbalances
The market's scale and momentum are clear from the headline numbers. The 2025 baseline of 3258.09 million USD places the sector in a meaningful mid-stage growth position, with the 2032 projection of 6228.87 million USD indicating a near-doubling of revenue over seven years. A 9.7 percent CAGR suggests that adoption is being reinforced by recurring replacement demand, technology refreshes, and expanding fare collection mandates rather than a one-time infrastructure push.
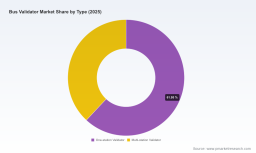
Beneath these totals, structural imbalances are already visible. One-station validators currently command a larger share of revenue than multi-station alternatives, pointing to a market where modular, single-point validation solutions remain the preferred choice for many deployments. At the same time, public transportation applications account for the dominant portion of revenue, underscoring that the core demand engine is municipal and regional transit rather than niche or auxiliary mobility use cases. Regionally, North America leads in market value, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but strategically notable corridors for future expansion.
Market concentration adds another layer of context. The top three players hold roughly 58.7 percent of the market, and the top five extend that share to about 68.4 percent. This level of concentration suggests that scale, installed base, and integration capabilities matter, but it also leaves meaningful room for specialized innovators, regional champions, and technology-led entrants to compete on features, service models, and total cost of ownership.
Core Challenges and Inflection Points
Despite the favorable trajectory, the market is navigating several operational and strategic pressure points. The first is the reliability-versus-complexity trade-off. Modern validators must support multiple payment methods, connectivity options, and environmental conditions, while still meeting demanding durability expectations. Public transit stakeholders increasingly expect validator systems to maintain at least 60 days mean time between failures for reliable service, a threshold that pushes manufacturers to strengthen hardware resilience, firmware stability, and field service support. As a result, product excellence is being redefined not just by functionality, but by sustained operational performance in harsh transit environments.
A second challenge lies in compliance and interoperability. Contactless transaction processing increasingly requires adherence to standards such as ISO/IEC 14443 for smart card readers and validators, while outdoor deployments demand ingress protection ratings like IP54 or IK07 to withstand exposure on moving vehicles. In parallel, fare collection installations must accommodate accessibility requirements, including ADA compliance for validator placement and usability. These overlapping mandates create a higher barrier to entry for generic hardware and reward manufacturers that can deliver standardized, specification-aligned solutions at scale.
The third inflection point is the shift from standalone hardware to connected, software-defined fare collection. Transit agencies are no longer buying validators as isolated devices; they are evaluating them as nodes within broader fare ecosystems that require remote monitoring, real-time maintenance, interoperability with mobile wallets and EMV payments, and integration with back-office platforms. This evolution places pressure on incumbents to modernize both product architecture and service delivery, while creating openings for vendors that treat the validator as part of a managed solution rather than a one-time capital purchase.
Key Drivers Shaping Market Dynamics
The market's expansion is being propelled by a set of reinforcing forces that go beyond general urban transit growth. Understanding these drivers helps clarify where demand will thicken, where margins may improve, and where competitive differentiation will matter most.
Technology Innovation and Feature Convergence
The strongest demand pull comes from the convergence of multiple validation and connectivity capabilities into compact, rugged form factors. Modern bus validators increasingly combine smart card reading, QR code scanning, contactless payment support, and wireless connectivity such as 4G, WiFi, and GPS relay functions. This convergence enables transit operators to serve passengers with diverse payment preferences while maintaining operational visibility and fleet-level data flow. Recent product announcements illustrate this direction: one major manufacturer highlighted new bus validator models designed for 2026 with enhanced smart terminal features, including Mifare readers, QR code scanners, and connectivity relays, alongside specialized functions such as student photo display for school bus applications. This kind of feature bundling reflects a broader market expectation that validators should be flexible enough to handle cash, smart cards, and contactless payments in a single device footprint.
Train Seat Market
Under the hood, processor choices also signal stability in the supply side. Validator designs commonly incorporate ARM9 and ARM-based processors, and current technical specifications indicate no recent supply chain constraints for these components. This is an important operational detail because processor availability directly affects production continuity, design refresh cycles, and cost predictability. Where core compute elements remain accessible, manufacturers can focus more on software maturity, certification, and service infrastructure rather than wrestling with foundational component shortages.
Policy and Regulatory Environment
Regulatory and procurement requirements are shaping both product design and purchasing decisions. Adoption of standardized technical specifications is accelerating, particularly around contactless transaction processing and environmental durability. The expectation that smart card readers and validators comply with ISO/IEC 14443 is becoming a baseline requirement in many tenders, reinforcing the importance of certified interoperability rather than proprietary-only solutions. Similarly, the push for IP54 or IK07 ratings on rugged bus validators reflects a pragmatic recognition that transit hardware must endure vibration, weather, and constant use.
Accessibility requirements are also influencing deployment specifications. Validator installations are increasingly expected to support ADA compliance, which affects not just hardware but placement, interface design, and serviceability. Meanwhile, reliability thresholds such as the 60-day MTBF expectation are moving from aspirational language into procurement criteria. These requirements do not merely constrain the market; they create competitive advantage for vendors that can demonstrate verifiable compliance, documented durability, and accessible design without sacrificing feature richness.
PW Consulting
Demand-Side Shifts in Consumer and Agency Behavior
On the demand side, passenger expectations are rising in tandem with broader digital payment habits. Riders increasingly expect fast, contactless, and mobile-friendly validators that reduce boarding friction and support multimodal travel patterns. Transit agencies, in turn, are seeking solutions that improve revenue assurance, reduce cash handling burden, and provide real-time operational data. This demand-side shift favors platforms that can support mobile wallets, EMV transactions, and cloud-based management, because the value proposition is no longer limited to validating a ticket at the point of entry. It extends to fare policy enforcement, auditability, and post-sale service management.
The dominance of public transportation as the primary application context reinforces this dynamic. Public transit agencies typically operate at scale, with standardized procurement cycles, strict reliability expectations, and long replacement horizons. That environment rewards vendors that can offer dependable hardware, interoperable payment support, and service models aligned with agency operations. It also means that even modest improvements in validator performance or fare system integration can translate into substantial aggregate value across large fleets.
Supply Chain and Cost Structure Considerations
Cost structures in this market are influenced by component stability, ruggedization requirements, and the growing importance of software and services. The availability of ARM-based processors without notable recent constraints helps preserve manufacturing continuity, but total cost of ownership is increasingly determined by more than bill-of-materials pricing. Agencies weigh factors such as field service frequency, remote maintenance capability, firmware update cycles, and the cost of downtime when evaluating validator solutions. As a result, vendors that can reduce maintenance burden and improve uptime through cloud-connected monitoring and scalable platform architecture are better positioned to compete on lifecycle economics rather than upfront hardware price alone.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established fare collection specialists, regional hardware manufacturers, and platform-oriented providers. The market's concentration suggests that scale and integration depth matter, but the diversity of recent moves indicates that leadership is being contested on multiple fronts: product breadth, cloud capability, deployment expertise, and regional reach.
Profiles of Key Players and Strategic Positioning
Scheidt & Bachmann GmbH, based in Mönchengladbach, Germany, specializes in fare collection systems including bus validators and fareboxes with next-generation solutions supporting cash, smart cards, and contactless payments. Its positioning leans toward integrated fare collection rather than isolated validator hardware, which gives it credibility with agencies seeking end-to-end system coherence. In February 2026, the company was selected by Pittsburgh Regional Transit for next-generation bus farebox modernization and validator hardware deployment, a move that underscores how incumbents with broad fare collection portfolios can secure high-visibility modernization contracts.
Krauth Technology GmbH, located in Eberbach, Germany, provides electronic ticket control devices and bus validators for indoor and outdoor use, including smart eTicketing and paper ticket systems. Its strategy appears oriented toward versatility in ticketing modalities and environmental adaptability, which can be especially relevant for operators that still handle mixed paper and electronic fare environments. By covering both electronic and paper-based validation, the company addresses transition scenarios where agencies are not yet fully paperless.
Cardlan Group, headquartered in Shenzhen, China, manufactures bus validators and smart ticket systems supporting Mifare cards, QR codes, 4G GPS, and contactless payments. Its recent activity highlights a product-led expansion approach. In February 2026, Cardlan announced a new start for 2026 bus validators with enhanced smart terminal features, including Mifare readers, QR code scanners, 4G/WiFi/GPS relay, and student photo display for school buses. This suggests a focus on feature-rich hardware that can serve both general transit and specialized fleet contexts, with an emphasis on connectivity and multimodal validation support.
Genfare, based in Elk Grove Village, Illinois, United States, offers bus validators and fare collection systems with cloud-based platforms supporting multiple payment types including mobile wallets and EMV. Its competitive angle is clearly tied to software and platform architecture. In May 2026, Genfare evolved its Link offering to a fully cloud-based SaaS model for improved scalability and real-time maintenance in fare collection systems including validators. This transition reflects a broader industry movement toward managed, remotely maintainable fare platforms, where the validator becomes part of a continuously updated service stack rather than a static device.
TransitFare, operating in the United States, produces rugged bus validators with RFID ticket validation and mobile ticketing capabilities for automated fare collection. Its profile emphasizes durability and mobile ticketing readiness, aligning with the operational reality that validators must survive demanding transit conditions while supporting modern rider authentication methods. This ruggedness-plus-mobility combination is a practical differentiator for agencies prioritizing reliability in outdoor deployments.
Differentiation Themes and Market Evolution
Across these players, several differentiation themes are emerging. One is the spectrum from hardware-centric to platform-centric offerings. Companies that can pair reliable validators with cloud management, remote diagnostics, and scalable payment support are building a stronger value proposition for agencies that want operational visibility and reduced maintenance friction. Another theme is modality breadth. Vendors that accommodate cash, smart cards, contactless payments, QR codes, and RFID in unified or interoperable form factors are better equipped to serve mixed-fleet and transition-period requirements. A third theme is ruggedization and compliance readiness. Given the expectation for IP54 or IK07 ratings, ISO/IEC 14443 compliance, and ADA-aligned installation practices, manufacturers that can document and deliver against these specifications gain procurement credibility.
The market is also showing signs of both consolidation and targeted fragmentation. Concentration remains significant, which favors incumbents with installed bases, proven integration track records, and the ability to support large-scale deployments. At the same time, the demand for specialized features, cloud platforms, and region-specific payment ecosystems creates space for focused players and new entrants that can compete on a specific capability, vertical, or geography rather than attempting to outscale the largest incumbents across every dimension. Recent contract awards, product launches, and platform updates suggest that competition is intensifying around modernization projects, feature refresh cycles, and service model innovation rather than pure volume pricing.
Apron Bus Market
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape how the bus validator market evolves and where commercial opportunities will concentrate.
Trend One: From Device Purchase to Managed Service Model
Validators will increasingly be evaluated as part of managed fare collection services rather than as standalone capital equipment. Cloud-based monitoring, real-time maintenance, remote firmware management, and scalable platform architecture are becoming central to procurement decisions. This shift creates opportunities for vendors that can offer lower total cost of ownership through better uptime, faster issue resolution, and continuous feature delivery. It also raises the stakes for hardware-only manufacturers that lack a credible software or services layer, because agencies may increasingly prefer integrated solutions that reduce operational burden across the fleet.
For commercial leaders, the implication is clear: roadmap planning should account for service attach rates, platform scalability, and remote diagnostics as core revenue and retention drivers, not optional add-ons.
Trend Two: Payment Convergence and Interoperability as Table Stakes
The validator market will continue moving toward unified support for multiple payment types, including contactless EMV, mobile wallets, smart cards, QR codes, and RFID-based validation. Interoperability with broader payment ecosystems will matter as much as raw device performance, because transit agencies are trying to accommodate rider preference while maintaining revenue integrity and operational simplicity. Compliance with relevant contactless standards and the ability to integrate cleanly with back-office fare systems will become expected capabilities rather than differentiators.
This trend opens opportunities for vendors that can demonstrate seamless payment interoperability, flexible configuration, and reliable transaction processing across mixed payment environments. It also introduces risk for products that are overly dependent on proprietary schemes or that lag in supporting widely used contactless and mobile payment methods.
Trend Three: Expansion in Specialized and Regional Deployment Contexts
While public transportation remains the dominant demand engine, specialized deployment contexts and regional expansion will provide meaningful growth pockets. School bus applications, for example, illustrate how validator functionality can be tailored to specific operational needs, such as student photo display alongside smart terminal features. Regional dynamics will also continue to diverge, with mature markets focused on modernization and replacement, and developing corridors pursuing foundational fare collection upgrades. These differing contexts reward vendors that can adapt product configurations, service models, and pricing structures to local requirements rather than applying a single global template.
The commercial opportunity here lies in segmenting offerings by use case and region, aligning feature sets with real operational needs, and building deployment expertise that reduces friction in new markets.
Risks and Uncertainties
Several risks could moderate the market's trajectory. Procurement cycles can be slow, and large transit modernization projects may face budget appropriations, political shifts, or operational delays. Standardization requirements, while beneficial for interoperability, can also raise compliance costs and lengthen time to market for new entrants. Reliability expectations are rising, which increases the penalty for field failures and puts pressure on quality assurance, service networks, and spare part logistics. In addition, payment ecosystem changes, cybersecurity expectations, and evolving accessibility requirements may continue to reshape technical specifications, requiring ongoing investment in certification and product updates.
These uncertainties do not undermine the market's growth outlook, but they emphasize that success will depend on execution quality, compliance readiness, and the ability to deliver dependable solutions in operationally demanding environments.
Actionable Recommendations for Decision-Makers
The bus validator market offers clear growth, but the most valuable positions will go to organizations that align their strategy with the market's operational realities and evolving service expectations. Recommendations vary by role, but all depend on timely, granular intelligence rather than broad market narratives alone.
For Manufacturers and Solution Providers
- Prioritize platform maturity alongside hardware performance. Cloud-based monitoring, remote maintenance, and scalable SaaS capabilities are becoming core purchase drivers, so product roadmaps should treat software and services as primary value components.
- Invest in compliance and ruggedization as competitive moats. Demonstrating alignment with contactless standards, ingress protection expectations, accessibility considerations, and reliability thresholds can shorten procurement cycles and improve win rates in public sector tenders.
- Prepare for mixed-modal reality. Many deployments will continue to handle cash, smart cards, contactless payments, and mobile ticketing in overlapping ways, so flexible configurations and interoperable architectures will be more valuable than narrowly optimized devices.
For Investors
- Focus on companies with defensible service models and integration depth. In a concentrated market, value often accrues to players that can combine installed base advantage with modern platform features, dependable support, and recurring service relationships.
- Track modernization cycles and regional expansion as leading indicators. Contract awards, platform updates, and feature launches in specific geographies can signal where demand is thickening before revenue data fully reflects the shift.
- Assess exposure to payment ecosystem evolution. Investments should consider how well target companies are positioned for contactless EMV, mobile wallets, and interoperability requirements, since these factors influence long-term relevance more than any single hardware feature.
For Transit Agencies and Procurement Leaders
- Evaluate total lifecycle cost rather than upfront device price. Reliability expectations, maintenance burden, remote diagnostics, and upgrade pathways can materially affect operational outcomes over the life of a deployment.
- Define compliance and accessibility requirements early. Clear specifications around contactless standards, environmental protection, and ADA-aligned installation practices help reduce integration risk and improve supplier comparability.
- Favor solutions that support future payment and service flexibility. Given the speed of change in rider payment behavior and fare system architecture, procurement choices should preserve options for multimodal support and software-driven enhancements.
Why Detailed Market Intelligence Matters Now
The strategic stakes in the bus validator market are rising because the growth is being shaped by overlapping technology, regulatory, and service-model shifts. High-level size and growth figures are useful for context, but they do not reveal where margins are improving, which configurations are winning procurement cycles, how regional demand is diverging, or which product and platform moves are likely to compound over the next several years. Decision-makers who rely only on aggregate market narratives risk misjudging segment attractiveness, competitive vulnerability, and the timing of modernization opportunities.
More detailed segmentation data, competitive tracking, and region-specific procurement context can materially improve planning quality. They help manufacturers prioritize feature investment, allow investors to distinguish durable differentiation from temporary momentum, and enable procurement teams to benchmark solutions against realistic operational requirements. In a market where reliability, interoperability, and service scalability are increasingly decisive, detailed intelligence is not just informational; it is a practical input to commercial execution.
For a deeper breakdown of segment dynamics, competitive developments, and regional procurement patterns, the full PW Consulting research report provides the structured detail needed to translate market trajectory into actionable strategy.
For detailed analysis of this topic, please visit the official page: Bus Validator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com