

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Food Dryer Market: Why the 6.85% CAGR Trajectory Changes Everything

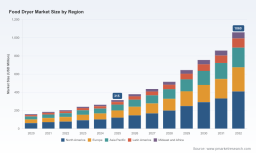
Navigating the Food Dryer Market: Strategic Shifts and Growth Horizons (2025–2032)
Market Landscape and Core Challenges
The global food dryer market has entered a phase of accelerated expansion, evolving from a mature processing niche into a strategic infrastructure component for food manufacturers, commercial kitchens, and emerging consumer wellness brands. Over the 2020–2025 period, the sector demonstrated consistent upward momentum, with revenue scaling steadily as drying technologies transitioned from utility-focused equipment to precision processing assets. Looking ahead to the 2026–2032 forecast horizon, the market is projected to follow a steep growth trajectory, driven by expanding applications in shelf-life extension, clean-label production, and decentralized food manufacturing. This progression signals more than incremental demand; it indicates a structural recalibration of how food processors approach moisture control, energy consumption, and product standardization.
Several macroeconomic and operational forces underpin this expansion. Food safety and traceability requirements continue to tighten across major trading blocs, pushing manufacturers toward equipment that can guarantee consistent moisture reduction and hygiene compliance. Simultaneously, the rise of alternative proteins, upcycled ingredients, and convenience formats has diversified the input materials requiring drying, creating demand for flexible, multi-stage drying architectures. Capacity investments in emerging processing hubs are also reshaping regional supply dynamics, while industrial digitization is redefining how drying lines are monitored, optimized, and maintained. Together, these forces are turning food dryers from passive processing tools into active nodes within broader food system resilience strategies.
Yet the sector is not moving through an unproblematic tailwind. The first major crossroads is regulatory and compliance complexity. Safety authorities now require stringent pre-heating protocols for meat and poultry-based dried products, alongside strict water activity thresholds for fruits and botanical ingredients. Equipment that cannot reliably demonstrate compliance with hygienic design standards, sanitation routines, or energy-efficiency mandates risks exclusion from global supply chains. Manufacturers and buyers alike must navigate divergent certification frameworks across jurisdictions, where organic certification, CE marking, and local GMP expectations may all apply simultaneously. This fragmentation increases testing, validation, and documentation costs, particularly for companies expanding across multiple markets.
The second challenge is the widening performance gap between equipment generations. Older convection-heavy lines often struggle to maintain uniform moisture removal across varied feedstock geometries, leading to inconsistent product quality and higher rework rates. In contrast, newer integrated systems leverage controlled airflow, multi-zone temperature profiling, and modular clean-in-place capabilities to improve repeatability. The challenge for operators is capital allocation: upgrading or replacing equipment requires clear ROI justification, especially when throughput gains are offset by higher initial investment and operator retraining. Companies that treat drying assets as long-term process enablers, rather than isolated purchases, are better positioned to manage this transition.
Food Dehydrators Market
A third pressure point lies in energy intensity and sustainability scrutiny. Drying remains one of the most energy-demanding unit operations in food processing, and efficiency expectations are rising from both regulators and downstream customers. Equipment that fails to align with emerging eco-design expectations or that lacks traceability for energy and utility consumption may face procurement disadvantages. For processors operating on thin margins, the balance between throughput, consistency, and operating cost has become a critical decision variable.
Key Growth Drivers
Technological Innovation and Process Precision
The market is being reshaped by a shift from single-function dryers to intelligent, modular drying systems. Advances in airflow control, multi-zone heating, and real-time monitoring are reducing variability across batches, which matters increasingly for products where flavor retention, texture, and shelf stability are tied directly to drying consistency. Digital integration is extending these gains. Process simulation and virtual modeling are being used to optimize spray and continuous drying configurations before physical deployment, helping operators reduce trial-and-error cycles and shorten commissioning timelines. At the equipment level, modular clean-in-place systems are becoming more prominent because they lower sanitation downtime and support frequent product changeovers in multi-use facilities. This trend is especially relevant for processors handling diverse feedstocks, where flexibility and hygiene assurance must coexist.
The practical implication is that drying technology is increasingly evaluated on total process value rather than unit price. Buyers are looking for systems that can reduce water activity predictably, maintain nutrient integrity where required, and integrate smoothly with upstream and downstream lines. Equipment that supports rapid sanitation, precise moisture endpoints, and adaptable tray or conveyor configurations is gaining preference in applications where product rotation is high or where specifications vary by client or region.
Policy and Regulatory Pressure as a Market Catalyst
Regulatory developments are functioning less as barriers and more as structural demand drivers. Safety guidance increasingly mandates specific pre-heating steps for animal-protein-based dried products and defines water activity thresholds for fruits, herbs, and other perishable inputs to suppress microbial growth. These requirements are not optional nuances; they determine whether a facility can legally ship product through major distribution channels. At the same time, equipment standards are tightening around hygienic design, sanitation compatibility, and energy performance. Manufacturers that align their drying systems with recognized GMP expectations, regional certification pathways, and eco-design principles are gaining smoother market access, while laggards face longer validation cycles and reduced buyer confidence.
For exporters and multi-site operators, the regulatory environment rewards standardization. Facilities that design drying processes around defensible safety parameters and documented equipment compliance can reduce audit friction, expand into new markets faster, and avoid costly last-minute retrofits. Conversely, companies relying on legacy configurations without clear compliance pathways face growing operational risk, particularly as procurement teams increasingly ask for sanitation and safety documentation during vendor evaluation.
Demand-Side Shifts Across Consumer and Commercial Segments
Demand is expanding beyond traditional industrial dehydration into adjacent use cases that were previously underserved. Consumer-facing interest in long-shelf-life snacks, dried produce, herbal ingredients, and specialty pet treats is encouraging smaller processors and brand builders to invest in compact or mid-scale drying capacity. At the same time, commercial kitchens, co-manufacturers, and regional food brands are adopting drying as a way to stabilize seasonal supply, reduce waste, and extend distribution range. This broadening demand base is creating a two-tier market dynamic: large industrial lines continue to anchor high-volume ingredient and powder production, while smaller, digitally controlled units are gaining relevance for specialty, batch-oriented, or locally branded products.
The commercial implication is that drying equipment is no longer a single procurement category. It now spans high-throughput industrial configurations for ingredient and protein processing, mid-capacity systems for snack and bakery production, and compact multi-tray units for herbs, fruits, and direct-to-consumer or local brand applications. Companies that can serve multiple tiers with appropriately scaled solutions are capturing demand that was previously fragmented across informal or semi-industrial channels.
Supply Chain, Cost Structure, and Capacity Realignment
Cost pressures are reshaping procurement and capacity strategies. Energy volatility, material availability, and labor constraints are encouraging processors to prioritize equipment that delivers faster ramp-up, lower downtime, and more predictable operating profiles. In parallel, regional capacity builds are influencing where drying assets are deployed. As processing moves closer to sourcing regions or to demand centers with favorable logistics, dryer lines must accommodate different feedstock qualities, ambient conditions, and utility profiles. This is pushing equipment suppliers and buyers toward modular designs that can be tuned for local operating environments rather than relying on one-size configurations.
The broader effect is a stronger emphasis on total cost of ownership. Depreciation alone is no longer the dominant procurement lens. Operators are weighing sanitation cycle length, cleaning compatibility, changeover speed, energy consumption per unit output, and serviceability. These variables often determine whether a system can sustain margin through fluctuating input costs or high-mix production schedules. In that context, drying equipment is increasingly evaluated as a throughput-and-compliance asset rather than a simple thermal device.
Competitive Landscape and Leading-Player Strategies
The competitive field is defined by a mix of established industrial equipment providers, application-focused manufacturers, and specialists serving commercial and compact drying segments. The market remains moderately concentrated, with a core group of larger players holding significant share, but its structure is not static. Differentiation is increasingly determined by application fit, process integration capability, sanitation efficiency, and the ability to offer defensible compliance pathways.
Industrial-scale players are reinforcing their positions by embedding drying into broader processing architectures. Companies supplying spray and continuous drying technologies are focusing on ingredient, dairy, and powder applications where consistency, throughput, and hygiene are paramount. Their strategic advantage lies in the ability to align drying with upstream formulation and downstream packaging or storage requirements, reducing line fragmentation and improving end-product repeatability. In this tier, competitive edge is increasingly tied to process engineering depth, service networks, and the capacity to support compliance documentation across multiple geographies.
A second cluster of competitors is anchored in fruit, vegetable, snack, and bakery drying. These manufacturers compete on configuration flexibility, multi-pass and static drying options, and the ability to handle delicate or shape-sensitive materials without compromising output quality. Their positioning often centers on specialized airflow designs, changeover adaptability, and equipment that can be integrated into continuous or semi-continuous production lines. For buyers in these categories, the focus is less on raw capacity and more on texture preservation, color retention, and dependable moisture endpoints across varied product runs.
Commercial Food Dehydrators Market
A third competitive layer serves commercial and compact dehydration needs, including multi-tray dehydrators, digital-controlled units, and high-capacity commercial drying spaces. These players are expanding functionality through improved controls, tray configurations, and product-change versatility. Their relevance is growing as smaller producers, local brands, and specialty operations seek professional-grade drying without committing to large industrial installations. In this segment, usability, sanitation practicality, and consistent performance across smaller batch sizes are key differentiators.
Recent product and process developments illustrate how competition is evolving. Modular clean-in-place systems have been introduced to improve sanitation efficiency on drying-related process equipment, reflecting an industry-wide push to reduce downtime and support frequent changeovers. Digital control enhancements and expanded tray configurations are broadening commercial drying capacity, while process optimization tools such as digital twin modeling are being applied to improve ingredient drying performance and reduce tuning time. In parallel, advances in continuous powder drying technologies are strengthening throughput and consistency for high-volume applications. These developments point to a common direction: competitors are seeking to win by lowering operational friction, improving repeatability, and making drying systems easier to validate and maintain.
The landscape is also susceptible to consolidation and selective entry. Larger players with integrated processing portfolios are well placed to acquire or partner with specialists in adjacent drying technologies, especially where hygiene, automation, or compliance support creates a meaningful barrier. At the same time, new entrants can still find opportunities by targeting underserved application niches, regional demand pockets, or compact-to-mid-scale commercial segments where service and usability matter as much as raw capacity. The likely trajectory is a hybrid market: concentrated leadership at the industrial end, continued fragmentation and specialization in mid-scale and commercial layers, and growing importance of suppliers who can bridge drying with broader process and compliance requirements.
Forward Trends and Commercial Opportunities
Precision, Modularity, and Process Integration as Default Expectations
Over the next three to five years, drying systems are likely to be judged increasingly on integration and precision rather than isolated capacity. Multi-zone control, modular sanitation design, and digital monitoring will become baseline expectations in applications where product variability is high or where facilities must process multiple feedstocks on shared lines. This creates an opportunity for equipment strategies that emphasize flexible capacity, predictable moisture endpoints, and easy documentation for safety and quality audits. Buyers who standardize around these capabilities can reduce rework, improve changeover economics, and strengthen market access for products that require demonstrable drying consistency.
PW Consulting Automotive & Machinery Research Center
Compliance-Linked Equipment Selection Gaining Procurement Weight
Safety and eco-design expectations are poised to become more central in sourcing decisions. Procurement teams are likely to place greater weight on equipment that can demonstrate hygienic design compatibility, manageable sanitation routines, and defensible energy performance. This trend favors vendors and operators who can provide clear compliance narratives and support multi-jurisdiction certification pathways. For exporters and multi-site processors, this is both a risk management and growth opportunity: standardized, well-documented drying processes can accelerate market entry and reduce the operational drag of repeated validation cycles.
Segmentation Between Industrial Scale and Agile Commercial Capacity Intensifying
The market is likely to see a stronger structural split between high-volume industrial drying and agile, smaller-scale capacity. Industrial lines will continue to evolve around ingredient, dairy, powder, and protein applications where throughput and repeatability dominate. At the same time, compact-to-mid-scale systems will expand as brands, co-manufacturers, and regional processors seek decentralized drying for seasonal supply, waste reduction, and product differentiation. This bifurcation creates a dual opportunity: industrial players can capture value through broader line integration and process services, while commercial-focused suppliers can grow by offering controllable, user-friendly systems that fit smaller footprints and varied product mixes.
Across these trends, the key commercial risk is overinvestment in non-adaptive configurations. Equipment that cannot accommodate changing feedstock, evolving safety requirements, or rising energy expectations may become a liability rather than a productivity asset. Likewise, companies that underestimate documentation, sanitation complexity, or regional certification differences may face delayed launches and procurement friction. The upside belongs to operators and suppliers who treat drying as a flexible, compliance-ready process layer rather than a fixed hardware purchase.
Strategic Actions for Decision Makers
For Equipment Manufacturers and Process Suppliers
Position drying systems as integrated process solutions rather than standalone thermal units. Emphasize sanitation efficiency, changeover adaptability, and control precision in product roadmaps, and align development with regulatory expectations that shape buyer purchasing criteria. Where possible, support customers with documentation, commissioning guidance, and service models that reduce validation and maintenance friction. Differentiation will increasingly come from how easily a system fits into multi-product operations and how confidently it supports safety and quality compliance.
- Prioritize modular architectures that allow airflow, capacity, and sanitation configurations to be tuned for different feedstock and facility profiles.
- Strengthen service, training, and compliance documentation as core revenue and retention enablers, not ancillary support functions.
- Track eco-design and safety mandates early so product updates can anticipate procurement requirements rather than react to them.
For Investors and Growth-Focused Buyers
Evaluate the drying sector with a focus on application adjacencies, regional demand formation, and total-cost economics rather than headline capacity alone. Capital and acquisition opportunities are likely to emerge where companies can combine drying technology with integration capabilities, service reach, or niche application expertise. In parallel, watch for supplier consolidation in industrial segments and growth in agile commercial-scale capacity, as both pathways can reshape competitive dynamics.
- Assess target companies on process integration depth, compliance readiness, and the ability to serve multiple drying segments, not solely on equipment specs.
- Factor operating cost dynamics into valuation logic, including sanitation cycle time, energy intensity, and serviceability across mixed production schedules.
- Monitor regional capacity shifts that may change where drying assets are most valuable in the supply chain.
For Procurement Teams and End-Use Operators
Standardize drying procurement around repeatability, sanitation practicality, and compliance documentation. When evaluating options, compare total operating impact rather than purchase price: consider changeover speed, moisture consistency, cleaning compatibility, and how well the system aligns with safety requirements for the specific products being processed. Where production is multi-product or export-oriented, favor configurations that simplify audit readiness and reduce rework risk.
- Define drying specifications by product safety and quality requirements first, then map equipment features to those outcomes.
- Include sanitation, documentation, and energy performance in request-for-quote criteria to avoid hidden operational costs.
- Build flexibility into capacity planning so drying lines can accommodate seasonal variation, feedstock differences, and new product introductions without major retrofit cycles.
Closing Perspective
The food dryer market is moving through a transition in which drying technology is becoming more central to product quality, regulatory readiness, and operational resilience. Growth is being driven by a combination of process innovation, compliance expectations, expanding demand across industrial and commercial segments, and a broader revaluation of equipment around total cost and integration value. The competitive field reflects this shift: leadership is increasingly defined by application fit, hygiene performance, flexibility, and the ability to support buyers through complex compliance and operating environments.
For organizations deciding how to position themselves, the strategic question is less about whether drying capacity is needed and more about which drying archetype matches the product mix, safety requirements, and growth path at hand. Detailed segmentation, regional nuances, and company-level benchmarking can materially improve capital and sourcing decisions, especially where multiple drying technologies, certification pathways, and application profiles intersect. For those seeking a deeper look at those variables, the full research report provides expanded segmentation detail, competitive benchmarking, and tailored decision support beyond the strategic overview presented here.
For detailed analysis of this topic, please visit the official page: Food Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com