

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Offset Printing Plate Market: How Asia Pacific's 79M Share Reshapes Long-Term Outlook

Digital Offset Printing Plate Market: Strategic Trends & Commercial Opportunities Beyond 2025
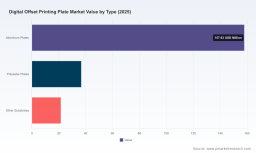
The digital offset printing plate market stands at a critical inflection point, shaped by the intersection of sustainability mandates, material science breakthroughs, and shifting print volumes across commercial and packaging applications. Described by a base-year valuation of USD 216.1 million in 2025 with a compound annual growth rate of 2.35 percent projected through 2032, the market reflects a measured but sustained expansion trajectory. Historical progression from 2020 to 2025 reveals a modest recovery from pandemic-era disruptions before stabilizing into a period of incremental growth. Forward-looking projections show volatility across near-term years, including a slight contraction in 2028 before resuming upward momentum, signaling a landscape defined less by linear growth and more by periodic realignment as pricing pressures, regulatory execution, and substrate innovation reshape buyer priorities.
For executives, investors, and procurement leaders, the narrative is no longer about market size alone. The strategic question centers on where value is being created as the industry transitions toward chemistry-free workflows, waterless imaging alternatives, and integrated final-exposure systems. This analysis maps the structural forces driving change, the competitive positioning of incumbents and specialists, and the actionable implications for stakeholders navigating the next cycle of investment, sourcing, and product strategy.
Market Context & Core Challenges
The current market is characterized by technological maturation rather than breakthrough expansion. The steady pace of growth masks underlying complexity: while aluminum-based formats continue to anchor production value due to their durability and consistent run-length performance, the broader ecosystem is being recalibrated by environmental compliance costs, substrate diversification, and operational efficiency demands. Prices are under pressure from raw material volatility, while demand patterns shift as packaging converters prioritize flexible, high-speed workflows and commercial printers consolidate around shorter-run, high-quality output models. The competitive environment reflects moderate concentration, with a small group of established players and emerging specialists carving out defensible niches. This structure rewards firms that can translate innovation into workflow integration and regulatory readiness.
Three challenges dominate the near-term agenda. First, regulatory tightening is reshaping the cost and compliance architecture of plate manufacturing and imposition. Standards governing chemical exposure, solvent handling, and waste management have moved from peripheral considerations to core operational requirements, forcing suppliers to redesign formulations and production protocols. Second, substrate performance trade-offs remain a persistent friction point. While aluminum continues to deliver superior print consistency for demanding packaging runs, alternative substrates face ongoing questions around scratch resistance, dimensional stability, and compatibility with advanced curing chemistries, constraining adoption in high-value applications. Third, the market is experiencing demand fragmentation across segments. Packaging continues to absorb a significant share of output, but commercial printing and periodical applications are subject to rapid volume swings as digital alternatives and on-demand models compress traditional run lengths. These dynamics require suppliers and buyers alike to align capacity, product mix, and service models with more volatile demand signals.
Key Drivers of Market Evolution
Technology Innovation And Imaging Breakthroughs
Advancements in thermal and photopolymer imaging are redefining performance expectations for digital offset plates. Next-generation thermal formats are delivering sharper image transfer, improved chemical resistance, and better handling of variable exposure environments, enabling printers to reduce scrap rates and maintain quality across mixed-material jobs. In parallel, improvements in photopolymer structures and violet imaging chemistries are extending run lengths and improving cure compatibility, particularly for UV-enabled packaging and label work. These technical gains are being reinforced by process-free and chemistry-free formulations that remove the need for wet-processing steps, simplifying pressroom operations while reducing consumable waste and operator exposure. The strategic implication is clear: plate performance is increasingly judged not only by output quality but by total workflow efficiency, including setup time, processing complexity, and compatibility with integrated imaging systems.
PW Consulting
Regulatory And Compliance Pressures
Environmental and safety regulations are no longer passive constraints; they are active design parameters. Frameworks governing chemical substances have compelled manufacturers to reduce hazardous emissions, minimize waste streams, and formalize material handling procedures throughout the production lifecycle. Compliance has become a competitive differentiator for suppliers that can demonstrate process-free operation, lower chemical footprints, and documented waste management practices. In parallel, occupational safety expectations around photopolymer handling and solvent use have raised the bar for supplier-support programs, technical documentation, and pressroom training. These shifts are accelerating market acceptance of greener plate technologies, with eco-label certifications and sustainability criteria increasingly influencing procurement decisions across regional and multinational print operations.
Flexographic Printing Plate Market
Demand-Side Shifts In Consumer And Enterprise Behavior
Demand structures are being reshaped by the rise of shorter production runs, personalized packaging, and brand-driven print differentiation. Packaging converters and commercial printers alike are seeking plates that support rapid job changes, strong scratch resistance, and consistent performance across diverse substrates and ink systems. As brands invest more in tactile packaging finishes, label sophistication, and limited-edition runs, the need for plates that can balance speed with image fidelity is intensifying. At the same time, digital substitution continues to pressure longer-run commercial volumes, pushing print service providers to compete on flexibility and quality rather than volume alone. This environment favors plate technologies that enable faster setup, lower chemistry dependency, and reliable performance on demanding runs, while also rewarding suppliers that can help customers reduce waste and operational cost per impression.
Supply Chain And Cost Structure Dynamics
Cost pressure remains a persistent force, amplified by aluminum volatility, processing chemistry inputs, and the operational expense of compliance. Suppliers are responding through formulation optimization, streamlined processing requirements, and greater emphasis on durability to reduce total cost of ownership. Buyers are increasingly weighing lifecycle economics over unit price, considering factors such as scratch resistance, handling robustness, and consumable savings from process-free designs. The net effect is a shift toward value-based evaluation, where performance consistency and workflow integration can offset raw material fluctuations. This dynamic also encourages consolidation of supplier relationships and technical support, as customers look for partners that can standardize product performance across locations and reduce the complexity of maintaining multiple plate formats.
Competitive Landscape And Strategic Positioning
The competitive environment is defined by a mix of large-incumbent capabilities and specialized technical differentiation. Several established players have focused on thermal digital offset plates for commercial and packaging work, emphasizing image sharpness, chemical resistance, and compatibility with next-generation imaging systems. Others have built strong positions in process-free and chemistry-free formats, leveraging proprietary technologies to reduce wet-processing needs and improve scratch resistance. A third group has pursued waterless and eco-friendly plate architectures aimed at lowering chemical use and environmental impact in offset workflows, particularly for packaging. Some suppliers are extending beyond plate materials into integrated imaging and press solutions, creating tighter coupling between plate format and on-press imaging workflows. Across the field, differentiation is increasingly tied to durability, workflow compatibility, regulatory readiness, and the ability to reduce total processing cost.
Recent developments illustrate how these firms are executing against the market's structural forces. In early 2025, one major supplier introduced a next-generation thermal digital offset plate designed to improve image sharpness and chemical resistance for commercial and packaging applications, aligning with the broader push toward sharper transfer and more robust handling. Later in 2024, another leading manufacturer launched an advanced photopolymer plate with improved durability and stronger compatibility with UV-curable inks, addressing the growing demand for high-performance packaging and label workflows. Third, a strategic partnership announced in mid-2024 between a plate specialist and a global printing equipment manufacturer signaled a move toward co-developed integrated plate and imaging systems, aiming to streamline offset workflows and reduce integration friction. Finally, an eco-focused brand introduced a process-free plate with enhanced contrast, scratch resistance, and cost savings for commercial printing, reinforcing the trend toward chemistry-free formats that lower operational complexity.
These moves reflect broader competitive patterns. Incumbents are strengthening technical performance while embedding sustainability into product definitions, using process-free chemistries and waterless options to address regulatory and cost pressures. Specialists are competing on differentiation, targeting packaging durability, label compatibility, and reduced chemical exposure. The rise of integrated system partnerships suggests a shift toward ecosystem-based value creation, where plate performance is judged alongside press readiness, imaging stability, and total workflow efficiency. Market evolution is likely to continue along two parallel paths: consolidation among players seeking scale and broad format coverage, and continued fragmentation among firms pursuing deep specialization in high-value applications or sustainable processing.
Worldwide Printing Plate Market
Future Trends And Commercial Opportunities (2026–2032)
The market's trajectory over the next several years will likely be shaped by three overlapping trends.
Sustained adoption of process-free and low-chemistry plate formats. As regulatory expectations solidify and pressroom cost pressures persist, demand is expected to tilt further toward plates that eliminate or reduce wet-processing steps. The commercial opportunity lies in building supply capability around durable, scratch-resistant, chemistry-light formats that reduce consumables, simplify operator procedures, and lower exposure risk. Suppliers that can pair these formats with strong technical support and workflow documentation will be better positioned to capture value in regulated and cost-sensitive environments.
Integration of plate and imaging systems for workflow efficiency. The push toward seamless offset workflows is likely to intensify as printers seek to reduce setup variability and improve run consistency. Opportunities are emerging for companies that can co-design plate specifications with imaging systems, standardize exposure protocols, and reduce compatibility risks across equipment fleets. This trend rewards partnerships, modular product architectures, and service models that address the entire imaging chain rather than isolated consumables.
Substrate diversification and packaging-specific performance gains. While aluminum substrates remain central, the market is likely to see continued experimentation with alternative formats where durability, dimensional stability, and ink compatibility can be proven at scale. The commercial opportunity is concentrated in packaging and label applications where run quality, scratch resistance, and chemistry compatibility directly influence conversion efficiency and customer acceptance. Firms that can deliver packaging-grade performance with reduced environmental footprint will have a clearer path to premium positioning.
These trends carry uncertainty. Pricing volatility in raw materials may compress margins if cost savings from process-free designs are not fully realized in the field. Demand fragmentation across commercial and periodical segments may create overcapacity risk if volume assumptions are misaligned with actual run-length trends. Regulatory interpretations can also diverge across regions, creating uneven compliance costs and slowing adoption of certain formulations. Stakeholders should treat these variables as design constraints for capacity planning, product mix, and supplier selection rather than static assumptions.
Actionable Recommendations For Decision Makers
For manufacturers and plate suppliers: Prioritize process-free and chemistry-light development as a core product strategy rather than a marginal offering, and pair formulation advances with measurable claims around scratch resistance, handling durability, and total processing cost. Invest in integration readiness by aligning plate specifications with imaging and press workflows, and build technical support programs that help customers standardize performance across sites. Track regulatory developments closely and treat compliance capability as a market-entry requirement, especially where chemical handling and waste management expectations are tightening.
For investors: Focus on value creation potential rather than raw volume growth. Evaluate companies by their ability to deliver workflow-integrated solutions, sustainable-processing formats, and packaging-grade performance with defensible cost profiles. Watch for partnership activity that signals ecosystem expansion, as integrated plate-and-imaging playbooks may create stronger customer lock-in and margin resilience. In parallel, assess exposure to raw-material volatility and the degree to which cost savings are embedded in total cost of ownership claims rather than unit pricing alone.
For procurement teams and print service providers: Shift sourcing decisions toward total workflow economics, including processing complexity, consumable usage, setup efficiency, and damage resistance under handling and production stress. Prioritize formats that reduce chemistry dependency where feasible, and request documented performance consistency across multiple run lengths and substrate conditions. Where feasible, consolidate supplier relationships around formats that standardize exposure protocols and simplify pressroom training, reducing operational friction while maintaining quality standards.
For stakeholders seeking a more detailed view of segment dynamics, regional demand structures, competitive share breakdowns, and pricing scenarios across the forecast horizon, a full market study can provide the granular benchmarks required for product planning, investment modeling, and sourcing decisions. The broader market signals are clear: the digital offset printing plate landscape is shifting from volume-based growth toward performance, sustainability, and workflow integration. Organizations that act on these signals with clear product and sourcing strategies will be better positioned to capture durable value in the years ahead.
For detailed analysis of this topic, please visit the official page: Digital Offset Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com