

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Smart Thermostats Market 2026: Beyond the 15.05% CAGR Growth Trajectory

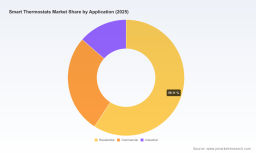
The Smart Thermostats Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global smart thermostats market has transitioned from a niche convenience segment to a foundational component of connected home and building energy management. Valued at approximately $4.94 billion in 2025, the market has expanded from $2.21 billion in 2020, reflecting a compound annual growth rate of 15.05% projected through 2032, when revenues are expected to reach $13.18 billion. This trajectory signals more than consumer interest; it reflects a structural shift in how heating, ventilation, and air conditioning systems are optimized, monitored, and integrated into broader energy ecosystems. For executives, investors, and procurement leaders, the window to shape positioning is narrowing as connectivity standards, regulatory frameworks, and AI capabilities accelerate simultaneously.
Market Snapshot and Structural Shifts
The revenue path from 2020 through 2032 illustrates a market gaining momentum rather than merely recovering from earlier volatility. Growth accelerated notably around 2024–2025, with the base year marking a step change in adoption intensity across residential and commercial environments. The forecast period to 2032 suggests continued expansion, though the pace will increasingly hinge on how quickly interoperability, installation friction, and data governance concerns are resolved. Market concentration remains moderately fragmented at the top, with the three largest players holding roughly 37.5% of share and the top five accounting for about 48.0%. This distribution leaves meaningful room for regional specialists, ecosystem-driven entrants, and companies that can narrow the gap between premium intelligence features and accessible price points.
Several structural tensions define the current environment. First, the market is navigating a shift from standalone device sales toward integrated service and software value, where recurring energy savings, predictive maintenance, and ecosystem lock-in begin to matter as much as hardware margins. Second, installation complexity and legacy HVAC compatibility continue to create friction in broader residential rollouts, pushing manufacturers to design for retrofit ease without sacrificing performance. Third, differing regional approaches to connectivity oversight and energy efficiency standards are shaping product roadmaps unevenly, requiring companies to balance unified global platforms with localized compliance and pricing strategies. These dynamics create both risk and differentiation potential for players that act early.
Core Drivers Reshaping Demand and Competition
Technology Innovation and the Move Toward Predictive Control
The most durable driver is the maturation of AI-enhanced learning, occupancy sensing, and adaptive scheduling. Devices are no longer limited to remote control via mobile applications; they are increasingly capable of recognizing usage patterns, adjusting to weather forecasts, and coordinating with ventilation or air quality sensors. Recent product introductions reflect this shift toward intelligence that is both more responsive and more accessible. In January 2025, ecobee launched the Smart Thermostat Essential at CES 2025, offering adaptive learning and mobile app control at a more accessible price point, signaling that predictive features are being brought down-market rather than reserved for premium tiers. A few months later, Alarm.com introduced the ADC-T25 Smart Thermostat, emphasizing cost-efficiency, advanced HVAC control, and simplified installation for broader residential adoption. These launches illustrate a dual strategy: expand the installed base through easier deployment while retaining differentiated algorithms that improve comfort and efficiency over time.
Policy and Regulatory Environments as Demand Catalysts
Policy momentum continues to shape purchasing behavior, particularly where energy efficiency mandates, incentive programs, and certification labels lower the effective cost of adoption. ENERGY STAR certification and Matter compatibility have become practical signals for both consumers and commercial specifiers, reducing uncertainty around interoperability and verified savings. At the same time, the broader connectivity environment is not uniform. In January 2025, the U.S. Court of Appeals for the Sixth Circuit struck down the FCC’s 2024 Open Internet Order, reclassifying broadband as an information service and ending federal net neutrality oversight. Several states, including California, Washington, Oregon, and Vermont, have maintained statewide net neutrality requirements that restrict ISP blocking, throttling, or prioritization of broadband traffic. The ruling also left Congress as the primary pathway for new federal legislation on broadband access. For smart thermostat providers, the practical implication is that residential and commercial connectivity assumptions cannot be taken for granted; product architectures must remain resilient across varying ISP practices, and go-to-market strategies may need to account for regional differences in network treatment and reliability expectations.
Demand-Side Behavior and Building Operations Priorities
On the demand side, residential buyers increasingly view smart thermostats as part of a wider smart home investment tied to comfort, air quality, and energy cost management. In commercial and industrial settings, the emphasis shifts toward integration with building automation systems, occupancy-based scheduling, and centralized control across multiple zones. Recent product activity underscores this bifurcation. In March 2026, Carrier launched the Smart Thermostat Advanced and enhanced Smart Thermostat models with InteliSense technology and a ComfortAdjust feature tailored for Performance Series heat pumps, reinforcing the value of system-specific optimization in higher-end residential and light commercial applications. Meanwhile, companies focused on hospitality and multi-site building environments have continued to emphasize no-door-interface designs and occupancy-based control to reduce manual adjustments and standardize environmental performance across properties. The commercial segment’s growth is increasingly tied to operational outcomes—fewer service calls, more consistent zone control, and better alignment between HVAC runtime and actual occupancy—rather than device novelty alone.
Supply Chain and Connectivity Cost Structures
Behind the product conversation, connectivity remains a structural cost factor. Broadband infrastructure represents the primary ongoing cost for smart thermostat data connectivity and cloud services, which means that subscription pricing, data handling architecture, and device-side processing design directly influence long-term margin profiles. Manufacturers that can reduce dependency on continuous heavy cloud processing—through smarter edge logic or more efficient scheduling algorithms—may gain flexibility in pricing and resilience against connectivity cost pressure. At the same time, component availability, platform certification cycles, and the cost of maintaining broad HVAC compatibility all shape time-to-market and portfolio breadth. The companies that manage these inputs well are increasingly those that treat connectivity not as an afterthought but as a core design constraint, balancing feature richness with sustainable service economics.
WiFi Thermostats Market
Competitive Positioning and the Evolution of the Market Map
The competitive field blends established home automation names, traditional HVAC and building technology players, and specialist firms with deep application focus. Google LLC continues to emphasize AI-driven learning and voice control through the Nest Learning Thermostat (4th generation), aligning residential smart thermostat adoption with wider smart home integration. ecobee Inc. has built its positioning around air quality sensing, predictive learning, and broad ecosystem compatibility, with its Essential launch reinforcing a tiered approach that spans premium and value-conscious buyers. Honeywell International Inc. has leaned into Matter compatibility, dual-band connectivity, and ENERGY STAR certification across its T9, X8S, and X2S Wi-Fi Smart Thermostats, highlighting standards alignment as a trust signal. Amazon.com, Inc. offers an app-based and voice-integrated thermostat developed in partnership with Resideo Technologies, leveraging distribution and voice ecosystem reach rather than attempting to lead on standalone HVAC engineering. Emerson Electric Co. focuses on the Sensi Touch and Sensi series with Alexa integration, touch interfaces, and broad HVAC compatibility, creating a practical middle ground between advanced features and installation flexibility.
In the commercial and industrial direction, Johnson Controls International plc emphasizes building automation system integration, while Carrier Global Corporation pursues system-specific optimization through InteliSense technology and humidity control in its Infinity System Control and Smart Thermostat portfolio. Schneider Electric SE extends connected home solutions through IoT platform integration, and Resideo Technologies, Inc. continues to develop Honeywell Home-branded models such as the X2S and X8S with advanced AI and smart home features; its January 2025 introduction of the Honeywell Home X2S at CES 2025, featuring Matter compatibility and ENERGY STAR certification, reflects the same interoperability emphasis seen across the broader field. Specialist entrants add application depth: Tado GmbH focuses on occupancy sensing and precise heating and cooling optimization with its V3+ and Sense devices, while Verdant Solutions LLC, operating under Copeland, targets commercial hotel and building applications with VX and VX4 thermostats designed around no-door-interface interaction and occupancy-based control.
The landscape is evolving along three overlapping vectors. First, interoperability and standards alignment are becoming table stakes, with Matter compatibility and ENERGY STAR certification increasingly expected rather than optional differentiators. Second, there is a subtle fragmentation between broad-platform players and application specialists, with the latter competing on installation simplicity, zone-specific control, and vertical workflow fit rather than general feature count. Third, the market is seeing consolidation pressure at the edges, where device-only businesses may struggle to defend margins unless they attach software value, service relationships, or integration partnerships. Companies that can combine credible HVAC compatibility, standards-aligned connectivity, and clear operational benefits are best positioned to expand share without relying solely on price competition.
Forward Outlook: Three Trends to Track Through 2032
The next three to five years are likely to be defined by a shift from device adoption to integrated optimization. The first trend is the normalization of predictive and occupancy-aware control as baseline expectations rather than premium extras. As adaptive learning, sensor integration, and weather-responsive scheduling become more common, value will shift toward accuracy, low-friction setup, and measurable energy outcomes. Manufacturers that can demonstrate consistent savings across varied housing types and HVAC configurations will have stronger positioning in both retail and specification channels.
PW Consulting
The second trend is deeper integration with broader building and home ecosystems. Smart thermostats are increasingly evaluated alongside air quality monitors, ventilation controls, voice platforms, and centralized management dashboards. In commercial environments, this points toward more unified building automation interfaces and occupancy-driven scheduling that reduces manual intervention across multiple zones. The commercial opportunity lies not in selling more devices per se, but in enabling operators to manage comfort, runtime, and maintenance more efficiently through a single coordinated layer.
The third trend is regulatory and connectivity-driven fragmentation in market access. With federal net neutrality oversight ended in January 2025 and several states maintaining their own rules, broadband treatment is no longer uniform, and Congress remains the only clear path for new federal legislation. Combined with the fact that broadband infrastructure underpins the ongoing cost of data connectivity and cloud services, this environment favors designs and business models that can tolerate variability in network conditions and that do not depend on a single connectivity assumption. Companies should anticipate that product roadmaps, pricing structures, and service commitments may need to be adapted regionally rather than deployed identically across all markets.
These trends create opportunity, but also uncertainty. Adoption may be moderated where installation complexity remains high, where older HVAC systems limit feature compatibility, or where consumers and building operators are slow to trust algorithmic control without clear proof of savings. Regulatory shifts, standards evolution, and connectivity cost pressure could also reshape margin expectations over time. The most resilient strategies will be those that treat these uncertainties as design inputs rather than external shocks.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Prioritize interoperability and installation simplicity as simultaneous growth levers. Standards alignment, broad HVAC compatibility, and reduced setup friction expand the addressable base, while differentiated intelligence features protect margin and build loyalty. Consider how much control logic can be handled on-device to manage long-term connectivity and cloud service costs, and structure product tiers so that predictive features are accessible without undermining premium positioning. Where feasible, design for integration with wider home or building automation workflows rather than competing solely on isolated device performance.
Thermostats Market
For Investors and Strategic Capital Allocators
Look for businesses that demonstrate durable value beyond initial hardware sales. Recurring savings verification, software-enabled differentiation, and ecosystem relationships often signal stronger long-term economics than feature parity alone. Pay attention to companies that are expanding into commercial and multi-site applications, where operational outcomes and centralized control can support more predictable demand than purely consumer-driven cycles. Also monitor exposure to connectivity cost structures and regional regulatory variance, since these factors can influence margin stability and market access over the forecast period.
For Procurement and Building Operations Leaders
Evaluate smart thermostats as part of a broader energy and comfort management strategy rather than as standalone replacements. Favor solutions with strong HVAC compatibility, clear standards alignment, and occupancy or air quality features that match your operating profile. In multi-site or commercial environments, prioritize centralized visibility, consistent zone control, and support for occupancy-based scheduling to reduce manual adjustments and simplify maintenance planning. Where possible, request evidence of savings and integration behavior across similar building types to reduce deployment risk.
The smart thermostats market is expanding quickly, but the strategic contest is already moving from adoption volume to integration quality, operational impact, and resilience across connectivity and regulatory conditions. Detailed segmentation data, regional breakdowns, and tailored scenario analysis can help translate these trends into specific product, pricing, and investment decisions. For those seeking a deeper view of subsegments, competitive benchmarks, and actionable recommendations suited to a particular market or application, the full PW Consulting research report provides the supporting detail needed to move from market intelligence to execution.
For detailed analysis of this topic, please visit the official page: Smart Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com