

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LED Billboard Market 2026-2032: Why 6.98% CAGR Reshapes Growth Beyond $344.8M

LED Billboard Market: Strategic Trends and Commercial Opportunities in a Maturing Out-of-Home Display Ecosystem
Market Reality and Core Challenges
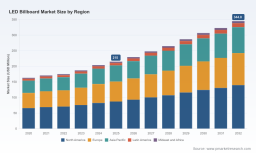
The LED billboard market has moved from a phase of rapid capacity expansion into a period of more deliberate, value-driven growth. Between 2020 and 2025, the sector advanced from roughly 163 million USD to 215 million USD, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon extending to 2032. By the end of that forecast window, revenue is projected to approach 345 million USD, indicating that the industry is not stalling but recalibrating around more durable demand drivers. The growth trajectory is steady rather than explosive, which means competitive advantage is increasingly defined by deployment quality, integration capability, and operational resilience rather than sheer installation volume.
This maturity brings a set of structural challenges that decision-makers need to address directly. First, the market is experiencing a shift from headline growth to margin discipline. Outdoor LED billboards are capital-intensive assets with long planning cycles, permitting requirements, and site-specific engineering constraints. Revenue growth alone no longer guarantees healthy execution economics. Installations can vary widely in complexity and cost depending on size, resolution, and local conditions, so organizations that do not manage project scoping, site readiness, and component selection carefully can see returns erode even as top-line activity expands.
Second, the industry is navigating a tighter regulatory and compliance environment. Signage rules are becoming more detailed, especially in jurisdictions that are scrutinizing installation practices, labeling, and visual impact for electronic displays. In practical terms, this increases the burden on developers and operators to demonstrate compliance early in the project lifecycle. Companies that treat compliance as an afterthought face delays, redesigns, and reputational risk, while those that build regulatory readiness into their product and deployment processes gain a smoother path to commercialized installations.
Third, supply-side volatility remains a core turning point for the market. High-end components, particularly LED chips and driver ICs, represent a significant share of the bill of materials, and premium versions can carry materially higher input costs. At the same time, trade policy uncertainty around key hardware components can introduce short-notice pricing pressure. Combined with periodic supply chain disruptions affecting specialized parts, this environment rewards firms that have diversified sourcing, strong inventory planning, and enough design flexibility to substitute components without compromising performance.
Key Market Drivers
Technology innovation continues to be one of the most important catalysts in the LED billboard market, but the nature of innovation is changing. The competitive focus is moving beyond brightness alone toward integrated performance: better color calibration, more consistent outdoor visibility across viewing conditions, and smarter content optimization. AI-driven content tools and high-brightness modules are becoming relevant differentiators because they improve the effectiveness of the display once it is installed. For advertisers and operators, this means the value of a billboard increasingly depends on how well the hardware and software work together in live outdoor environments, not just on raw pixel specifications.
Policy and regulatory dynamics are also shaping demand in more nuanced ways than a simple expansion or restriction narrative would suggest. In some regions, updated signage compliance requirements are prompting re-examination of installation practices and product labeling for electronic displays. These requirements can slow individual projects, but they also raise the barrier to lower-quality entrants and encourage standardization around more durable, better-documented systems. For the market overall, this creates a subtle shift in favor of established manufacturers and operators that can prove reliability, traceability, and long-term maintainability.
Demand-side behavior is supporting this shift. Advertisers and venue operators are looking for outdoor displays that do more than deliver static visibility. They want flexible digital formats, better integration with scheduling and content management, and displays that can adapt to changing campaigns without requiring full hardware replacement. This is especially relevant in retail and transportation settings, where out-of-home visibility intersects with location-based marketing, event-driven messaging, and changing foot or vehicle traffic patterns. The underlying behavioral change is a preference for displays that can be actively managed as part of a broader media and communications strategy rather than treated as fixed infrastructure.
Cost structure and supply chain strategy form the fourth major driver. Outdoor LED billboard deployments are not commodity purchases; they involve customization across site conditions, mounting requirements, resolution needs, and environmental exposure. That makes procurement and engineering coordination central to commercial outcomes. At the same time, raw material exposure and component availability can influence project timing and pricing. Companies that develop clearer internal standards for modular designs, serviceability, and selective premium sourcing are better positioned to control installation risk and avoid performance shortfalls that can undermine customer confidence.
Competitive Landscape and Leading Strategies
The competitive field in the LED billboard market is concentrated enough that scale, product breadth, and deployment reputation matter, yet still open enough that specialization can create meaningful differentiation. Market leaders are not competing solely on price; they are competing on the reliability of outdoor performance, the manageability of the total installation process, and the ability to support customers after deployment. That combination is especially important because a billboard is both a physical asset and an ongoing advertising medium, so the post-installation experience shapes repeat business and network expansion.
Daktronics stands out as a manufacturer with strong visibility in outdoor LED video walls, dynamic digital billboards, and large-scale message displays for sports, transportation, and advertising. Its recent expansion through deployment partnerships illustrates a practical growth model: extending reach by integrating hardware into broader outdoor advertising networks rather than relying only on direct product sales. This kind of network-centric expansion is strategically important because it ties the manufacturer more closely to live installation demand and long-term operational use.
Watchfire Signs competes with a focus on OOH digital billboards and outdoor LED signs supported by proprietary color calibration and specialized software for high-visibility advertising. In a market where perceived image quality and consistency influence buyer confidence, this software-and-calibration emphasis is a clear differentiation path. It signals an understanding that outdoor advertising performance depends on repeatable visual quality as much as on enclosure durability.
Formetco illustrates a different strategic angle: in-house manufacturing of LED digital billboards and sports systems, combined with product features such as long brightness warranties and fanless cooling. The wider agreement with SignBird to provide a modern marketing resource platform also shows how hardware companies are increasingly extending into customer-facing platforms and services. This is a useful indicator of where the industry is heading: manufacturers that can pair hardware reliability with streamlined customer acquisition, configuration, and deployment support may gain a stronger commercial position.
Samsung Electronics and its associated display offerings bring global scale, AI-driven content optimization, and ultra-high-brightness module capabilities into the market. Prismview, as a specialized provider of large-format LED signs and digital billboards operating under Samsung Electronics, represents how brand ecosystems can combine broad technology capability with focused go-to-market niches. For buyers, this structure can reduce uncertainty about supplier continuity and technical support, while also providing access to advanced display features that may be harder for smaller specialists to replicate on their own.
Planar Systems adds another dimension by emphasizing fine-pitch LED video walls and outdoor displays with U.S.-based calibration for premium corporate and advertising applications. This points to a market segment where installation quality, calibration rigor, and premium positioning matter more than volume alone. In practice, the existence of this kind of offering suggests that the LED billboard market is not uniform; there are clearly differing expectations between mass outdoor advertising use cases and higher-end, specification-driven deployments.
The broader competitive trend is a combination of consolidation pressure and segmentation. On one hand, larger players with manufacturing depth, brand recognition, and software or ecosystem capabilities are well placed to capture share in complex, multi-site, or higher-specification projects. On the other hand, specialized firms can still win by focusing on particular applications, regional procurement cycles, or distinctive product features such as long warranties, fanless designs, or calibration-led quality control. New entrants will find the greatest traction not by competing generally, but by solving a specific deployment pain point: faster permitting support, more predictable installation costs, improved content management integration, or stronger supply reliability for critical components.
Future Trends and Commercial Opportunities
One of the clearest trends for the next three to five years is the continued shift from hardware-only selling to integrated outdoor display solutions. Buyers increasingly expect a combination of reliable brightness, consistent color performance, content optimization tools, and serviceability over time. The commercial opportunity here lies in bundling hardware with software, maintenance, and deployment support in ways that reduce total cost of ownership and improve campaign effectiveness. Companies that can make outdoor billboards easier to operate and easier to measure will be better positioned to win multi-site contracts and long-term partnerships.
PW Consulting
A second trend is the growing importance of regional procurement and regulatory readiness as competitive factors. As signage compliance expectations evolve and project approvals become more detailed, speed to installation will depend on how well suppliers and operators align with local requirements. This favors organizations that standardize documentation, installation practices, and product labeling in a way that can be adapted across jurisdictions. The opportunity is to reduce friction in public procurement, leasing, and site development by making compliance part of the product story rather than a separate administrative burden.
LED Display Market
A third trend is the widening gap between premium and standard offerings. High-end components remain a meaningful cost driver, and certain applications will continue to justify higher specifications for brightness, durability, and visual consistency. At the same time, price-sensitive deployments will still seek dependable mid-tier solutions. The strategic implication is that successful players will need clear product tiering and transparent value propositions, so customers understand what they are buying and why one configuration is appropriate for a high-traffic transportation corridor while another fits a retail environment with different viewing conditions. Blurring these distinctions tends to create disappointed buyers and eroded margins.
These trends create several practical commercial opportunities. Manufacturers can pursue longer warranty structures, fanless or low-maintenance thermal designs, and more modular architectures that simplify upgrades and repairs. Operators and media owners can focus on network expansion in regions where permitting pathways are predictable and where digital billboard networks can be tied to recurring advertising demand. Technology providers can strengthen their position by improving content optimization, calibration consistency, and remote management tools that make large outdoor networks more efficient to run. In each case, the opportunity is not simply to sell more screens, but to make each installation more commercially effective over its lifespan.
There are also risks that should not be overlooked. Trade policy uncertainty can affect component costs and lead times, especially for cabinets and structural materials. Supply disruptions for high-end parts can delay projects or force design compromises. Regulatory changes can increase documentation and installation burdens. In addition, overly aggressive pricing strategies can pressure margins in a market where installation complexity and service expectations are rising. The most resilient strategies will be those that build flexibility into sourcing, keep product specifications aligned with real deployment conditions, and avoid assuming that growth in installed base automatically translates into profitable operations.
Decision-Maker Actions
For manufacturers, the priority is to strengthen the link between product design and real-world installation economics. That means investing in modular designs, service-friendly architectures, and clear product differentiation around brightness consistency, calibration, and long-term reliability. It also means preparing for component cost volatility through sourcing diversity and realistic lead-time planning. Firms that can reduce installation uncertainty and support predictable maintenance will have an advantage when buyers compare alternatives with similar screen specifications but different risk profiles.
For investors, the key question is whether a company’s revenue model is aligned with durable demand rather than one-time project cycles. Attention should be paid to recurring service potential, software and content-related value, regional exposure, and the ability to win public procurement or network expansion deals. Companies with strong post-installation support, clear compliance readiness, and recognizable branding in transportation, retail, sports, or premium corporate environments are more likely to benefit from the market’s steady growth path. Conversely, businesses that depend heavily on price competition without corresponding operational discipline may face tighter returns as installation and compliance costs rise.
For buyers and procurement teams, the most important discipline is to evaluate outdoor LED billboards as long-lived assets with operating implications, not as isolated hardware purchases. Site conditions, mounting complexity, resolution requirements, content management needs, and local compliance expectations should all be factored into the decision. Where possible, standardize specifications across projects to improve procurement predictability, and ask explicit questions about calibration practices, warranty coverage, thermal design, and support response. In a market where customized installations can vary significantly in scope and cost, clarity at the planning stage is one of the most effective ways to protect both budget and performance outcomes.
For organizations seeking a more detailed view of segment dynamics, regional variation, company-level positioning, and scenario-based forecasts, the full research report provides deeper segmentation detail and customized guidance. In a market where execution risk, regulatory readiness, and supply resilience are becoming as important as headline growth, access to granular market intelligence can help decision-makers move from general trend awareness to concrete commercial choices.
Outdoor LED Display Market
For detailed analysis of this topic, please visit the official page: LED Billboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com