

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
How Asia Pacific’s Drive is Redefining Water-Based Polyurethane Dispersions Growth

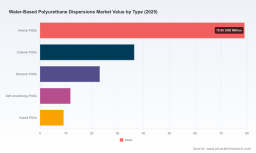
The Water-Based Polyurethane Dispersions Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global market for water-based polyurethane dispersions (PUDs) has entered a phase of steady expansion, with total revenue estimated at approximately 159.5 million USD in 2025 and a projected compound annual growth rate of 5.9 percent through 2032. This trajectory reflects a market that has largely moved past the volatility of the post-pandemic recovery period and is now driven by structural shifts in end-use industries. Historical growth between 2020 and 2025 has been consistent, with annual revenue climbing from roughly 125 million USD to the current level, indicating that the transition away from solvent-based systems is no longer a niche preference but a mainstream industrial requirement. Forward momentum is expected to continue as capacity additions and formulation refinements compound, pushing the market toward an estimated 236.6 million USD by 2032.
Despite this favorable direction, the industry faces several structural bottlenecks that will define competitive outcomes over the next several years. First, raw material cost volatility remains a persistent pressure point. Feedstock prices for polyols and isocyanates have experienced regional fluctuations, and even modest increases can compress margins for formulators who operate on thin spreads. Second, regulatory tightening around volatile organic compound emissions has raised the performance threshold for water-based alternatives. While compliance drives adoption, it also forces manufacturers to invest in advanced stabilization, dispersion, and crosslinking technologies to meet both environmental standards and end-user durability expectations. Third, the market exhibits a high degree of concentration, with a small group of large players accounting for the majority of revenue. This concentration creates pricing influence and technology leverage for incumbents, but it also leaves room for specialized and regional entrants to capture value through tailored formulations, faster customer support, and localized supply chains.
Together, these factors create a market that is growing, but not uniformly. Success will depend on navigating cost structures, meeting stricter performance criteria, and positioning offerings in segments where differentiation is possible.
Key Growth Drivers
The expansion of the PUD market is being propelled by a convergence of technological, regulatory, demand-side, and supply chain dynamics. Each of these forces reinforces the others, creating a self-sustaining cycle of adoption and innovation.
Technological Innovation and Formulation Advances
Formulation science has become a primary differentiator in a market where base chemistry is increasingly treated as a commodity. Recent product introductions underscore the shift toward multifunctional dispersions that combine low environmental impact with enhanced mechanical and chemical performance. For example, new wood coating dispersions launched in 2025 have been engineered to deliver outstanding protection for both residential and commercial surfaces, addressing the long-standing perception that water-based systems lag behind solvent-based counterparts in durability. At the same time, low-VOC and low-CO2 formulations enabled by mass-balance approaches are entering commercial production, allowing manufacturers to reduce the carbon footprint of existing application categories without sacrificing process compatibility. These advances matter because they expand the addressable market: rather than competing only in applications where water-based chemistry is the least-cost option, PUD suppliers can position their products in higher-value uses where performance parity or superiority is required.
Policy and Regulatory Environment
Regulatory frameworks continue to be a decisive force in reshaping demand patterns. Stricter VOC emission standards in the United States and Europe have accelerated the replacement of solvent-borne systems with low-VOC water-based alternatives, particularly in architectural coatings, construction-related applications, and industrial finishes. Compliance is no longer a peripheral concern; it is a commercial catalyst that shortens decision cycles for formulators under pressure to meet environmental targets. This regulatory momentum is also reshaping regional investment patterns, as companies look to establish or expand capacity closer to end markets to reduce exposure to logistics bottlenecks and to align with local compliance expectations. The net effect is a policy environment that favors scale, technical readiness, and the ability to provide documented environmental benefits alongside performance guarantees.
Worldwide Modified Polyurethane Dispersion Market
Demand-Side Shifts in End-Use Industries
End-use industries are driving change from the customer side as well. Coatings remain the largest application category, reflecting broad adoption across construction, furniture, and industrial substrates. Adhesives and sealants represent another major demand center, where water-based dispersions are increasingly specified for their ease of handling, reduced odor, and compatibility with sensitive substrates. Synthetic leather production has also emerged as a significant growth area, benefiting from the broader trend toward more sustainable material inputs in footwear, automotive interiors, and consumer goods. Flexible packaging and other specialty applications add further layers of demand, particularly where water-based systems can deliver adhesion, flexibility, and barrier properties without relying on solvent-intensive processes. Across these segments, the common thread is a preference for chemistries that support sustainability claims without compromising processing efficiency or final product quality.
Supply Chain and Cost Structure Evolution
Supply chain resilience has become a strategic priority, influencing both sourcing decisions and capacity placement. Recent capacity investments in Asia-Pacific reflect a deliberate effort to diversify production geography and reduce dependence on concentrated feedstock sources. This regional expansion is partly a response to trade dynamics and the desire to mitigate exposure to export controls and tariff-related risks on petrochemical feedstocks. At the same time, the growing use of bio-based polyols and renewable feedstocks is altering cost structures and sustainability profiles simultaneously. While bio-based inputs can introduce challenges in consistency and scale, they also offer a pathway to differentiate products on environmental grounds and to insulate part of the value chain from fossil-based price swings. The interplay between regional capacity growth and feedstock innovation is reshaping how cost, performance, and sustainability are balanced in commercial formulations.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive structure of the PUD market is characterized by a mix of global specialty chemical producers, regional scale players, and highly focused custom formulators. This mix creates a layered competitive environment where broad portfolio strength, regional responsiveness, and application-specific expertise all play roles in market positioning.
Strategic Positioning of Key Players
Several companies illustrate the range of strategies currently shaping the market. Large global producers are leveraging integrated feedstock capabilities and broad formulation portfolios to serve multiple end-use segments, with an increasing emphasis on low-VOC and bio-based grades. Their advantage lies in the ability to offer consistent supply, technical support at scale, and the credibility that comes with established brand recognition across coatings, adhesives, and construction applications. Other global suppliers have built strong positions around low-emission and high-performance formulations for fiber sizing, coatings, and industrial uses, using product lines that are closely associated with specific performance attributes. Integrated manufacturers with in-house polyol and isocyanate capabilities are particularly well placed to manage cost and supply continuity, while also tailoring dispersions for coatings and specialty applications. In the wood coatings and industrial finishes space, suppliers have focused on durability and chemical resistance as core selling points, launching products that target demanding residential and commercial environments.
At the same time, cost-competitive producers with integrated MDI operations are expanding capacity to serve coatings and adhesives markets, using scale and regional footprint as key levers. Specialist manufacturers have carved out roles by concentrating on biobased and renewable dispersions, custom design for adhesives and leather finishes, and specialty grades for graphic arts and technical applications. This segmentation allows smaller players to compete on agility, formulation tuning, and direct customer collaboration, even in a market where overall concentration is high.
Recent Developments Reshaping the Field
Recent activity in 2025 highlights how strategy is being translated into concrete capacity and product moves. A major Chinese producer completed a large water-based resin project that included substantial annual volume for waterborne polyurethane dispersions alongside epoxy resin capacity, reinforcing the trend of region-based expansion and feedstock integration. A German heavyweight started up a new production line focused on low-VOC and low-CO2 dispersions for architectural coatings and construction industries, signaling the importance of sustainability-linked product lines in mature markets. A European specialty player inaugurated a new PUD manufacturing facility in Singapore to better serve the Asia Pacific region, illustrating how incumbents are positioning capacity closer to fast-growing demand centers. In addition, a new wood coating dispersion was introduced to strengthen protection performance in residential and commercial applications, and a major Japanese chemical group announced significant capacity expansion for its polyurethane dispersion line. These developments collectively point to a market where investment is targeted at both scale and differentiation, with geography and performance attributes guiding where new capacity is placed.
Evolution of the Competitive Structure
The market is likely to continue evolving along two complementary paths. On one hand, consolidation pressure will persist among suppliers that need scale to sustain R&D investment, reduce feedstock exposure, and compete in regulated application areas. On the other hand, differentiation will deepen as customers demand formulations tailored to specific substrates, processing conditions, and sustainability targets. New and regional entrants can find openings by focusing on application niches, offering faster formulation turnarounds, or combining regional production with specialized bio-based or low-emission chemistries. The most resilient competitors will be those that can operate at both levels: maintaining broad supply reliability while also delivering specialized value where generic commodity dispersions are insufficient.
Future Trends and Opportunities
Looking ahead to the next three to five years, several trends are likely to define the direction of the PUD market and the opportunities within it.
Acceleration of Low-Emission and Bio-Based Formulations
The combination of regulatory pressure, customer sustainability commitments, and technological progress will continue to accelerate adoption of low-VOC and renewable feedstock-based dispersions. This trend creates opportunities for suppliers that can document environmental benefits, maintain performance parity, and offer drop-in compatibility with existing production lines. It also raises the bar for marketing claims: credible sustainability positioning will increasingly depend on transparent feedstock sourcing, lifecycle considerations, and independently verifiable performance data. Companies that can align product development with these expectations will be better placed to capture premium positions in coatings, adhesives, and synthetic leather applications.
Regional Capacity Build-Out and Supply Chain Rebalancing
Continued capacity additions in Asia-Pacific and selective investments elsewhere suggest that supply chains will become more regionally diversified. This rebalancing can reduce lead times, improve service levels, and lower exposure to trade-related disruptions, but it also requires disciplined execution to avoid overcapacity in specific segments. For buyers, the practical implication is greater choice and potentially stronger negotiating leverage, especially where regional suppliers can match performance with local support. For manufacturers, the opening lies in securing long-term offtake relationships and aligning capacity expansion with genuine end-use demand rather than speculative growth.
Performance Parity as the New Baseline
As water-based dispersions increasingly match solvent-based systems in durability, chemical resistance, and adhesion, the competitive conversation will shift from environmental compliance alone to total cost of ownership, processing efficiency, and application reliability. This shift favors suppliers with strong technical service, reliable quality consistency, and formulations that reduce rework or enable faster line speeds. It also creates an opportunity for hybrid and specialty dispersions that address specific substrate challenges, particularly in coatings and adhesives where performance requirements are tightening.
Polyurethane Dispersions (PUD) Market
Potential risks remain. Raw material price volatility can still erode margins if not managed through hedging, vertical integration, or value-based pricing. Regulatory requirements may continue to become more demanding, requiring ongoing reformulation and documentation efforts. In addition, the concentration of the market means that a few large players can influence pricing and availability, which can pressure smaller suppliers unless they have clear differentiation. Finally, capacity expansion must be carefully matched to demand absorption; overspending on volume in segments with limited differentiation could lead to price erosion.
Actionable Recommendations for Decision Makers
For Manufacturers and Formulators
Focus formulation development on the intersection of compliance and performance. Low-VOC and bio-based attributes open doors, but they must be paired with durability, adhesion, and processing reliability that reduce total application cost. Invest in technical service capabilities, because customers increasingly evaluate suppliers on the basis of formulation support and consistency as much as on base pricing. Where possible, strengthen feedstock linkage or long-term supplier agreements to dampen cost volatility and protect margin during periods of regional price movement.
For Investors
Evaluate companies based on how well they balance scale, differentiation, and regional positioning. Capacity expansion is only valuable if it is aligned with end-use demand and supported by product-level differentiation that protects pricing. Pay attention to companies that are building low-emission, mass-balance, or bio-based lines, since these investments are likely to become more valuable as regulatory and customer requirements tighten. Also consider the importance of regional footprint: suppliers with production located closer to fast-growing demand centers may gain service and resilience advantages that translate into better commercial outcomes over time.
For Procurement and Sourcing Leaders
Diversify sourcing options where feasible, especially by evaluating regional suppliers that can offer comparable performance with reduced logistics exposure. Use sustainability and compliance credentials as part of the evaluation framework, but verify performance claims through application testing before making sourcing changes. Build relationships with suppliers that provide formulation customization and technical support, since these capabilities can reduce implementation risk when transitioning from solvent-based or legacy water-based systems to advanced PUD grades.
Moving Toward a More Informed Strategy
The water-based polyurethane dispersions market is at a point where growth, regulation, technology, and supply chain strategy are tightly intertwined. Macro momentum is clear, but the commercial winners will be determined by how well companies navigate feedstock volatility, meet rising performance expectations, and position capacity where demand is expanding fastest. Detailed segmentation data, regional comparisons, and company-level assessments can help decision makers move from broad trends to specific, actionable plans. For organizations that need a deeper view of segment dynamics, competitive positioning, and forward scenarios, the full research report provides a structured foundation for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Water-Based Polyurethane Dispersions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com