

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
4A and Air Separation Drive the Molecular Sieve Adsorbents Market: 4.7% CAGR Analysis 2026-2032

Molecular Sieve Adsorbents Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
The molecular sieve adsorbents market is entering a decisive growth phase. Valued at USD 1,118.0 million in 2020 and projected to reach USD 1,934.0 million by 2032, the sector is expanding at a compound annual growth rate of 4.7% throughout the 2026–2032 forecast period. This trajectory reflects more than steady industrial demand; it signals a structural pivot driven by energy transition priorities, tightening emissions standards, and technological maturation across gas separation, drying, and purification applications. For executives and investors operating in adjacent sectors, understanding where value is accumulating—and where margin pressure is intensifying—is no longer optional. The market’s evolution requires a clear view of demand drivers, competitive positioning, and the operational realities that will define winners over the next five years.
Market Landscape and Core Challenges
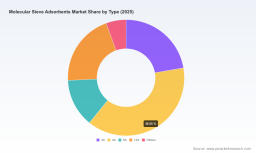
The market has grown from USD 1,237.4 million in 2023 to an estimated USD 1,402.0 million in 2025, a progression marked by consistent demand pull from industrial gases, refining, and specialty separation applications. Asia Pacific currently anchors the largest regional revenue share, followed by North America and Europe, while Latin America and the Middle East & Africa contribute smaller but steadily growing positions as regional industrial capacity expands. Type-wise, 4A-grade sieves command the broadest application footprint, 3A and 13X grades sustain strong positions in dehydration and gas drying, and 5A variants remain essential in higher-selectivity separation workflows. On the application side, air separation and petroleum refining together represent the dominant revenue streams, with petrochemicals and refrigerant processing forming a meaningful secondary layer of demand.
Beneath this growth curve, several structural challenges are reshaping how vendors, buyers, and investors should interpret market signals.
Raw material cost volatility is compressing margin stability. Sodium silicate and sodium aluminate prices have become increasingly sensitive to energy market fluctuations and supply chain disruptions. Since these precursors form the foundation of zeolitic sieve production, cost swings directly affect manufacturing economics and pricing strategies. Producers that lack diversified sourcing, long-term supply agreements, or process efficiencies are facing greater exposure, particularly in cost-sensitive industrial drying segments.
Regulatory tightening is raising the performance threshold. New environmental restrictions in the EU and the US require higher-purity molecular sieves capable of meeting ppm-level contaminant limits in air separation and related processes. At the same time, stricter volatile emissions rules are pushing buyers toward circular-economy procurement policies that favor regenerated sieves. These dynamics create a dual pressure: performance specifications are rising, while procurement teams are also scrutinizing lifecycle cost and sustainability credentials. Compliance with ISO 9001 and REACH standards further adds to certification costs for sieves used in pharmaceutical and food-grade applications, which raises the barrier to entry in high-value end markets.
Operational costs are reshaping competition in labor- and logistics-intensive segments. Rising labor and logistics costs for specialized adsorbent handling, transport, and regeneration have pressured margins in compressed air and industrial drying applications. In markets where sieves are treated as more commoditized consumables, buyers are increasingly evaluating total cost of ownership rather than unit price alone. This shift rewards suppliers that can offer reliable regeneration protocols, predictable service intervals, and optimized logistics over those competing purely on product pricing.
Key Demand Drivers Reshaping the Market
The market’s expansion is not uniform; it is being unevenly pulled by technological, regulatory, and demand-side forces. Three drivers stand out as particularly influential for the 2026–2032 period.
Technology innovation is expanding the addressable use cases
Advances in sieve formulation and manufacturing are extending the role of molecular sieves beyond traditional dehydration and separation. Higher-selectivity grades are increasingly relevant in hydrogen purification, carbon capture workflows, and battery-related drying applications, where moisture and contaminant control directly affect process efficiency and end-product quality. Improved 13X and lithium X variants are enabling more effective removal of specific impurities in natural gas and olefin/paraffin streams, while specialized grades designed for high-purity gas drying are opening opportunities in electronics, medical, and advanced materials processing. These innovations matter because they shift molecular sieves from a maintenance-driven consumable to a performance enabler in higher-margin applications.
Recent product and capacity actions illustrate this direction. One major supplier expanded its zeolite manufacturing facility in Ludwigshafen, Germany, to increase production of specialized molecular sieves for hydrogen purification and carbon capture applications. Around the same period, the same company introduced improved sieve grades tailored for drying lithium-ion batteries and high-purity gases. These moves signal a deliberate pivot toward applications where purity, consistency, and energy efficiency carry stronger commercial weight than bulk volume alone.
Environmental and regulatory pressure is accelerating adoption of cleaner separation technologies
Policy and regulatory environments are acting as both a constraint and a catalyst. Stricter emissions controls are forcing industrial users to improve the efficiency of gas drying, purification, and separation processes. In practical terms, this increases demand for sieves that can operate longer between regenerations, tolerate harsher process conditions, and meet increasingly stringent purity specifications. Regenerated-sieve procurement policies are also gaining traction as organizations seek to reduce waste and align purchasing with circular-economy goals. For suppliers, this means that performance claims, regeneration compatibility, and documentation of compliance are becoming integral parts of the commercial proposition rather than ancillary service features.
Demand-side shifts are broadening the customer base
Beyond traditional refining and air separation, demand is spreading into segments where gas purity and drying performance are becoming critical to product quality. Medical oxygen generation is one of the more visible examples, where reliable oxygen purity depends on consistent sieve performance. Growth in electrolyte and battery manufacturing processes is also increasing the need for moisture-sensitive drying solutions, and higher-specification industrial gas applications continue to expand in specialty chemicals and advanced materials. At the same time, procurement behavior in compressed air and industrial drying is shifting toward lifecycle value. Buyers are more willing to evaluate supplier reliability, regeneration support, and compliance documentation if those factors reduce downtime and total operating cost.
Supply chain and cost structure changes are redefining competitive dynamics
Cost pressures are not limited to raw materials. Energy-intensive production processes, specialized handling requirements, and logistics for regeneration and replacement create a cost structure that is increasingly sensitive to regional operating conditions. This favors producers with integrated manufacturing footprints, stable energy access, and the ability to standardize regeneration services or technical support. For buyers, it underscores the importance of supplier selection criteria that account for lead time consistency, regeneration efficiency, and technical guidance, especially where process interruptions carry high costs.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with the top three players accounting for approximately 29.8% of revenue and the top five representing around 38.6%. This level of concentration suggests that scale, application expertise, and geographic reach still matter, but it also leaves room for differentiated specialists to compete effectively in high-value niches. The competitive field is shaped by a mix of broad-portfolio suppliers and focused technology players, each pursuing distinct strategic plays.
Zeolite Molecular Sieves Market
Arkema has positioned itself as a global leader in Siliporite® molecular sieve adsorbents across 3A, 4A, 5A, and 13X grades. Its portfolio spans dehydration, purification, and separation for energy, chemicals, industrial gases, medical and pharma packaging, and construction applications. The company’s recent capacity expansion in Ludwigshafen and the launch of improved Hespera-grade sieves for lithium-ion battery drying and high-purity gases indicate a strategy centered on high-performance grades tied to hydrogen purification, carbon capture, and advanced battery-related drying. This approach allows Arkema to compete not just on volume but on application-specific performance and technical credibility.
BASF SE remains a major manufacturer of 3A, 4A, 5A, and 13X molecular sieve adsorbents for compressed air drying, petrochemical refining, and general industrial applications. Its strength lies in broad application coverage and deep integration with catalyst and chemical portfolios, which supports cross-selling and a strong presence in refining and industrial drying. BASF’s positioning suggests a strategy of scale, consistency, and breadth, appealing to buyers seeking reliable supply and established product familiarity.
PW Consulting
Honeywell UOP stands out through its UOP/MOLSIV® and HiSiv® molecular sieve adsorbents, which are focused on olefin/paraffin purification, natural gas processing, and polymer streams. This specialization gives Honeywell UOP a strong foothold in higher-value separation applications where selectivity and process integration are critical. Its strategy appears oriented toward performance differentiation and close ties to downstream process requirements, which can translate into stronger customer lock-in in technologically demanding segments.
Zeochem AG offers a wide range of 3A, 4A, 5A, 13X, lithium X, calcium X, and Purmol zeolite molecular sieve adsorbents for industrial oxygen generation, natural gas treatment, solvent drying, and medical oxygen. Zeochem has been particularly active in expanding its medical oxygen generation footprint, including an office expansion in Louisville, KY, to support growth of its ZEOtope molecular sieve product line. The company also completed the acquisition of SiliCycle Inc. to broaden its portfolio of high-value chromatography gels and molecular sieve technologies. These moves reflect a dual strategy: reinforcing leadership in medical and industrial oxygen applications while expanding into higher-margin specialty purification and chromatography-related technologies.
Tosoh Corporation supplies Zeolum® zeolite molecular sieve adsorbents for gas product drying, petrochemical refining, and separation processes. Its positioning is consistent with a steady, application-focused supplier serving refining and gas drying markets with established product lines and regional manufacturing strength. W.R. Grace & Co. continues to provide molecular sieve adsorbents and related adsorbent technologies for gas purification and refining applications, leveraging a long-standing reputation in process technologies. Albemarle Corporation integrates molecular sieve adsorbents within broader catalyst and specialty chemical portfolios, making it relevant in petrochemical and chemical processing contexts where integrated solutions can create additional value. Clariant AG supplies molecular sieve adsorbents for industrial drying, purification, and separation in chemicals and refining sectors, positioning around application reliability and specialty chemical expertise.
The competitive landscape is evolving along several axes. Consolidation is visible in targeted acquisitions, such as Zeochem’s purchase of SiliCycle, which expands technical breadth rather than simply adding volume. At the same time, capacity expansions are being directed toward higher-value applications, especially hydrogen purification, carbon capture, medical oxygen, and battery-related drying. This suggests a market that is not merely growing in size but also shifting in composition, with premium performance grades gaining relative importance. New entrants and specialty innovators can still compete by focusing on narrow applications where purity, regeneration efficiency, or compliance documentation provide a genuine advantage, but broaderscale competition will increasingly depend on manufacturing reliability, supply chain resilience, and application engineering capabilities.
Worldwide Zeolite Adsorbents Market
Forward Outlook: Trends Shaping the Next 3–5 Years
Based on current market dynamics and recent corporate actions, three trends are likely to define the next phase of market development.
Premium-grade molecular sieves will capture a growing share of value, even in a market that continues to expand in volume. Demand for higher-purity, more selective, and more durable sieve grades is rising in hydrogen-related workflows, carbon capture, medical oxygen, battery drying, and high-specification industrial gases. As stricter purity requirements and circular procurement practices become more common, buyers will place greater weight on performance consistency and regeneration efficiency. Suppliers that can demonstrate differentiated grades and reliable technical support are likely to retain stronger pricing power in these segments. The commercial opportunity lies in aligning product development with applications where contamination control and process reliability directly affect end-product quality and operating cost.
Regional demand will keep diversifying, but not uniformly. Industrial capacity growth in Asia Pacific continues to support expanding consumption, while North America and Europe maintain strong demand in refining, industrial gases, and regulatory-driven substitution. Latin America and the Middle East & Africa are expected to grow from smaller bases as regional petrochemical, refining, and industrial gas activities expand. The strategic implication is that supply footprints, logistics planning, and local technical support will become more important differentiators, especially where buyers value responsive service and consistent lead times over pure unit-cost competition.
Sustainability and circularity will move from policy language to procurement practice. Regenerated sieve adoption and waste-reduction expectations are likely to become more embedded in buyer decision-making, particularly in jurisdictions with stronger environmental mandates. This will increase the relevance of regeneration-compatible product design, service frameworks, and compliance documentation. At the same time, certification and compliance costs will remain a factor in pharmaceutical, food-grade, and other high-purity applications, reinforcing the importance of demonstrated quality systems. The opportunity here is not simply to sell sieves, but to offer predictable lifecycle solutions that reduce disposal, downtime, and compliance risk.
These trends carry potential risks. Raw material price volatility and energy market swings could continue to challenge cost structures, especially for producers without diversified sourcing or efficient manufacturing. Regulatory requirements may keep rising, raising the bar for performance and certification and potentially narrowing the field for less-equipped competitors. Demand for premium grades may accelerate faster than manufacturing capacity in certain niches, creating short-term supply tightness, while more commoditized segments could face continued margin pressure from total-cost-of-ownership buying behavior. Investors and operators should therefore watch not only top-line growth, but also the mix shift toward higher-value applications and the extent to which regeneration and service capabilities influence purchasing decisions.
Strategic Implications for Decision-Makers
The market’s direction suggests different priorities depending on a reader’s role in the value chain.
For manufacturers and technology providers, the imperative is to align capacity and R&D with higher-value applications rather than chasing bulk volume alone. Investments in hydrogen purification, carbon capture, medical oxygen, and battery-related drying appear better positioned for durable differentiation than undifferentiated commodity compete. Equally important is building or strengthening regeneration compatibility, technical service, and compliance documentation, since buyers in regulated and high-specification applications increasingly evaluate total cost of ownership and lifecycle reliability. Supply chain resilience—through diversified raw material sourcing, stable energy access, and logistics optimization—should be treated as a strategic asset, not just an operational concern, especially where sodium silicate and sodium aluminate volatility continues to affect margins.
For investors, the key question is where margin resilience and growth are converging. The market’s moderate concentration leaves room for both scaled incumbents and specialized players, but value creation is increasingly tied to application specificity, performance differentiation, and service-enabled revenue models. Capacity expansions directed at premium grades and higher-specification end markets are more likely to support pricing stability than volume-only plays in commoditized drying segments. Investors should also monitor consolidation activity and technology tuck-in acquisitions, as these can reshape portfolios quickly by adding chromatography gels, specialty purification capabilities, or new application footholds. Regulatory tailwinds and circular-economy procurement can expand demand, but they also raise entry barriers in food-grade, pharmaceutical, and high-purity applications, which may favor established, well-documented suppliers.
For procurement and operations leaders, the buying lens should shift from unit price to lifecycle value and risk reduction. In compressed air, industrial drying, and other labor- and logistics-sensitive segments, total cost of ownership is being shaped by regeneration efficiency, downtime risk, handling complexity, and compliance burden. Selecting suppliers with strong technical support, clear regeneration protocols, and reliable lead times can reduce hidden costs that are not always visible in initial pricing comparisons. Where sustainability or regulatory requirements are tightening, prioritizing regenerated-sieve compatibility and documented compliance can lower both operational and audit-related risk. In higher-purity applications, consistency of performance and contaminant control should carry more weight than baseline specification sheets, because ppm-level limits and process sensitivity can make variability far more expensive than the sticker price of the sieve itself.
Conclusion
The molecular sieve adsorbents market is expanding at a steady pace, but the more important story is how its center of gravity is shifting. Demand is moving toward higher-purity, higher-selectivity grades in hydrogen purification, carbon capture, medical oxygen, battery-related drying, and other application areas where performance directly affects product quality and operating efficiency. At the same time, cost volatility, regulatory tightening, and lifecycle-oriented procurement are reshaping how value is created and captured. Companies that combine application-specific innovation with reliable supply, regeneration support, and compliance credibility are better positioned to defend margins and capture growth than those competing primarily on volume.
For decision-makers seeking a more detailed view of segment-level dynamics, regional demand patterns, procurement implications, and company-level strategic scenarios, the full PW Consulting report provides deeper segmentation data and tailored recommendations across manufacturing, investment, and procurement perspectives.
For detailed analysis of this topic, please visit the official page: Molecular Sieve Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com