

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Power Connectors Market: Decoding 5.14% CAGR Growth and Shifts

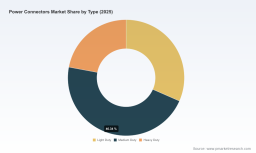
Navigating the Power Connectors Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Size, Trajectory, and Pressing Challenges
The global power connectors market has evolved from a mature, steady-growth segment into a strategically critical component of electrification and digital infrastructure. Recent market tracking shows total revenue climbing from approximately 163 million USD in 2020 to roughly 215 million USD by 2025, with a forward trajectory shaping up toward 345 million USD by 2032. The implied five-year growth rate of 5.14 percent reflects more than incremental industrial expansion; it signals structural demand shifts driven by grid modernization, data center build-outs, and high-power mobility applications. This baseline momentum, however, sits alongside a market that remains comparatively fragmented, with the top three players accounting for less than 25 percent of total revenue and the top five just above that threshold. Such concentration levels indicate room for both consolidation and differentiated niche positioning rather than a single dominant paradigm.
Three structural challenges currently define the operating environment for manufacturers, buyers, and investors.
- Raw material volatility and cost pass-through pressure. Elevated prices for copper and precious metals have begun to compress margins and force repricing across connector portfolios. The impact is not uniformly absorbable, especially for standardized lines where substitution and value engineering are limited.
- Supply chain unpredictability in power-intensive components. Lead times for power supply manufacturing and related interconnect components remain sensitive to demand swings and supplier allocation practices. This instability complicates capacity planning for OEMs and system integrators who rely on predictable delivery windows.
- Regulatory and materials-access constraints. Export controls on certain rare earth materials and broader industrial policy shifts are reshaping sourcing options, qualification pathways, and timeline risk for high-performance connector programs. Companies must now evaluate not only performance and cost, but also material provenance and regulatory exposure.
The practical implication is that scale alone is no longer a sufficient competitive moat. Response speed to cost shocks, qualification agility, and the ability to secure reliable material channels are becoming equally decisive. Market participants that treat these pressures as purely tactical purchasing issues tend to lag; those that embed them into product architecture, supplier strategy, and customer contracting models are better positioned to preserve margin and share.
PW Consulting
Core Drivers Reshaping Demand and Value Creation
Several interlocking forces are steering the market beyond a simple volume-growth narrative.
High-current density and application-specific architecture
A defining technical shift is the move toward connectors engineered for higher current density, hybrid power-signal integration, and harsher operating conditions. Products capable of handling currents in the 350A to 500A range are increasingly visible in industrial electrification, energy storage interfaces, and high-density data center backplanes. This evolution is not just about larger contacts; it is about packaging, thermal behavior, vibration resilience, and modular mating systems that reduce integration risk. Recent product introductions from leading manufacturers illustrate this direction, including high-current connector lines targeting battery energy storage systems, sealed interconnects with combined power and signaling contacts for harsh environments, and vibration-resistant connectors designed for powertrain applications. The recurring theme is performance under constraint: more power in tighter spaces, greater durability, and safer maintenance access.
Policy, energy security, and infrastructure acceleration
Policy and energy-security dynamics are reshaping demand indirectly but powerfully. Industrial and grid infrastructure programs are accelerating the need for reliable electrical interconnects, while domestic production gaps in large power equipment have exposed how dependent downstream deployment schedules are on upstream component availability. When large transformers and related grid equipment face extended lead times, the pressure cascades into interconnected component markets and incentivizes sourcing strategies that prioritize resilience over lowest unit cost. In parallel, materials-access regulations are nudging engineering teams toward alternative material selections and more rigorous supplier qualification. The net effect is a market where compliance and supply assurance are increasingly part of the value proposition rather than background overhead.
Demand-side behavior: electrification, data centers, and ruggedized mobility
On the demand side, several application pockets are expanding the relevance of high-performance power connectors. Industrial automation and instrumentation continue to anchor demand, but growth is increasingly linked to electrified processes, energy storage integration, and networked equipment that blends power delivery with signaling integrity. Data centers and communication infrastructure are also intensifying requirements for dense, reliable interconnects that can support higher power throughput with stable performance. In mobility and aerospace contexts, demand is shaped less by volume and more by qualification difficulty, environmental resilience, and total cost of ownership over long service life. For commercial buyers, the strategic question is shifting from "what connector fits the spec" to "which connector architecture reduces integration risk, maintenance downtime, and future retrofit cost."
Automotive Connectors Market
Cost structure, material economics, and sourcing recalibration
Cost structures are being redefined by materials economics and production logistics. Persistent copper deficits and elevated precious metal prices are translating into documented price increases across connector portfolios, often in the low-to-mid single-digit range and higher for materials-intensive designs. At the same time, power supply manufacturing lead times remain uneven, meaning that inventory strategy, contract terms, and second-source development are becoming strategic levers rather than administrative tasks. This environment rewards companies that can negotiate multi-tier cost pass-through mechanisms, lock in critical material allocations, and design connectors that use materials more efficiently without sacrificing performance. It also rewards buyers who treat connector specification as a long-term sourcing decision, balancing unit price against delivery reliability and lifecycle risk.
Competitive Landscape: Positioning, Differentiation, and the Shape of Change
The competitive field is diverse, spanning broad portfolio players, application-focused specialists, and companies built around specific high-power niches. Rather than competing purely on price, leading firms are building differentiation through current-handling capability, modularity, environmental sealing, qualification depth, and integration support for complex systems.
TE Connectivity illustrates one strategic orientation: concentrating on high-current density solutions and hybrid connector architectures that serve industrial, data center, and energy storage use cases. Its recent product activity around higher-ampacity connectors and stacked hybrid interfaces for battery energy storage systems reflects a move toward ecosystems where power, signal, and packaging are addressed together. Amphenol Corporation leans into high-power backplane, card-edge, and high-power series that align with dense system architectures. Molex emphasizes specialty power connectors and high-performance data center and harsh-environment solutions, reinforcing the trend toward application-tailored portfolios. Hirose Electric Co., Ltd. continues to develop board-to-board, cable, and industrial high-current connectors, with recent launches emphasizing vibration resistance for powertrain environments. HARTING Technology Group has carved out a recognizable position in modular heavy-duty connectors for industrial electrification and automation, where maintainability and ruggedness are central purchase criteria. In higher-reliability corners of the market, Glenair, Inc. and Positronic Industries, Inc. focus on military, aerospace, and ultra-high power interfaces, often with touch-safe, waterproof, or blind-mate features that reduce integration risk. Anderson Power Products rounds out the landscape with sealed, high-power interconnect lines targeting data center and battery applications.
These profiles reveal several competitive patterns:
- Application-led differentiation is strengthening. Leaders are less likely to win on generic catalog breadth alone and more likely to win by aligning connectors with specific operating conditions, mating requirements, and maintenance scenarios.
- Hybridization and modularity are becoming design priorities. Products that combine power and signaling, or that allow scalable mating configurations, reduce engineering rework and improve downstream adoption.
- Qualification and reliability claims are commercial assets. Especially in aerospace, defense, and harsh industrial settings, certified performance and durable contact systems can justify premium positioning and longer cycle longevity.
- Fragmentation still exists, but targeted consolidation is plausible. The relatively dispersed concentration profile suggests room for acquirers to build scale in particular application verticals, or for specialists to grow through portfolio extension and customer depth rather than broad commodity competition.
The market is not simply becoming more concentrated or more fragmented; it is becoming more application-sliced. Companies that can own a demanding segment end to end—from materials sourcing to qualification to field serviceability—can create defensible positions even in a market where no single player dominates overall share.
Forward Outlook: Three Strategic Themes for 2026 to 2032
Looking ahead, the market's trajectory will likely be shaped less by broad commodity growth and more by where high-current, high-reliability interconnection becomes indispensable. Several themes deserve close attention.
1. Power-dense interconnect demand will keep migrating into new infrastructure layers
As electrification extends deeper into industrial processes, energy storage integration, and large-scale computing environments, the need for connectors that can carry higher current with lower integration risk will continue to rise. The commercial opportunity here is not merely unit volume; it is system-level value. Suppliers that can shorten integration time, simplify maintenance, and support scalable power-signal architectures are more likely to become embedded in customer design standards. The uncertainty is demand pacing: procurement cycles in infrastructure and capital equipment can shift with financing conditions, policy timing, and lead-time realities across the broader supply chain.
2. Materials and regulatory exposure will become design inputs, not afterthoughts
With metals prices elevated and certain material access routes constrained, connector design will increasingly need to account for substitution feasibility, material efficiency, and compliance traceability. This creates opportunities for engineering-led differentiation, such as more efficient contact geometry, smarter plating strategies where permitted, and robust second-source qualification. It also introduces risk: programs tied to single-source materials or slow qualification paths may face cost volatility and schedule fragility. The strategic winners will be those that treat material economics as a design parameter and build sourcing resilience into the product roadmap.
3. Resilience and serviceability will compete with unit cost as purchase criteria
In an environment of unpredictable lead times and elevated materials costs, buyers are likely to weigh total cost of ownership more heavily than headline price. Sealed connectors, vibration-resistant designs, and modular maintenance-friendly architectures can reduce lifecycle friction in industrial and field-deployed settings. For manufacturers, this means product roadmaps should increasingly emphasize durability, service access, and mating reliability as commercial features. For investors, it suggests that value creation may be strongest where companies can command premium positioning through reliability and integration support rather than through volume alone. The key risk is over-indexing on niche durability in price-sensitive segments where standardization and cost pressure dominate.
Industrial Connectors Market
Strategic Actions for Decision-Makers
The current market dynamic rewards preparation over reaction. The most useful moves depend on role, but several priorities apply across the board.
For manufacturers and product leaders
- Prioritize high-current density, hybrid, and ruggedized architectures where integration risk and serviceability drive purchasing decisions. These attributes can support pricing power and longer program life.
- Build material resilience directly into product strategy. Evaluate contact design, plating strategy, and supplier qualification with an eye toward cost volatility and materials-access constraints, rather than treating them as purchasing issues alone.
- Use qualification and reliability messaging as a commercial lever, especially in segments where downtime, maintenance access, and environmental exposure are expensive.
For investors and strategic planners
- Focus on application-specific value pools where power density, reliability, and integration support are difficult to replicate. Broad commodity exposure may understate risk given materials volatility and lead-time unpredictability.
- Watch for consolidation opportunities in segments with strong technical barriers and steady demand, while recognizing that fragmented concentration also supports specialist growth through portfolio deepening rather than scale alone.
- Stress-test assumptions around pricing power. Not all connector lines can pass through materials cost increases evenly, and differentiation quality will determine which players preserve margin.
For procurement and sourcing leaders
- Shift from transactional price negotiations to lifecycle cost evaluation. In applications where downtime and maintenance are costly, sealed, vibration-resistant, or modular connectors may deliver lower total cost even at higher unit price.
- Diversify critical sourcing and qualify second sources where feasible, particularly for materials-intensive or long-lead programs. Supplier allocation volatility makes contingency planning a competitive advantage.
- Align connector specification with future deployment risk. Designs that are easier to service, less sensitive to environmental stress, and compatible with scalable power architectures can reduce retrofit exposure later.
These themes are only the starting point for a full strategic plan. Deeper segmentation detail, regional nuance, application-level demand patterns, and company-specific positioning can materially change how opportunities are prioritized and timed. For decision-makers who need to move from broad trend awareness to executable sourcing, product, or investment choices, more granular market intelligence can help translate these directional signals into concrete next steps.
For detailed analysis of this topic, please visit the official page: Power Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com