

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Managed File Transfer Software Market: Why 10.4% CAGR Builds a $3.21B Future

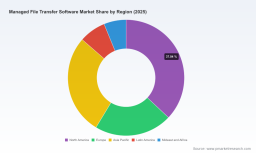
Managed File Transfer Software Market: Navigating Compliance, Automation, and the Cloud Shift
A Strategic Outlook on Market Evolution and Commercial Opportunity (2026–2032)
The managed file transfer software market has entered a phase of structural expansion, driven by converging pressures around data sovereignty, enterprise automation, and cloud-native integration architectures. From 2020 through 2025, the total addressable market scaled from approximately 1.1 billion USD to 1.62 billion USD, reflecting sustained adoption across regulated sectors and the gradual migration of legacy file-sharing workflows into purpose-built transfer management platforms. The forward trajectory through 2032 points to a compound annual growth rate of roughly 10.4 percent, with market size expected to reach 3.21 billion USD by the end of the forecast window. This growth is not evenly distributed: it is being shaped by enterprise procurement patterns, regional regulatory divergence, and a rapid pivot from purely on-premise deployments toward hybrid and cloud-based managed file transfer models. For executives and investors, the market represents more than a compliance utility. It is becoming a strategic layer for secure information exchange, partner connectivity, and audit-ready data governance.
The industry is simultaneously confronting several inflection points that will define competitive positioning over the next half-decade. One of the most visible is the tension between legacy architecture expectations and modern cloud delivery models. Many organizations started with on-premise managed file transfer solutions to retain full control over data paths and encryption keys, but the operational burden of patching, scaling, and maintaining infrastructure has accelerated interest in managed and software-as-a-service variants. At the same time, security and compliance requirements are no longer static checklist items. Cross-border data movement is increasingly scrutinized, and enterprises face mounting expectations to demonstrate not only that files are encrypted, but that transfer workflows are auditable, incident-responsive, and aligned with region-specific regulations. Finally, the market is maturing in terms of vendor differentiation. As baseline secure transfer capabilities become table stakes, the winners are those who can reduce manual effort, embed intelligence into workflow orchestration, and integrate managed file transfer into broader integration and data-exchange ecosystems.
Technology Innovation and the Automation Imperative
One of the most consequential drivers of market momentum is the shift from static file movement to automated, policy-driven transfer orchestration. Modern enterprises operate across fragmented partner networks, cloud environments, and internal systems, making manual file exchanges a liability in both speed and risk. Managed file transfer platforms are increasingly expected to act as control planes that encode routing rules, transformation steps, retry logic, and audit trails directly into the transfer workflow. This shift reduces reliance on custom scripts and ad hoc processes, which historically created blind spots in logging and compliance reporting. Recent product activity illustrates the direction of travel. In mid-2025, Progress Software released an updated version of its MOVEit MFT platform with usability enhancements and reinforced security features, signaling continued investment in the core enterprise transfer experience. Shortly afterward, the company introduced a next-generation SaaS automation platform designed to reduce manual processing and infrastructure overhead by up to half, reflecting a broader industry push to make managed file transfer more operationally efficient and less dependent on dedicated administrative staffing.
Worldwide Managed Office Market
Automation is also becoming a competitive differentiator in highly specialized verticals. In media and content supply chains, for example, transfer speed and reliability are essential, and platform vendors are tailoring SaaS-based managed file transfer offerings for high-volume, time-sensitive workflows. Other vendors have focused on visibility and centralized control, launching operations workbenches that unify monitoring and automation across transfer portfolios. These enhancements matter because they change managed file transfer from a backend utility into a managed service layer that can be governed, measured, and optimized. For enterprises, the implication is clear: platforms that embed automation and centralized operational control can reduce operational friction while strengthening governance. For vendors, differentiation increasingly depends on how well automation is packaged, how easily it integrates with existing systems, and how transparent the platform is to security and compliance teams.
Regulatory Pressure and the Compliance-as-Architecture Shift
Regulatory dynamics have become a central force shaping enterprise procurement of managed file transfer solutions. Data transfer compliance is no longer confined to a single framework or jurisdiction. Enterprises operating across borders must navigate a landscape where privacy and data protection expectations differ by region, yet the underlying principle is consistent: cross-border file movement requires demonstrable controls, traceability, and rapid incident responsiveness. Recent enforcement actions and legislative alignment efforts have raised the stakes. In Europe, regulatory attention around data transfer violations has increased organizational sensitivity to how files move across jurisdictions. In other regions, new or updated personal data protection laws are converging toward principles that resemble established global privacy frameworks, expanding the scope of compliance requirements for transfer operations. In parallel, enforcement in jurisdictions with existing data protection regimes has intensified, particularly around cross-border transfers and the consequences of inadequate controls.
This environment is reshaping deployment expectations. Organizations are increasingly seeking platforms that come with pre-configured compliance templates for major standards and regulations, reducing the time and internal effort needed to align transfer workflows with audit expectations. There is also growing preference for real-time logging, automated incident handling, and structured notification capabilities, since these functions can shorten response cycles and help contain the operational and reputational costs of a breach. From a market perspective, this means managed file transfer is increasingly purchased as part of a compliance and risk posture, not solely as a technical integration tool. Vendors that can make compliance easier to demonstrate—through templates, auditable logs, and integration with broader security ecosystems—gain an advantage in regulated sectors such as financial services, healthcare, and government-adjacent enterprises. The strategic implication for buyers is that compliance readiness should be treated as a first-order selection criterion, alongside performance and integration capability.
Demand-Side Shifts and the Hybrid Delivery Model
On the demand side, enterprise behavior is moving toward managed file transfer models that balance control, cost, and scalability. While on-premise deployments still represent a meaningful share of the market, cloud and managed-delivery approaches are expanding as organizations seek to reduce capital expenditure, simplify maintenance, and accelerate deployment. This shift does not imply a wholesale abandonment of on-premise architectures. In many cases, enterprises prefer hybrid arrangements that allow sensitive data paths to remain under direct control while less constrained workflows benefit from cloud elasticity and managed operations. The availability of managed file transfer as a service has made this hybrid thinking more practical by lowering the barrier to entry for organizations that want auditable file flows without building and maintaining full transfer infrastructure internally.
Cost structure and operational accountability are important parts of this transition. Cloud-based managed services can alter the economics of transfer infrastructure by shifting spending from upfront capital investment toward more predictable operational models. They can also improve auditability by standardizing logging, access controls, and administrative workflows. For large enterprises with complex partner ecosystems, these attributes are especially relevant because they reduce the internal burden of maintaining multiple transfer mechanisms across departments and business units. At the same time, procurement teams are increasingly evaluating total cost of ownership through the lens of operational overhead, incident response capability, and integration effort, rather than focusing solely on license or subscription price. This broader evaluation framework favors platforms that can demonstrate measurable efficiency gains and lower ongoing administrative complexity.
Competitive Positioning Among Established and Specialized Players
The competitive landscape includes large platform vendors, specialized transfer vendors, and integration-centric players, each pursuing different angles of differentiation. A useful way to understand the field is to look at how major vendors frame their managed file transfer capabilities within broader portfolios. Some vendors anchor their offerings in enterprise-grade secure transport platforms with strong automation and auditing functions, positioning them for large-scale, controlled file movement across complex environments. Others emphasize secure automation and built-in compliance support, with SaaS-based platforms that aim to simplify deployment and streamline workflow design. There are also vendors whose managed file transfer capabilities are closely tied to broader B2B integration and information exchange networks, making transfer functionality part of a larger connectivity strategy. Cloud-infrastructure vendors contribute another dimension by embedding managed file transfer features into cloud storage and data services, appealing to organizations already committed to a specific cloud ecosystem.
Several specialist and mid-tier vendors are competing on precision, security posture, and vertical fit rather than breadth alone. Some have built their reputation around platform-independent transfer servers with strong compliance characteristics. Others focus on secure-by-design exchange platforms that incorporate threat intelligence or emphasize validated encryption and private data networking. There are also vendors targeting specific industry workflows, such as media, where high-speed secure transfer and automation are especially important, or service-delivery models that emphasize managed transfer as a service with reduced capital expenditure and stronger auditability. This diversity matters because it gives enterprises multiple entry points depending on their priorities: some want a broad, integrated platform; others want a focused, security-first transfer solution; still others want managed services that reduce operational responsibility.
Recent product activity shows how these strategies are being sharpened in practice. Workbench-style operational tooling has been introduced to improve visibility and centralized control across transfer portfolios. Malware-scanning and security-enforcement enhancements have been layered into transfer platforms to address the reality that file exchanges are common vectors for risk. Cloud-based managed offerings have been launched to make deployment faster and more auditable while lowering upfront infrastructure costs. Together, these moves indicate a market that is moving beyond basic secure transfer toward managed, observable, and increasingly automated file exchange services. The competitive trend is not simply consolidation or fragmentation in the traditional sense. Instead, it is a realignment around value propositions: some vendors are extending into broader integration and data exchange platforms, while others are deepening their security, compliance, and automation capabilities to defend specialized positions. New entrants and adjacent platform players continue to find opportunities where they can combine transfer functionality with strong security, workflow intelligence, or industry-specific workflows.
Market Concentration and the Shape of Future Competition
The market remains moderately concentrated, with the largest providers accounting for a meaningful but not dominant share of total revenue. This concentration pattern suggests that scale advantages exist, particularly for vendors with broad enterprise relationships, established integration footprints, and the ability to embed managed file transfer into larger platform deals. However, it also indicates room for specialized players to compete effectively by serving high-value segments where security assurance, compliance readiness, or operational automation is the primary buying driver. As enterprises continue to evaluate managed file transfer as part of wider data governance and integration strategies, vendors with strong cross-functional portfolios may gain from bundling and cross-sell dynamics. At the same time, focused vendors can thrive by offering depth, clarity, and lower operational complexity for use cases where broad platforms introduce unnecessary overhead. The competitive trajectory is likely to favor organizations that can clearly articulate where they provide unique value rather than those that attempt to be everything to every buyer.
Strategic Outlook: Three Trends Shaping 2026–2032
First, managed file transfer will increasingly be treated as a governed integration layer rather than an isolated file movement tool. As enterprises connect partners, cloud services, and internal applications through more orchestrated workflows, transfer platforms will need to interoperate with identity systems, monitoring tools, data-protection controls, and integration pipelines. The commercial opportunity here lies in platforms that reduce friction across the data-exchange lifecycle and make secure transfer part of a repeatable, auditable process. The risk is that fragmented toolchains will persist if buyers select point solutions without sufficient attention to integration and operational unification.
Second, compliance-driven procurement will intensify as data protection expectations continue to diverge and mature across regions. Enterprises will increasingly favor platforms that lower the effort required to demonstrate compliance through templates, logging, incident handling, and controlled data paths. This trend creates durable demand for managed file transfer in regulated industries and raises the premium on vendors who can make compliance evident and operationally manageable. The uncertainty lies in the pace and form of regulatory change, which can differ significantly across jurisdictions and may shift procurement priorities unexpectedly.
PW Consulting
Third, automation and managed delivery will continue to reshape cost structures and operating models. Enterprises will seek solutions that reduce manual administration, improve reliability, and support hybrid deployment preferences. SaaS and managed service models will expand where they can demonstrate clear operational savings and stronger auditability, but on-premise and hybrid deployments will remain relevant where governance requirements or internal policies favor direct infrastructure control. The commercial opportunity for vendors is to offer flexible deployment paths and measurable efficiency gains. For buyers, the challenge is to evaluate whether a given deployment model truly reduces long-term operational burden or merely shifts it.
What This Means for Different Decision-Makers
For enterprise leaders and procurement teams, the priority should be to evaluate managed file transfer as part of a broader secure data-exchange strategy. Selection criteria should go beyond basic encryption and include automation capability, operational visibility, compliance readiness, integration effort, and the practical implications of deployment models for long-term total cost of ownership. Organizations that standardize on transfer platforms with strong auditability and workflow automation are better positioned to manage partner ecosystems and reduce the hidden costs of manual or fragmented file processes. In regulated environments, platforms that make compliance demonstrable through templates, logging, and incident response can materially shorten the path to deployment and lower ongoing risk.
For investors and strategic planners, the market signals a sustained growth trajectory with differentiation emerging around automation, compliance enablement, and managed delivery. Attention should be paid to vendors that can convert operational efficiency into commercial advantage, whether through SaaS-based platforms, workflow-centric automation, or strong integration into wider data-exchange ecosystems. Concentration levels suggest that scale matters, but specialization also remains viable where security, compliance, and vertical fit are valued highly. Monitoring product launches, enterprise adoption patterns, and regulatory developments will be critical for anticipating where competitive advantage is being created and where pricing or positioning pressure may intensify.
For technology and security leaders evaluating build-versus-buy decisions, the most practical path is usually to prioritize platforms that reduce integration complexity and improve governance without locking the organization into unnecessary infrastructure overhead. Managed file transfer should be assessed not only for its immediate secure transfer capabilities, but also for how it supports longer-term objectives such as partner onboarding, audit readiness, automation of repetitive workflows, and alignment with broader integration and data-protection strategies. In practice, the organizations that benefit most are those that treat file transfer as a managed, governed process and select platforms accordingly.
Connecting Market Intelligence to Action
The managed file transfer software market is expanding in both scale and strategic importance, but the value of any decision depends on how clearly the underlying segmentation, deployment trends, regional dynamics, and vendor positioning are understood. Broad market figures provide orientation, but the actionable detail lies in how subsegments evolve, where deployment models are shifting fastest, which compliance and automation capabilities are becoming decisive in enterprise selections, and how competitive positioning is changing across vendor types. Decision-makers who align their strategies with these dynamics are better positioned to capture growth, reduce operational risk, and avoid costly missteps in platform selection or market entry. For those who need a more detailed view of segment-level data, deployment trends, vendor strategy comparisons, and region-specific implications, the full research report provides the granularity required to move from high-level direction to concrete planning.
Software Asset Management Managed Service Market
For detailed analysis of this topic, please visit the official page: Managed File Transfer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com