

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial Wireless Remote Control Market: Why 7.2% CAGR Signals Structural Shift

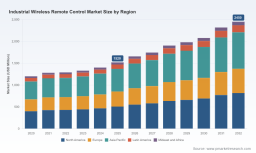
Industrial Wireless Remote Control Market: Navigating Strategic Shifts and Commercial Opportunities (2026–2032)
Wireless remote control technology has quietly become one of the most consequential enabling layers in heavy industry, construction, and material handling. Operators who once managed machinery from cramped operator cabins or exposed control panels now manipulate complex systems from safe distances, often with real-time telemetry feeding back into digital workflows. The industrial wireless remote control market has grown steadily over the past five years, expanding from an estimated $1.2 billion baseline in 2020 to approximately $1.52 billion in 2025. Current projections place the market on a trajectory toward $2.45 billion by 2032, supported by a compound annual growth rate of 7.2 percent. This is not explosive, speculative growth. It is measured, application-driven expansion rooted in safety mandates, labor dynamics, and the gradual digitization of field equipment. For executives and investors, the market's stability can be a distraction: beneath the steady headline numbers lie structural shifts that will determine which suppliers capture premium positioning and which become commoditized component vendors.
The market's current form is the product of several converging forces. Traditional hardwired control architectures are being challenged by environments where operator proximity to heavy loads, rotating machinery, and hazardous payloads carries unacceptable risk. At the same time, the economics of deployment are changing: wireless systems no longer represent a premium add-on reserved for flagship equipment. They are increasingly specified as baseline safety and productivity infrastructure, particularly in sectors where uptime and regulatory compliance carry heavy financial consequences. Understanding where this market goes next requires moving past aggregate size figures and examining the operational frictions, technology transitions, and competitive maneuvers that will shape purchasing decisions over the next half decade.
Market Landscape and the Pressures Reshaping Adoption
The industrial wireless remote control market today is defined less by its size than by the pressure points that are forcing reevaluation across procurement, engineering, and compliance teams. Several themes recur across equipment OEMs, end users, and system integrators.
First, operator safety and ergonomic strain are no longer secondary considerations; they are becoming the primary purchase justification. Industries that rely on mobile hydraulics, cranes, and material handling platforms are confronting persistent labor shortages and an aging workforce. The physical demands of close-quarters machine operation contribute to fatigue, injury risk, and turnover. Wireless remote controls address these concerns by enabling operators to work from protected positions while maintaining control authority over equipment. As a result, wireless solutions are increasingly evaluated through the lens of workforce sustainability rather than pure technical novelty.
Second, the regulatory environment is tightening around functional safety and emergency stop reliability. Industrial wireless remote controls must satisfy functional safety expectations that leave little room for ad hoc designs. Systems that cannot demonstrably guarantee reliable stop functionality under degraded signal conditions, battery anomalies, or interference scenarios face mounting barriers to specification. For suppliers, this translates into higher engineering and certification costs; for buyers, it means that compliance confidence is now a decisive factor in vendor selection. The market is moving away from informal, application-specific retrofits toward documented, certifiable architectures that can survive audit and liability scrutiny.
Third, the integration pathway into broader automation and data ecosystems is altering buyer expectations. Wireless remote control hardware is increasingly expected to do more than transmit commands. Operators and plant managers want systems that feed operational signals into monitoring platforms, support diagnostics, and complement Industry 4.0 initiatives. The challenge is that many existing deployments were designed as standalone safety and control units, not as data nodes. This gap between legacy control point designs and modern digital integration expectations is creating a competitive divide. Suppliers that can demonstrate clean integration paths—without forcing operators to abandon familiar ergonomics—gain a structural advantage in bids for new equipment and retrofitting programs.
Finally, the raw material base and component supply environment remain a persistent, if underappreciated, pressure. Enclosures, specialized polymers, and electronics for control units are subject to the volatility common across industrial electronics and electromechanical assemblies. Because industrial wireless remote controls depend on dependable transmission hardware and ruggedized circuitry, any disruption to radio frequency components or precision electronics ripples into lead times and cost structures. Supply chain constraints are not the dominant narrative, but they influence margin management, inventory planning, and the timing of new product introductions. In practical terms, suppliers and buyers alike are being forced to think in terms of resilience rather than just unit price.
Core Drivers Propelling Market Evolution
Behind these challenges sits a set of drivers that are more durable than short-term cyclical demand. Three to four forces are particularly important for anyone making multi-year capacity, sourcing, or investment decisions.
Technology maturation and differentiation beyond the transmitter. The earliest wave of industrial wireless remote controls competed primarily on range, button layout, and ruggedness. The competitive frontier has shifted. Today's differentiation is increasingly anchored in intelligent automation integration, interoperability with anti-collision and load sensing systems, and configurable safety functions that can be tuned to specific machinery and site conditions. This matters because it changes the value pool. When wireless control units are treated as isolated input devices, pricing pressure intensifies. When they are positioned as part of a safer, more intelligent machine interface, suppliers can justify stronger margins and deeper customer lock-in. Companies with in-house R&D and strong safety certification capabilities are best positioned to pursue this path.
Functional safety and standardization as a market filter. Compliance with functional safety expectations for emergency stop and fail-safe behavior is becoming a de facto market filter. Buyers in construction, lifting, hoisting, and material handling cannot afford unreliable control failures. This regulatory and liability-driven reality raises the barrier to entry for weakly engineered solutions and favors incumbents that can document performance under real-world conditions. The practical consequence is that certification capability and proven field track records increasingly outweigh low-price competition in mainstream industrial applications. Over time, this should consolidate demand toward suppliers capable of sustaining rigorous validation cycles.
Demand-side behavior shaped by safety, labor, and uptime economics. Purchasing decisions are being influenced by a combination of operator safety priorities and workforce constraints. When skilled operators are scarce or expensive to retain, equipment owners look for solutions that reduce physical strain, lower training friction, and support safer operation in complex environments. Wireless remote controls fit into this logic by decoupling the operator from the immediate machine envelope. They are especially relevant where mobile hydraulics, heavy lifting, and forestry or outdoor equipment create environments in which visibility, torque, and proximity risks are difficult to manage through cabin-based controls alone. In these contexts, wireless control is not merely convenient; it becomes part of the operational risk management toolkit.
Supply-side and cost-structure pressures reshaping sourcing strategy. The cost environment is shaped by specialized material needs and the sensitivity of radio frequency-dependent electronics to broader component dynamics. Suppliers are responding in different ways. Some are investing in modular architectures that simplify repair, upgrade, and regional adaptation. Others are making greater use of configurable platforms that can be tailored to specific applications without requiring a fully custom build each time. For buyers, this environment rewards suppliers who can offer both durability and flexibility—units that withstand harsh conditions while remaining adaptable enough to fit multiple machine families and retrofit scenarios. For investors, the more relevant signal is that scale alone no longer guarantees competitive advantage; engineering depth, certification readiness, and integration capability are increasingly the differentiators.
Radio Remote Control Equipment Market
Competitive Landscape and Strategic Positioning
The supplier landscape reflects a market that is mature enough to have produced a stable set of capable specialists, yet fragmented enough that competitive advantage depends heavily on how companies position their technology, certification, and integration narratives. Several patterns stand out.
A clear cluster of durable specialists has emerged around rugged, application-proven wireless control systems. Companies such as HBC-radiomatic, Hetronic, Cattron, OMNEX, Scanreco, Autec Safety, Tele Radio, Danfoss, Green Electric, Akerströms, Control Chief, and Magnetek each carry a distinct operational emphasis. In practice, that emphasis matters more than broad branding. HBC-radiomatic has built its profile around high-quality radio remote controls supported by in-house R&D and safety certifications, with durable applicability across construction and material handling machinery. Hetronic emphasizes rugged transmitters and receivers suited to crane, hoist, trolley, and material handling equipment, where reliability under repeated industrial use is non-negotiable. Cattron positions itself within intelligent automation and control solutions, extending wireless remote controls into industrial and mining applications where system-level thinking matters. OMNEX has cultivated a reputation for Trusted Wireless remote controls designed for high-value machinery in harsh environments, a positioning that aligns with equipment owners who cannot tolerate downtime. Scanreco serves forestry, heavy equipment, mining, and maritime machinery with professional remote controls and customized systems, reflecting an application breadth that depends on close engineering engagement. Autec Safety offers highly configurable and certified industrial radio remote controls for both mobile and fixed machinery, a flexibility that appeals to buyers with mixed fleets or evolving site requirements. Tele Radio focuses on safe wireless remote control systems for industrial, mining, crane, and hydraulic machinery, underlining compliance and operational safety as central themes. Danfoss, through its TM70 series, anchors its offering in heavy machinery and off-highway applications, where environmental ruggedness and integration with broader hydraulic and control architectures are critical. Green Electric focuses on material handling and specialized equipment, a narrower but defensible niche. Akerströms extends into cranes, mobile vehicles, and door-opening applications, illustrating how wireless control can stretch beyond traditional machine operation into site infrastructure control. Control Chief serves cranes, locomotives, and heavy manufacturing applications, an interesting combination that shows how remote control solutions travel across transportation and factory-floor contexts. Magnetek provides rugged industrial radio remote controls for hoisting, lifting, and material handling equipment, maintaining a strong association with lifting and load-control environments.
What distinguishes the stronger competitors is not the breadth of their product lines alone but the coherence of their value proposition around safety, certification, ruggedness, and integration. The market is not rewarding undifferentiated me-too transmitters. It is rewarding suppliers that can reduce the buyer's risk across the entire lifecycle: specification, deployment, compliance documentation, maintenance, and future integration. That is why companies with strong in-house development, demonstrated certification capability, and application-specific expertise continue to hold meaningful positions even as the broader market expands at a steady pace.
Recent field activity reinforces this strategic posture. At FDIC International, Control Chief showcased industrial wireless remote control solutions aimed at steel mill and heavy manufacturing applications, along with an Access 1000 wireless remote control for remote operation of fire station overhead doors. Both demonstrations point to the same strategic logic: extending wireless control beyond traditional machine operation into adjacent infrastructure and process environments where remote actuation improves safety and operational flow. In Brazil, Tele Radio demonstrated next-generation wireless remote control solutions at FEIMEC 2026, a move consistent with the market's continued expansion into Latin American industrial and construction ecosystems. At IFAT 2026, Autec Safety presented a complete range of industrial radio remote controls alongside new safety solutions, signaling an emphasis on broader safety portfolios rather than isolated control hardware. These activities are not merely promotional. They illustrate how competitors are pushing into adjacent application spaces, aligning with trade ecosystems, and reinforcing safety and integration narratives in front of buyers who evaluate solutions in context rather than in isolation.
Looking at the market structure, concentration remains moderate, with the top three suppliers accounting for roughly 35 percent of revenue and the top five around 42 percent. That level of concentration is significant but not dominant, leaving room for specialists, regional champions, and application-focused entrants to compete effectively. The more important structural trend is not wholesale consolidation but selective convergence around capability. Suppliers that can combine rugged hardware, functional safety documentation, and integration readiness are gaining leverage. Those left with only generic hardware offerings risk being pulled into price competition or relegated to secondary sourcing roles. New entry remains possible, but the safest openings are in focused niches—specific machine families, regional industrial clusters, or integration-led service models—rather than in broad head-to-head competition against established specialists.
Forward Signals: What the Next Three to Five Years Will Likely Reward
The market's next chapter will be shaped by the intersection of application expansion, digital integration, and safety compliance. Several trends are likely to define where value accumulates.
PW Consulting
Trend one: wireless control becomes part of the operational data fabric. As smart factory and connected equipment initiatives mature, wireless remote controls will increasingly need to contribute usable signal data to monitoring and analytics environments. The practical opportunity is not just transmitting start and stop commands but enabling richer operational visibility: usage patterns, signal integrity indicators, operator interaction data, and maintenance cues. Suppliers and buyers alike should expect this to become a stronger basis for differentiation. Systems that can feed data cleanly without complicating operator workflows will be favored in bids for new equipment and retrofits. The risk is integration complexity: if data output is forced into proprietary architectures that are difficult to connect, adoption may stall or push buyers toward more open solutions.
Trend two: safety and compliance become the dominant purchase gate, not a checkbox. Functional safety expectations around emergency stop behavior and fail-safe design are already influencing specification decisions. Over the next several years, this will likely sharpen into a more rigorous gatekeeping function. Buyers will compare not only whether a system works but whether its safety design is documented, supportable, and aligned with site risk assessments. This trend creates opportunity for suppliers with strong certification capability and field-proven reliability. It also raises the stakes for new entrants and low-cost players that cannot sustain the documentation and validation burden.
Trend three: application breadth expands into adjacent control domains. The market is gradually moving beyond traditional crane, hoist, and hydraulic machinery into environments where remote actuation improves safety and process control. Fire station overhead doors, steel mill operations, locomotives, door-opening systems, and specialized material handling are all examples of contexts where wireless remote control value extends past the machine itself. This expansion creates growth, but it also introduces complexity. Different applications carry different environmental, duty-cycle, and compliance requirements. Suppliers that can manage that complexity through modular, configurable platforms will be better positioned than those forced to build bespoke solutions for every use case.
These trends share a common implication: value will migrate toward systems that are safe by design, integration-ready, and adaptable across applications without sacrificing ruggedness. The market's 7.2 percent growth trajectory through 2032 will not be evenly distributed. Stronger performance is likely to concentrate where wireless control is tied to measurable safety improvement, workforce sustainability, and operational data value, rather than where it is sold purely as a replacement for wired control.
Remote Control Market
At the same time, uncertainty remains. Radio frequency component constraints can affect supply continuity and cost in certain regions. Regulatory expectations may evolve in ways that require additional engineering investment. Buyers may also hesitate if integration promises outpace real-world interoperability. And as more competitors position themselves around intelligent automation and safety solutions, the risk of narrative hype increases, making it more important for buyers to validate claims against documented performance and field experience.
Strategic Actions for Decision Makers
The market's opportunity is real, but it is distributed unevenly across supplier types, buyer priorities, and application contexts. The following actions are most useful for executives and investors trying to navigate the next planning cycle.
For manufacturers and equipment OEMs , the priority is to treat wireless remote control as a design and safety decision rather than a late-stage accessory. Specify control architectures that align with functional safety expectations from the outset, and choose supplier partners with demonstrated certification capability and in-house development depth. Where possible, favor modular and configurable platforms that can adapt across machine families and retrofit scenarios. Equally important is the integration story: ensure that the control solution can support operational data needs without disrupting operator ergonomics or adding unnecessary complexity. This is where the strongest differentiation will come from in competitive equipment bids.
For investors and strategic acquirers , the relevant question is not whether industrial wireless remote control will grow, but where durable advantage can be built. The most defensible positions are likely to belong to companies that combine rugged hardware, safety certification, application expertise, and integration readiness. Niche specialists that dominate a specific application cluster or demonstrate strong regional presence can also offer attractive exposure, especially where they can expand through adjacent use cases or service-oriented models. The less attractive proposition is a broadly generic hardware play without clear safety, integration, or application differentiation. In this market, capability concentration matters more than headline scale.
For procurement and operations leaders , the buying focus should shift from unit price toward total risk reduction and lifecycle support. Evaluate suppliers on the strength of their safety documentation, field reliability, and ability to support integration with existing monitoring or automation infrastructure. Ask how a system will behave under imperfect conditions, how maintenance and replacement will be handled, and whether the supplier can support multiple applications across a mixed fleet. In a market where compliance and operator safety carry real financial consequences, the cheapest upfront option is often the least valuable over time.
Timely, detailed intelligence is especially valuable in a market like this one, where aggregate growth can obscure the differences that determine competitive outcomes. Segment-level dynamics, regional application preferences, supplier capability gaps, and compliance requirements all influence how the market will split between premium, integration-oriented solutions and more commoditized hardware. Access to deeper segmentation data, supplier profiles, and application-by-application insight makes it easier to align sourcing, capacity, and investment decisions with where value is actually being created.
For decision makers who need a fuller picture—down to segment trajectories, regional demand patterns, and company-level positioning—broader research coverage is the logical next step. Detailed segmentation data, competitive benchmarking, and customized guidance can help translate the market's structural trends into concrete commercial moves. The signal in this market is not simply that it is expanding. It is that expansion is being channeled through safety, integration, and application specificity, and those are the dimensions where strategic advantage will be won or lost.
For detailed analysis of this topic, please visit the official page: Industrial Wireless Remote Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com