

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
CPAP Devices Market: Why 8.15% CAGR and Auto-Adjustment Shifts Redefine 2032

CPAP Devices Market: Strategic Shifts and Commercial Opportunities Through 2032
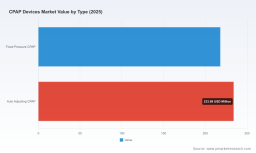
The continuous positive airway pressure (CPAP) devices market has moved into a phase of steady structural expansion rather than episodic growth. Valued at approximately 452 million USD in 2025, the market has advanced from roughly 313 million USD in 2020, reflecting sustained demand for sleep-disordered breathing treatment and a maturing ecosystem of home-based respiratory therapy. The trajectory is expected to continue toward nearly 784 million USD by 2032, underpinned by a compound annual growth rate of approximately 8.15 percent across the 2026-2032 forecast window. This expansion is not merely a function of population aging or diagnosis rates; it is increasingly shaped by product redesign, reimbursement mechanics, regulatory recalibration, and competitive reconfiguration.
For executives and investors, the strategic question is no longer whether the market is expanding, but where value is being created and where margin pressure is building. The following analysis maps the current operating environment, examines the forces driving change, evaluates how leading players are positioning themselves, and identifies the commercial opportunities most likely to differentiate performers over the next three to five years.
Market Context and Core Challenges
The market's current size and forward trajectory reflect a transition from legacy mechanical devices toward connected, patient-adaptive systems. The 2020-2025 period delivered meaningful revenue growth, with year-over-year progression accelerating in the most recent years as home care adoption broadened and replacement cycles for older devices gained momentum. Looking ahead, the 2026-2032 path suggests continued top-line expansion, though the composition of that growth will matter more than the headline figure. Fixed-pressure and auto-adjusting platforms continue to coexist, but the growth center of gravity is shifting toward intelligent pressure delivery, integrated humidification, and software-linked therapy management.
The market also displays a moderately concentrated competitive structure, where a core group of established manufacturers holds a significant share of revenue, while regional and niche players compete through cost positioning, distribution access, and specific clinical applications. Concentration of this nature tends to reward scale, service networks, and regulatory execution, while creating openings for entrants that can address underserved patient cohorts or cost-sensitive procurement channels. That dynamic sets the stage for several interrelated challenges.
Sleep Apnea Masks Market
Reimbursement pressure and patient access variability. Coverage frameworks for positive airway pressure devices continue to vary across payers and regions, with continued emphasis on documented medical necessity, trial periods, and compliance criteria. These requirements influence adoption speed, especially in price-sensitive segments, and create administrative friction that can slow replacement purchases and new patient onboarding. The durability of revenue growth increasingly depends on how efficiently manufacturers and distributors can align product design and service models with payer expectations.
Regulatory recalibration and quality expectations. Classifications and special controls for positive airway pressure delivery systems have established clearer regulatory expectations for safety, performance, and post-market management. At the same time, sterilization and infection-prevention considerations have gained prominence as healthcare facilities and home users become more attentive to reprocessing standards. This environment increases the cost of compliance and rewards companies with disciplined quality systems, but it also creates barriers for manufacturers that lack robust development and post-market infrastructure.
Cost structures and competitive intensity. Retail price points for leading auto-adjusting devices can span a meaningful range once accessories and bundled services are included, which signals both premiumization and ongoing price scrutiny. Materials, component sourcing, and logistics costs remain relevant to margin planning, particularly for manufacturers expanding across multiple geographies. In parallel, a concentrated competitive base means that differentiation is increasingly tied to user experience, connectivity, clinical workflow integration, and service reliability rather than basic device availability alone.
Key Drivers of Market Change
The market's next phase of growth will be shaped by several reinforcing forces rather than a single demand hotspot. The most consequential drivers span product architecture, regulatory and reimbursement conditions, patient and clinical behavior, and supply-side economics.
Technology innovation and therapy personalization. Recent regulatory milestones illustrate how quickly product differentiation is being defined by intelligent comfort features and application-specific designs. FDA clearance for Smart Comfort AI-enabled personalized therapy comfort settings for CPAP devices highlights a shift toward algorithms and sensors that adapt therapy experience in real time rather than relying solely on fixed pressure logic. Equally significant are expanded clearances and planned commercial launches targeting broader patient populations and alternative interface designs. Regulatory movement for nasal pillow systems and new positive airway pressure technologies indicates that manufacturers are pursuing not only incremental device improvements but also differentiated patient interfaces that can improve adherence and expand the addressable population.
This technology trajectory has practical commercial implications. Devices that simplify setup, reduce perceived discomfort, and provide clearer feedback loops are more likely to support compliance, which in turn strengthens the value proposition for both clinicians and payers. Software-linked data management is also becoming a competitive battleground, with development activity extending beyond hardware into platforms that support therapy monitoring and clinical review.
Policy and reimbursement dynamics. Reimbursement frameworks continue to define the practical boundaries of market growth. Coverage for PAP devices under major public programs remains structured around documented diagnosis, trial periods, and compliance-based continuation criteria. These parameters reinforce the importance of medical necessity documentation and adherence support, and they influence how quickly new patients can be initiated on therapy and how steadily existing users replace or upgrade equipment.
From a strategic standpoint, reimbursement conditions reward manufacturers and service providers that can demonstrate real-world efficacy, reduce abandonment, and streamline administrative workflows. Where coverage criteria remain demanding, the commercial winners are often those who invest in patient onboarding, follow-up support, and clinician-facing tools that make therapy management more efficient.
Demand-side shifts in patient behavior and clinical workflows. The growing preference for home-based care continues to support the dominance of home care applications in total market usage, while hospital and clinic settings remain important for diagnosis, titration, and complex case management. This split pushes manufacturers to design devices that function effectively across care settings without creating operational friction. Patients increasingly expect quieter operation, easier cleaning and maintenance, comfortable interfaces, and digital engagement that reduces the perceived burden of long-term therapy. Clinicians, meanwhile, seek clearer data, faster setup, and better integration with sleep medicine workflows.
This dual expectation is reshaping product requirements. Devices are no longer evaluated only on pressure delivery accuracy; they are increasingly judged on total experience, including noise levels, humidification performance, interface comfort, and the quality of companion software or app-based support. As a result, the market is moving toward solutions that reduce drop-off and improve sustained usage rather than simply expanding the installed base through replacement alone.
PW Consulting
Supply chain and cost structure evolution. The competitive base includes manufacturers operating from a range of geographic and sourcing models, which creates variation in cost efficiency, time-to-market, and distribution reach. As premium features and digital add-ons become more common, the economics of device manufacturing are increasingly influenced by component quality, sensor integration, cleaning and sterilization compatibility, and after-sales service requirements. At the same time, price transparency and procurement pressure in certain channels mean that cost discipline remains essential even as companies invest in higher-value features.
Vaporized hydrogen peroxide sterilization recognition for medical devices, including CPAP-related equipment, is one example of how infection-prevention standards can affect design decisions and operating procedures. Clearer sterilization pathways can simplify reprocessing and support broader institutional acceptance, but they also require manufacturers and service providers to align product materials and instructions for use with evolving standards.
Competitive Landscape and Leading Strategies
The market's competitive structure is defined by a mix of large multinational manufacturers, respiratory-focused specialists, and regional players with growing regulatory footprints. The strategic differences among them are becoming more important than the simple fact of market participation.
ResMed continues to emphasize connected auto-adjusting platforms with integrated humidification and digital companion tools, and its recent regulatory progress around AI-enabled personalized comfort settings illustrates a push toward therapy experience refinement. This approach positions the company around adherence, user comfort, and software-enabled differentiation rather than commodity device supply. Philips Respironics remains a prominent competitor with an emphasis on comfort-oriented engineering, including noise reduction and patient-centric design features in its CPAP and BiPAP lines. In a market where adherence and daily tolerability matter, this positioning supports a strong clinical reputation if execution and supply reliability remain consistent.
Fisher & Paykel Healthcare focuses on usability and integrated humidification with interfaces designed for straightforward operation, reinforcing a value proposition that appeals to both patients and care teams seeking simplicity. Drive DeVilbiss Healthcare extends its footprint through home CPAP units and PAP systems, leveraging distribution breadth and a practical orientation toward home therapy. BMC Medical, with its emphasis on APAP and BiPAP devices and respiration data management software, reflects the growing importance of data-enabled therapy support and the increasing relevance of manufacturers expanding their regulatory and software capabilities across markets.
Recent regulatory and commercial activity reinforces the trend toward more specialized and software-linked offerings. Beyond the large incumbent moves, newer or expanding players are seeking clearance for novel interface systems, alternative positive airway pressure technologies, and data management software that supports broader patient populations and institutional use cases. This pattern suggests that competition is not only about scale but also about regulatory agility and the ability to serve specific clinical segments with purpose-built solutions.
The market structure appears likely to evolve along a few clear lines. First, consolidation pressure will remain where scale advantages in service, distribution, and compliance capability support incumbents. Second, differentiation will increasingly emerge from software, interface design, and adherence-oriented features rather than from basic device functionality. Third, new entrants and expanding regional players can find room by targeting underserved patient groups, cost-competitive procurement channels, or specific interface and therapy technology niches. The net effect is a landscape in which broad participation will continue, but the most defensible positions will depend on execution quality, regulatory track record, and the ability to reduce the burden of therapy for patients and clinicians alike.
Future Trends and Commercial Opportunities
Over the next three to five years, the market is likely to be defined by three trends that carry direct commercial implications.
Intelligent, adherence-oriented therapy becomes the default expectation. AI-enabled comfort settings, adaptive pressure logic, and improved interface ergonomics should increasingly separate leading products from baseline alternatives. The commercial opportunity lies in building ecosystems that connect device performance with patient engagement and clinician visibility. Manufacturers and service providers that can show measurable improvements in comfort, usage consistency, and setup simplicity will be better positioned to defend pricing and secure repeat purchasing cycles.
Reimbursement-aligned service models gain strategic importance. As coverage expectations continue to emphasize medical necessity, trial periods, and compliance, the economic value of therapy will increasingly depend on how well providers manage the patient journey. This creates opportunity for integrated models that combine device supply with onboarding, follow-up, data review, and replacement management. The risk is that companies treating devices as isolated transactions may face slower adoption and more volatile demand, especially where payers require documented adherence before continued coverage.
Institutional and broader population access opens incremental growth paths. Expanded clearances and submission activity around data management and broader patient populations indicate a gradual widening of use cases beyond standard home therapy. This creates opportunities for manufacturers to move into institutional workflows, expand interface options, and address patient groups that may have previously faced access barriers. However, the pace of expansion will depend on regulatory processing, payer alignment, and the ability to demonstrate fit for different care environments. A related uncertainty is that reimbursement and sterilization expectations can shift, affecting cost bases and the feasibility of certain use cases.
These trends point to a market where growth is increasingly tied to execution quality and patient outcomes rather than to raw device volume alone. The most attractive opportunities are likely to appear where product design, regulatory positioning, and service integration reinforce one another.
Strategic Actions for Decision-Makers
Different participants will need to prioritize different moves, but several actions are broadly relevant across the market.
CPAP Masks Market
- For manufacturers and device developers, invest in the therapy experience as a core differentiator rather than a feature add-on. Comfort, noise reduction, humidification effectiveness, interface variety, and software-supported adherence should be treated as commercial drivers in their own right. Where possible, align product roadmaps with regulatory clearance pathways and reimbursement realities so that innovation translates into market access rather than lingering in development.
- For investors and corporate strategists, focus on durable value creation beyond headline growth. Examine how well-positioned companies are in service networks, compliance systems, software capabilities, and patient retention. In a concentrated market, the strongest performers are likely to be those that can sustain pricing power through adherence benefits and real-world outcomes while managing material and supply costs efficiently.
- For procurement leaders and healthcare buyers, prioritize total cost of therapy and operational fit over unit price alone. Devices that improve setup speed, reduce cleaning burden, support clinician workflows, and help sustain patient compliance can create broader economic value than lower sticker prices with weaker usability or service coverage. Evaluation criteria should account for replacement cycles, patient dropout risk, and integration with existing clinical and administrative processes.
The market's next phase will reward participants who can read the interaction between technology, reimbursement, regulation, and patient behavior with precision. Because the landscape is evolving quickly across product types, regulatory milestones, and competitive positioning, detailed segmentation data and updated scenario analysis will be important for companies making investment, launch, or procurement decisions. More granular views on regional dynamics, type-level performance, application-specific demand, and company-level benchmarking can help decision-makers translate these strategic themes into concrete plans.
For detailed analysis of this topic, please visit the official page: CPAP Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com