

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
High Speed Motor Market 2026: Beyond the 10.17% CAGR Growth Story

The High Speed Motor Market: Strategic Trends and Commercial Opportunities Through 2032
The high speed motor market has entered a phase of sustained expansion that demands more than passive observation. From 2020 through 2032, the sector is projected to grow from $7.55 billion to $24.87 billion, reflecting a compound annual growth rate of 10.17 percent. This trajectory is not merely a function of incremental demand; it signals a structural recalibration of how industries approach motion, efficiency, and precision. By 2032, the market will have more than tripled in size, with the fastest gains concentrated in the latter half of the forecast window as efficiency mandates, electrification, and advanced manufacturing converge.
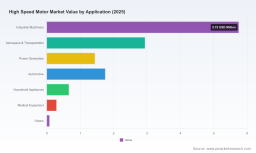
Beyond headline numbers, the market's composition reveals where value is being created and where friction persists. Asia Pacific accounts for the largest regional revenue share, followed by North America and Europe, while Latin America and the Middle East and Africa remain smaller but strategically relevant for specific industrial corridors. On the type front, AC motors dominate the revenue base, whereas DC motors occupy a smaller but technically specialized segment. Applications span industrial machinery, aerospace and transportation, power generation, automotive, household appliances, medical equipment, and other niche uses, with industrial machinery representing the largest application pool. The sector remains moderately fragmented, with the top three players holding roughly 25.5 percent of revenue and the top five capturing approximately 32.4 percent, leaving meaningful space for differentiation and targeted consolidation.
Core Challenges and Inflection Points
Despite robust growth, the market faces several interconnected challenges that will shape competitive outcomes over the next five years.
PW Consulting
Efficiency mandates and material cost volatility. Regulatory timelines are compressing the window for compliance. Electrical steel prices have exhibited pronounced swings driven by broader steel market dynamics and iron ore cost fluctuations, while thin-gauge non-oriented silicon steel remains the primary core material for high speed motors. This combination forces manufacturers to balance performance targets against input cost uncertainty, particularly for high-grade non-oriented electrical steel and amorphous alloys that show ongoing price instability.
Design trade-offs at extreme speeds. Pushing rotational speeds higher amplifies mechanical stress, thermal management demands, and bearing reliability constraints. Achieving record efficiency at these operating points requires tight integration of motor design, drive electronics, and materials engineering. Companies that cannot synchronize these elements risk performance gaps, reliability issues, or cost overruns that erode margin.
Adoption lag in heterogeneous end markets. Not all application verticals move at the same pace. While industrial machinery and aerospace and transportation continue to pull demand, segments such as household appliances and medical equipment operate with different procurement cycles, certification requirements, and total cost of ownership calculations. This unevenness creates pockets of opportunity alongside slower adoption curves that can obscure overall market momentum.
Key Drivers Reshaping the Market
Several forces are interacting to accelerate adoption and redefine competitive priorities.
Technology innovation and efficiency breakthroughs. The push for higher efficiency is no longer optional; it is becoming a baseline expectation. ABB's achievement of a 99.13 percent energy efficiency record in a large synchronous electric motor for a steel plant in India illustrates how design-led optimization can translate into tangible energy savings at scale. Such milestones raise the performance bar across the industry and encourage customers to reconsider legacy specifications in favor of higher-efficiency alternatives that reduce operating expenditure over the asset lifecycle.
Policy and regulatory environment. Regulation is a primary catalyst. The EU Ecodesign Directive mandates IE3 efficiency as the minimum for motors above 7.5 kW starting in 2025, with IE4 phasing in from 2028. In parallel, the US Department of Energy's NEMA Premium and UltraPremium efficiency classes influence purchasing decisions for high speed motors. These standards do not merely set compliance floors; they reshape demand by making efficiency a procurement criterion and by accelerating replacement cycles for older, less efficient units.
Demand-side transformation. End users are increasingly optimizing for throughput, precision, and energy intensity rather than purchase price alone. Manufacturers of industrial machinery and automation systems are seeking motor solutions that support faster cycle times and tighter process control. In logistics and material handling, performance requirements are rising as operators address warehouse throughput challenges, a theme highlighted by Regal Rexnord's showcase of powertrain and motor solutions at ProMat 2025. Meanwhile, high rotational speed capabilities are attracting attention in applications where compact, power-dense motion is critical, exemplified by Tianjin Santroll's showcase of a 36,000 rpm high-speed motor test stand with peak power of 682 kW and peak torque of 605 N·m.
Supply chain and cost structure dynamics. The cost of core materials remains a pivotal variable. Volatility in electrical steel pricing and broader steel market fluctuations can shift the economics of motor production, influencing both pricing strategy and margin management. Companies are responding by strengthening supplier relationships, exploring alternative material specifications where performance allows, and designing for manufacturability to mitigate exposure to input cost swings.
Competitive Landscape and Leading Strategies
The market's moderate concentration leaves room for both scale leaders and specialized players to compete on different axes. Several themes define the current competitive environment.
Efficiency and application-specific engineering. ABB and Siemens continue to emphasize high-efficiency synchronous and induction designs for industrial applications, with ABB focusing on steel plants and energy efficiency and Siemens offering high-speed motor series for industrial drives and high-speed applications. These positions reflect a strategy of aligning product performance with the efficiency and reliability requirements of demanding sectors.
High-speed and heavy-duty specialization. Nidec, Meidensha, TMEIC, Toshiba International, and Mitsubishi Electric contribute distinct strengths in high-speed motor drive systems, ultra-high-speed synchronous motors and spindles, and CNC-oriented spindle and high-speed motor solutions. Regal Rexnord complements this field with high-speed synchronous motors and spindles for industrial and automation applications. The common thread is a focus on application-specific performance, where speed, torque density, and integration with drives and controls become differentiators.
High Speed Oven Market
Geographic and capability diversification. The presence of headquarters and operating bases across Switzerland, Germany, Japan, and the United States underscores a globalized competitive field. Firms are leveraging regional manufacturing, service networks, and application engineering teams to serve customers with localized support while maintaining international scale in design and sourcing.
Market evolution toward selective consolidation and new entry. With the top five holding roughly a third of revenue, the landscape is not dominated by a few incumbents, which creates space for targeted mergers, partnerships, and new entrants that bring specialized materials, electronics, or application expertise. At the same time, efficiency standards and material cost pressures raise the bar for entry, favoring companies that can combine design capability, supply chain resilience, and compliance fluency. Recent activity, from ABB's efficiency milestone to Santroll's high-speed test stand and Regal Rexnord's logistics-focused showcase, illustrates how both incumbents and specialized players are using technical demonstrations and application showcases to signal capability and capture attention in specific verticals.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape where growth concentrates and where value is captured.
Efficiency will become the primary purchasing lens. As IE4 phases in from 2028 and NEMA Premium and UltraPremium expectations influence procurement in the US, total cost of ownership calculations will increasingly favor higher-efficiency motors. This trend creates commercial opportunities for manufacturers that can quantify energy savings, offer integration support, and deliver reliability at higher efficiency levels. It also raises the stakes for suppliers of legacy-standard equipment, where replacement demand may accelerate but price competition could intensify.
Application-specific platforms will outpace generic offerings. Industrial machinery, aerospace and transportation, power generation, and automation-driven logistics are pulling demand toward specialized platforms that balance speed, torque, thermal management, and control integration. Companies that develop modular architectures—able to be tuned for different applications without full custom redesign—can capture share across multiple verticals while managing engineering cost. The commercial opportunity lies in pairing motor hardware with drives, bearings, and service agreements that lock in lifecycle value.
Materials strategy will separate winners from the rest. Given the volatility in electrical steel and the continued reliance on thin-gauge non-oriented silicon steel, firms that secure stable supply, qualify alternative grades where feasible, and design for material efficiency will enjoy margin resilience. This is not purely a procurement issue; it is a design and product management challenge. Opportunities will emerge for suppliers that can demonstrate consistent performance under material cost fluctuations and for customers that align specifications with realistic material availability.
Risk and uncertainty deserve active management. The trajectory is strong, but it is not linear. Regulatory timelines could shift, material cost swings could compress margins unexpectedly, and uneven adoption across application verticals could create demand volatility. In addition, the performance ceiling at extreme speeds introduces reliability and thermal risks that require disciplined engineering and validation. Market participants should plan for scenario variability rather than assume a single growth path.
Actionable Guidance for Decision Makers
Different roles within the market should prioritize distinct moves to capitalize on current dynamics.
For manufacturers and technology providers. Focus on efficiency as a core product attribute and build a credible total-cost-of-ownership narrative around energy savings, uptime, and service life. Invest in application-specific platforms that can scale across industrial machinery, automation, and power-dense use cases without sacrificing performance. Strengthen materials sourcing and design-for-manufacturability capabilities to buffer against electrical steel volatility, and align roadmaps with IE3/IE4 and NEMA Premium/UltraPremium timelines so that product portfolios remain compliant and competitive.
For investors and strategic buyers. Seek companies that combine efficiency leadership with application expertise, especially where motor hardware is paired with drives, controls, and service offerings that deepen customer lock-in. Watch for consolidation opportunities in moderately concentrated segments, but assess supply chain resilience and regulatory readiness alongside financial metrics. Be attentive to regional strengths and to specialists pushing speed and torque boundaries, as these can signal adjacent expansion potential or acquisition targets with differentiated technology.
For procurement and engineering leaders. Treat efficiency standards as a planning parameter, not a compliance checkbox. Evaluate replacements and new procurements against lifecycle energy costs, availability of higher-efficiency variants, and supplier support for integration and validation. Where extreme speeds or specialized torque profiles are required, partner early with suppliers that can demonstrate test data and application engineering support, reducing the risk of performance gaps during commissioning.
High Speed Packaging Machine Market
The strategic picture is clear: the high speed motor market is expanding at a double-digit pace, efficiency mandates are reshaping demand, and application-specific performance is becoming the basis for differentiation. Progress at this pace rewards organizations that align product strategy, materials planning, and regulatory fluency with the evolving expectations of end users. For decision makers who need granular segmentation, regional nuances, and tailored scenario planning, the full research report provides the detailed breakdown and customized guidance required to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: High Speed Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com