

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
How Wireless Routers Lead a 6.98% CAGR as Routers Market Hits $344.8M by 2032

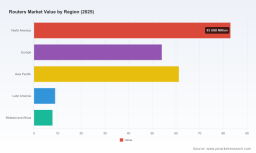
The Router Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2025–2032)
The global router market has entered a period of structural transformation. Over the historical period from 2020 to 2025, revenue climbed from approximately $163.15 million to $215.0 million, reflecting steady expansion across both consumer and enterprise environments. Looking forward through 2032, the trajectory accelerates, with revenue projected to reach $344.8 million, translating to a compound annual growth rate of 6.98 percent. These figures do more than quantify growth; they frame a market where connectivity, security, and regulatory alignment are increasingly inseparable. For executives and investors, the directional signals matter more than any single data point, yet the scale of movement remains substantial enough to warrant disciplined strategic planning.
Several overlapping forces are compressing the market's evolution timeline. First, the convergence of faster wireless standards and enterprise-grade routing architectures is blurring traditional segmentation lines. Second, geopolitical friction is reshaping procurement norms, particularly in North America, where national security concerns have been elevated to explicit policy constraints. Third, supply chain recalibrations and semiconductor cost fluctuations are forcing manufacturers to reconsider inventory strategies and regional sourcing assumptions. Together, these forces create a landscape where agility, compliance readiness, and differentiated feature sets determine competitive outcomes.
Understanding what is happening at the macro level is useful, but the commercial value lies in interpreting which pressures are transient and which will become permanent market conditions. The following sections break down the core drivers, trace how leading companies are positioning themselves, outline the trends likely to shape the next three to five years, and translate those signals into actionable guidance for manufacturers, investors, and procurement teams.
For decision-makers comparing router portfolios today, the immediate question is no longer simply about throughput or coverage. It is whether a routing solution can align with evolving regulatory expectations, integrate cleanly into software-defined network architectures, and scale without introducing operational fragility. That shift in evaluation criteria is already reshaping purchasing cycles and competitive responses.
Key Challenges and Structural Pressures
The most consequential pressure currently reshaping the router landscape is the intersection of regulatory caution and market access risk. Recent actions by the Federal Communications Commission (FCC) have placed new constraints on consumer-grade routers manufactured outside designated approval pathways. On March 23, 2026, the FCC added routers produced in foreign countries to its Covered List, making new consumer-grade models ineligible for equipment authorization unless they receive Conditional Approval from the Department of War or the Department of Homeland Security. The agency reinforced this stance in early guidance, clarifying that only existing inventory remains fully authorized, while new foreign-produced models face meaningful barriers. Netgear and Eero were subsequently noted as exceptions in certain exemption categories, illustrating that policy implementation is not entirely uniform. This regulatory environment introduces compliance uncertainty and raises the cost of market entry for foreign OEMs and their downstream partners.
A second challenge is the widening gap between consumer expectations and enterprise-grade performance requirements. Residential users and small office environments increasingly demand seamless coverage, low-latency gaming or streaming performance, and reliable mesh connectivity. At the same time, businesses are migrating toward software-defined wide area networking, cloud-managed infrastructure, and automated traffic routing. Bridging these two demand profiles is not merely a question of features; it requires distinct supply chain priorities, firmware roadmaps, and service models. Manufacturers that attempt to serve both segments with a single platform often struggle to optimize for latency-sensitive commercial deployments while keeping residential pricing attractive.
A third structural pressure involves supply chain fragility and component cost volatility. High-performance routing devices rely on advanced silicon, memory, and increasingly specialized radios for Wi-Fi 7 and 5G/4G connectivity. When semiconductor availability, pricing, or lead times shift, router makers face rapid adjustments in product roadmaps and margin structures. This exposure is especially acute for companies competing in the mid-tier consumer and small business segments, where margin flexibility is limited and demand cycles can change quickly. The result is a market where production resilience is becoming as important as technical differentiation.
Key Growth Drivers
Technology Innovation and Standards Evolution
The adoption of Wi-Fi 7 and the gradual integration of 5G/4G capabilities into residential and small office routing solutions are expanding both performance ceilings and application scenarios. Wi-Fi 7 introduces higher throughput, improved multi-link operation, and better support for dense device environments, which directly benefits multi-dwelling residential setups and small business locations with concurrent streaming, collaboration, and IoT traffic. Enterprise-oriented platforms are simultaneously advancing through software-defined WAN architectures that enable more granular traffic steering, policy enforcement, and cloud-based management. These advances are making routers less isolated hardware endpoints and more integrated control points within broader network ecosystems.
Policy and Regulatory Environment
The regulatory landscape has become a strategic variable rather than a compliance afterthought. The FCC's Covered List actions demonstrate how national security considerations can influence product eligibility, purchase programs, and channel partnerships almost overnight. For OEMs and distributors, this means that market access planning now requires earlier engagement with certification pathways, documentation requirements, and regional approval processes. Regulatory visibility is increasingly valuable because it shapes which product lines can scale smoothly in key markets and which cohorts may need redesign, regional sourcing shifts, or partnership adjustments.
Demand-Side Behavior and Deployment Patterns
Demand is evolving on two fronts. In residential and small office settings, users are prioritizing reliability, seamless handoff across mesh nodes, and simple management interfaces that reduce IT burden. In commercial environments, buyers are looking for scalable routing platforms that integrate with SD-WAN strategies, simplify data center connectivity, and support address-locating and traffic prioritization across hybrid work models. The common thread is a stronger preference for solutions that reduce operational complexity. Customers increasingly evaluate routers not only by hardware specifications but also by the ease with which the device fits into existing networks, remote management tools, and support ecosystems.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by component dependencies, regional sourcing decisions, and the overhead required to maintain regulatory compliance. Companies that diversify component procurement, build inventory buffers for mission-critical SKUs, and align product planning with certification timelines are better positioned to protect margins during volatility. At the same time, the cost of integrating security features, advanced radio modules, and cloud management capabilities is rising, which pressures manufacturers to differentiate through software value, service bundles, or focused segment strategies rather than hardware-only competition.
Competitive Landscape and Strategy Differentiation
The competitive field reflects a clear divergence in strategic focus. Cisco Systems, Inc., headquartered in San Jose, California, continues to emphasize enterprise and SD-WAN routing solutions, including its 8000 series and Meraki Wi-Fi 7 routing options. Its differentiation rests on scalability, integration with enterprise management frameworks, and support for organizations that require consistent policy enforcement across distributed sites. For commercial buyers, Cisco's positioning signals a willingness to prioritize operational predictability and network automation over price-first consumer positioning.
PW Consulting
Netgear, Inc., also based in San Jose, California, has concentrated on high-speed home and small office networking through its Nighthawk Wi-Fi 7 routers and mesh systems. Its strategy centers on performance perception, ease of setup, and strong consumer brand recognition. Netgear's noted exemption status in certain FCC guidance reflects the reality that regulatory positioning can also influence market continuity and channel confidence, especially for established consumer brands with extensive existing inventory and authorized product histories.
In Shenzhen, TP-Link Technologies Co., Ltd. has built a broad footprint across consumer and mesh Wi-Fi routers, including the Archer Wi-Fi 7 line and 5G/4G series aimed at reliable home networking. Its strength lies in product breadth, cost-effective performance, and widespread retail and channel availability. TP-Link's approach underscores how volume-oriented consumer brands can maintain relevance by continuously refreshing model families and aligning with mainstream residential connectivity expectations.
Wireless Router Market
ASUSTeK Computer Inc., headquartered in Taipei, Taiwan, pursues a premium positioning through Wi-Fi routers that include the ROG gaming series and ProArt models with AI-enhanced features. This strategy appeals to performance-focused users and creators who value low-latency behavior, aesthetics, and feature-rich firmware experiences. ASUSTeK's differentiation demonstrates that premium router segments can command attention by combining performance tuning with specialized use-case branding rather than competing solely on general-purpose coverage.
Beyond individual company strategies, the broader competitive trend points toward selective consolidation in enterprise-grade routing and continued fragmentation in consumer and small business segments. Larger platform vendors are gaining advantage where buyers value integration, security oversight, and long-term manageability. Meanwhile, the consumer space remains crowded with tiered offerings that compete on speed claims, mesh architecture, and brand familiarity. Regulatory developments may further reshape this balance by raising access hurdles for certain foreign-produced consumer models, potentially encouraging regional sourcing, partnership redesign, or accelerated compliance investment among affected players.
Forward-Looking Trends and Commercial Implications
One of the clearest trends over the next three to five years is the continued integration of Wi-Fi 7 and advanced radio capabilities into mainstream router portfolios. As device density grows in homes, apartments, co-working spaces, and small commercial sites, the practical value of multi-link operation and improved interference handling will become more visible in real-world deployments. Commercially, this trend favors vendors that can pair hardware upgrades with firmware maturity, easy migration paths, and support services that help users and small IT teams realize the benefits without specialized networking expertise.
Enterprise Grade Router Market
A second trend is the expanding relevance of regulatory-aware product planning as a strategic capability. The FCC's 2026 actions are unlikely to remain isolated; they indicate that security and sourcing scrutiny can become routine considerations in product launches and market entry decisions. Companies that institutionalize compliance forecasting, maintain flexible manufacturing arrangements, and proactively document approval pathways will be better positioned to avoid launch delays and inventory disruptions. For investors and strategic planners, regulatory readiness should be treated as a growth enabler rather than a legal checkbox.
A third trend is the deepening blend of routing hardware with managed software services. Enterprises increasingly expect cloud-managed control, automated policy deployment, and visibility across hybrid environments. In consumer and small business settings, users prefer interfaces that simplify setup, troubleshooting, and performance optimization. The commercial opportunity lies in bundling routing capability with subscription services, remote monitoring, security add-ons, and extended support, thereby creating recurring value rather than relying solely on hardware unit sales. This shift also introduces risk if service differentiation is weak or if warranty and support expectations outpace operational capacity.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product roadmaps with both performance expectations and regulatory access realities. That means evaluating whether upcoming models depend on components or production locations that could complicate authorization processes, and whether differentiated features are genuine enough to justify margin expectations in crowded consumer or small office categories. Companies should also consider whether enterprise-focused platforms can be modularized or segmented more cleanly from residential lines to avoid internal trade-offs between latency-sensitive commercial needs and price-sensitive consumer demand.
For investors, the most useful lens is the combination of segment dynamics and external pressure sensitivity. Markets with strong secular demand for higher connectivity tiers and software-managed infrastructure offer more durable growth than segments dependent primarily on periodic hardware refreshes. At the same time, exposure to sudden regulatory or sourcing shocks should be weighed against a company's ability to adapt through regional partnerships, product redesigns, or exemption eligibility. Due diligence should extend beyond unit shipment narratives to include supply chain flexibility, certification readiness, and the durability of service-based revenue where applicable.
For procurement and network planning teams, the practical focus should be on total operational fit rather than headline specifications. Evaluate whether a router supports the intended deployment model, whether its management tools match the organization's staffing and skill level, and whether the vendor's supply and compliance trajectory suggests continuity through the planning horizon. Where possible, incorporate regulatory status, warranty structure, and service availability into purchasing criteria, especially for rollouts where replacement cycles or support delays could disrupt business operations.
The market trajectory through 2032 points toward continued expansion, but the composition of winners will depend on how effectively organizations navigate technology adoption, regulatory alignment, and operational simplicity at the same time. For those seeking deeper segmentation data, detailed scenario modeling, and customized strategic recommendations across product lines and regions, the full PW Consulting research report on the router market provides more granular analysis and planning guidance.
For detailed analysis of this topic, please visit the official page: Routers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com