

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Wire Drawing Lubricants Market: Why 5.4% CAGR Signals a $325M Shift

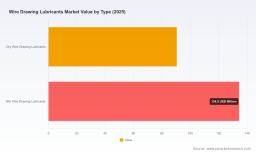
Navigating the Wire Drawing Lubricants Market: Strategic Trends and Commercial Horizons (2026–2032)
The global wire drawing lubricants market is entering a period of disciplined expansion, shaped by material science advances, evolving manufacturing demands, and a volatile input cost environment. Valued at an estimated $225.0 million in 2025, the market is projected to grow at a compound annual growth rate of 5.35 percent through 2032, reaching approximately $325.45 million. This trajectory reflects more than a simple volume or price effect; it signals a structural shift in how lubricants are formulated, applied, and evaluated across the metal forming value chain. As drawing speeds increase, tolerances tighten, and sustainability expectations move from optional to operational, the lubricant segment is becoming a strategic lever rather than a commoditized consumable. For manufacturers, procurement leaders, and investors, the next several years will reward those who can align formulation strategy, supply resilience, and application engineering with the realities of modern wire production.
Market Dynamics and Structural Constraints
Historical performance from 2020 through 2025 illustrates a market that recovered from pandemic-era disruptions and then accelerated as industrial activity normalized and downstream demand broadened. The period demonstrated consistent year-over-year expansion, with the pace of growth supported by higher application intensity in ferrous and non-ferrous drawing operations, alongside incremental adoption of performance-oriented lubricant grades. Looking ahead, the forecast window to 2032 suggests continued expansion, though the nature of that growth is changing. Markets are less likely to advance through undifferentiated product swaps and more likely to be driven by process optimization, yield improvements, and compliance-aligned formulations.
The current landscape also exposes several structural tensions that decision-makers must navigate carefully:
-
Input cost and supply volatility: Base oil pricing dynamics have shifted from stable patterns to episodic adjustments driven by regional refinery conditions, Group II/III supply balances, and freight pressures. These fluctuations compress margins for formulators and can create unpredictable working capital cycles for distributors and end-users alike.
-
Performance versus sustainability trade-offs: High-speed drawing demands lubricants that deliver consistent lubrication films, thermal stability, and surface finish quality, while regulators and corporate procurement teams increasingly expect lower environmental footprints, improved biodegradability profiles, and reduced hazardous substance exposure. Reconciling these priorities requires formulation sophistication rather than simple grade substitutions.
-
Application specialization and process mismatch: As wire producers push toward finer gauges, higher drawing reductions, and multi-stage operations, off-the-shelf lubricants often fail to optimize performance across rod breakdown, intermediate drawing, and fine wire finishing. The resulting inefficiency in lubricant consumption, rework, or line stoppages creates hidden costs that can exceed the initial purchase price by a significant margin.
These pressures are not isolated; they interact to define where value can be captured and where exposure can accumulate. Market participants that treat lubricants as process chemicals with measurable operational impact, rather than generic consumables, are better positioned to manage these constraints.
Key Drivers Reshaping the Market
Technological Innovation and Formulation Intensification
Advancements in lubricant chemistry are shifting the market from basic lubrication toward integrated process performance. Modern wire drawing lubricants are increasingly engineered for draw cleanliness, film stability, and rinsability, with attention to how lubricant behavior interacts with die wear, cooling dynamics, and post-draw surface treatments. Some suppliers frame this through concepts such as total lubricant use efficiency, emphasizing how formulation choices can influence consumption rates, process stability, and emissions intensity over a full production cycle. In practice, this means a growing emphasis on precision-tuned additives, controlled wetting characteristics, and lubricant grades that maintain consistent behavior across multi-pass systems.
For end-users, the strategic implication is that lubricant selection now intersects directly with throughput, surface quality, and rework rates. A lubricant that performs acceptably at moderate draw speeds may fail to support stability when speeds increase or when reductions per pass become more aggressive. Conversely, well-matched formulations can reduce variability, support die life, and improve downstream cleaning outcomes, creating value that compounds across the production line.
Policy and Regulatory Environment
Environmental and occupational regulations continue to shape formulation choices and market acceptance. Producers are navigating a landscape where compliance is no longer a static checklist but an evolving requirement, especially for substances used in metal forming fluids and associated additives. Companies are aligning portfolios with broader environmental expectations, emphasizing product lines designed to reduce ecological impact while maintaining application performance. This regulatory pressure also influences packaging, labeling, disposal considerations, and customer documentation, which in turn affects how lubricants are evaluated in tender processes.
The commercial implication is that regulatory alignment can become a competitive attribute, not merely a cost of doing business. Lubricants that simplify compliance, reduce hazardous handling burdens, or support manufacturer sustainability targets may gain preference in buyer evaluations, especially in regions where environmental management and occupational safety are tightly integrated into operational KPIs.
Demand-Side Shifts in Wire Production
Downstream demand for wire-based products continues to diversify across construction, electrical infrastructure, transportation, fasteners, fencing and mesh applications, and specialized alloy uses. This diversification is pushing wire producers toward broader product ranges, tighter tolerances, and more consistent surface properties. In parallel, certain end markets prioritize finer wire, higher mechanical consistency, and improved drawing efficiency, which increases reliance on lubricants that support repeatability across different materials and diameters.
A notable demand-side dynamic is that buyers are increasingly interested in total system outcomes rather than lubricant price alone. Procurement teams weigh how lubricant behavior affects downstream cleaning, scrap generation, line speed, and operator handling. Where lubricants contribute to smoother process flow and fewer operational interruptions, they may justify premium positioning through measurable operational savings. This is especially relevant in high-throughput environments where marginal improvements in lubricant consistency can translate into meaningful throughput gains.
Supply Chain and Cost Structure Pressures
The cost environment has become more complex as raw material movements influence formulation economics. Pricing volatility in the paraffinic base oil segment, including reported increases in May 2026 from major refiners, reflects conditions in Group II/III supply and refinery operations. At the same time, lubricant producers have implemented multiple rounds of price adjustments since March 2026, citing rising costs for base oils, additives, packaging, and freight, alongside volatility linked to geopolitical instability and energy market conditions. Base oil prices in North America faced additional upward pressure in June 2026, partly influenced by crude movements and constrained Middle East flows.
These dynamics create a dual challenge. For formulators, input cost uncertainty complicates capacity planning, inventory strategy, and margin management. For buyers, price escalation introduces uncertainty into total cost of ownership calculations and encourages a closer look at application efficiency, reuse potential, and consumption control. In this setting, the most resilient strategies often combine supply diversification, formulation flexibility, and closer collaboration between lubricant suppliers and wire producers to manage consumption and waste.
Competitive Landscape and Strategic Positioning
Differentiated Leadership in a Fragmented Market
The market is characterized by a moderately concentrated competitive structure, with the top three firms accounting for roughly 35.2 percent of revenue and the top five reaching about 48.7 percent. This distribution indicates that scale, technical reputation, and application reach matter, but there is still meaningful room for specialization and region-specific strength. The leading players tend to compete on formulation depth, application support, and portfolio breadth across ferrous and non-ferrous materials, rather than on price alone.
Blachford Ltd. positions itself around custom-engineered lubricants, soaps, and additives for both ferrous and non-ferrous wires, with particular emphasis on performance grades for carbon and stainless steel at higher speeds. Carl Bechem GmbH supports a global footprint with product families such as Unopol and Berudraw, targeting copper, aluminum, steel, and alloy wires with tailored lubrication approaches. Holifa Fröhling GmbH & Co. KG builds on a long operational history in drawing oils, pastes, emulsions, and synthetic powders, reinforcing a focus on high-quality metal forming lubricants across the wire industry. Metalube Group Ltd. emphasizes synthetic and advanced solutions for copper and aluminum drawing, with formulations designed for stability, cleanliness, and environmental considerations in high-speed multi-draw settings. Growel Solutions Pvt. Ltd. contributes a regional and application-focused presence through its GRODAL range for copper, aluminum, and steel, including high-lubricity variants suited to rod breakdown and fine wire work. Q8Oils offers full synthetic and semi-synthetic lubricant options aligned with global environmental legislation, covering a broad range of wire sizes and materials, including super-fine wire. CONDAT SA provides soap and lubricant ranges such as VICAFIL and STEELSKIN for steels, carbon steel, stainless steel, and special alloys, alongside surface treatment products that extend the value proposition beyond the drawing stage itself. Klüber Lubrication Deutschland GmbH brings attention to more efficient lubricant use through its Traxit Wire Lubrication line, with claims of reduced lubricant consumption and improved process stability in wire drawing mills.
Across these players, several strategic differentiators emerge:
-
Application engineering and customization: Companies with strong technical service models can tailor grades to specific reduction sequences, materials, and machine configurations, helping customers reduce variability and improve yield.
-
Sustainability-aligned portfolios: Multiple suppliers are positioning products to align with environmental legislation and corporate sustainability goals, using this as both a compliance and differentiation advantage.
-
Process-integrated thinking: Some market participants frame lubricants as part of a broader efficiency and emissions-reduction approach, linking lubricant performance to consumption reduction, energy use, and mill stability.
Near-Term Market Activity and Strategic Signals
Recent company activity reflects the direction of competition. In April 2026, Klüber Lubrication participated in Wire Expo 2026 in Milwaukee, using the event to demonstrate a total lubricant use concept for wire drawing mills that highlights efficiency, sustainability, and CO2 emission reductions through advanced lubrication solutions. Around the same time, Metalube Group introduced Lubricool™ 960, a sustainable wire drawing lubricant grade for copper applications intended to improve process stability and reduce environmental impact in multi-draw machines. Blachford also participated in Wire Expo 2026, showcasing custom wire drawing lubricants and soaps intended to support OEMs with performance enhancements for ferrous and non-ferrous wires.
Taken together, these moves illustrate a broader pattern: competition is increasingly expressed through product refinement, application messaging, and sustainability framing rather than through pure volume or geographic reach. Trade show participation and product launches are being used to communicate capability in ways that matter directly to wire producers' operational priorities. The market appears to be moving toward clearer segmentation by performance need, material type, and sustainability expectation, while still allowing for global suppliers to compete on consistency and support infrastructure.
PW Consulting
The evolving landscape also suggests that consolidation and specialization may proceed along parallel tracks. Larger players may continue to expand through portfolio breadth and application reach, while smaller or regional firms may compete by solving specific formulation, handling, or cost problems for local customer bases. New entrants are most likely to gain traction where they can address a niche need with measurable operational advantage, such as a specialized grade for a particular alloy class, a reduced-consumption system, or a formulation optimized for a specific cleaning or rinsing workflow.
Bearing Lubricant Market
Outlook: Strategic Trends to Watch (2026–2032)
Trend One: Lubricants as Process Efficiency Enablers
Over the next several years, lubricant evaluation is likely to increasingly incorporate total process outcomes rather than isolated performance metrics. This means stronger emphasis on lubricant consumption management, line stability, die wear implications, and downstream cleanliness. Wire producers seeking to reduce variability and improve throughput may prioritize grades that support consistent film behavior under higher speeds and repeated drawing passes. The commercial opportunity lies in pairing lubricant selection with application expertise, so that formulation choices are integrated with machine settings, drawing schedules, and post-draw treatments.
Trend Two: Sustainability as a Core Purchasing Metric
Environmental and regulatory expectations are expected to continue shaping buyer behavior, particularly where sustainability commitments are tied to procurement criteria, reporting requirements, or operational safety goals. Lubricants designed to reduce environmental impact, support cleaner handling, or align with global legislation may gain preference in a wider set of applications. This trend creates opportunities for suppliers that can demonstrate credible product attributes without compromising the performance required for demanding drawing conditions. At the same time, suppliers must manage the risk that sustainability claims are scrutinized more closely, making transparency and consistent product behavior critical.
Trend Three: Cost Resilience Through Formulation and Sourcing Strategy
Given ongoing volatility in base oil markets, feedstock conditions, and freight dynamics, cost resilience will remain a strategic priority. Lubricant formulators and buyers alike may benefit from more flexible sourcing approaches, improved inventory discipline, and formulations that maintain performance while reducing total consumption or waste. The upside for market participants is that firms able to manage input cost exposure while preserving product consistency can strengthen customer relationships during periods of price instability. The risk is that sustained cost escalation could pressure adoption of premium grades unless buyers can clearly connect them to operational savings or quality improvements.
Yarn Lubricant Market
Decision-Maker Playbook: Strategic Actions by Role
For Wire and Metal Forming Manufacturers
-
Treat lubricant selection as a process variable with measurable downstream effects. Evaluate grades based on draw stability, cleanliness, consumption behavior, and compatibility with post-draw treatment steps, rather than focusing solely on price per kilogram or liter.
-
Invest in collaborative application testing with suppliers to match lubricant behavior to your specific reduction sequences, materials, and machine conditions. Tailored trials can reveal whether performance gains in one stage of the operation offset additional cost elsewhere.
For Investors and Strategy Teams
-
Monitor how the market splits between broad-spectrum global suppliers and specialized regional or application-focused players. The most durable value may accrue to companies that combine technical credibility with the ability to support demanding, high-speed, or sustainability-sensitive applications.
-
Track input cost dynamics and pricing actions as leading indicators of margin pressure and demand responsiveness. Companies that can navigate base oil volatility while maintaining consistent product quality may be better positioned to protect share and profitability.
For Procurement and Supply Chain Leaders
-
Broaden total cost assessments to include consumption, rework, cleaning burden, and process stability. This approach can help distinguish lubricants that appear comparable on list price but differ materially in operational impact.
-
Strengthen supplier relationships that offer formulation flexibility, supply continuity, and clear documentation for regulatory or sustainability requirements. In a volatile cost environment, reliability and transparency can be as valuable as marginal price advantages.
The wire drawing lubricants market is evolving in a way that favors informed, application-aware decision-making. As performance expectations rise and input cost volatility persists, organizations that understand the intersection of formulation, process behavior, and supply resilience will be better equipped to capture value and manage risk. For leaders seeking a deeper operational and commercial view of how these dynamics play out across regions, material types, application contexts, and competitive segments, PW Consulting's full market research report offers more granular segmentation data and tailored strategic guidance for navigating the 2026–2032 outlook.
For detailed analysis of this topic, please visit the official page: Wire Drawing Lubricants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com