

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Lamination Adhesives for Flexible Packaging: The 5.9% CAGR Story and Key Strategic Shifts

Strategic Shifts and Commercial Opportunities in the Lamination Adhesives for Flexible Packaging Market
The global market for lamination adhesives used in flexible packaging has entered a decisive growth phase, expanding from approximately $163 million in 2020 to an estimated $212 million in 2025. Valued at $222 million in 2026, the market is projected to cross $312 million by 2032, reflecting a consistent compound annual growth rate of 5.9 percent across the 2020–2032 evaluation window. This trajectory signals more than steady expansion; it marks a structural transition where performance requirements, regulatory expectations, and formulation chemistry are reshaping demand patterns at the same pace as volume growth.
Commercial momentum in this segment is increasingly driven by formulators, converters, and end-use packaging producers who must balance technical reliability with sustainability mandates, cost volatility, and recyclability goals. The market’s scale, combined with its accelerating pace of change, makes it a strategically important category for organizations that design packaging systems, manage specialty chemical procurement, or evaluate materials investments. Understanding where value is shifting—and why—offers a clearer path to competitive positioning than headline figures alone.
Market Snapshot and Core Inflection Points
The market’s progression from $163 million in 2020 to $212 million in 2025 reflects a mature yet still expanding base. Because lamination adhesives are embedded across a broad range of flexible packaging formats, demand is influenced by multiple downstream dynamics rather than a single application cycle. The size of the segment has consistently grown year over year, with the 2020–2025 historical period establishing a clear upward baseline that sets the stage for the 2026–2032 forecast horizon.
A defining feature of this market is its moderate concentration. With the top three players collectively representing 24.6 percent of market revenue and the top five accounting for 26.2 percent, no single company controls the category. This fragmentation creates room for differentiated positioning based on chemistry, application expertise, and regional responsiveness. It also means that strategic moves by mid-sized and regional players can influence pricing, availability, and innovation cycles in ways that broad-market data alone may not capture.
Several structural inflection points are shaping the near-term trajectory of the market:
- Regulatory alignment with packaging design. Extended producer responsibility frameworks and recyclability expectations are pushing converters and brand owners toward adhesive systems that support delamination, compatibility, and waste-stream performance. Adhesives are no longer evaluated only for bonding strength and process reliability; they are increasingly assessed as part of packaging end-of-life design.
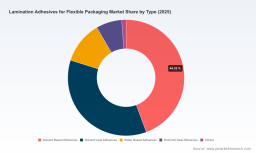
- Formulation trade-offs around performance and environmental profile. The portfolio of lamination adhesives spans multiple chemistry families, each with distinct drying, curing, solvent management, and application characteristics. As converters adjust line speed, material combinations, and curing constraints, the balance between solvent-based, solvent-free, water-based, and seal-type systems is shifting in response to both operational and compliance priorities.
- Input cost volatility affecting procurement planning. Fluctuations in feedstock markets, including oil-linked raw material pathways, have added complexity to cost forecasting for lamination adhesive production. Producer price indicators for adhesive manufacturing have reflected elevated pressure, prompting manufacturers and converters to revisit formulation economics, inventory strategies, and contract structures.
Together, these forces suggest that growth in the market is not simply a function of volume expansion in flexible packaging. It is increasingly tied to which adhesive systems can meet evolving processing requirements, regulatory expectations, and cost realities while preserving performance quality.
Key Drivers Reshaping Demand and Competitive Positioning
The direction of the market is being shaped by a combination of technology advancement, regulatory momentum, downstream demand behavior, and supply-side cost dynamics. Each driver influences not only how much adhesive is consumed, but which systems gain preference in specific applications and regions.
Technology Innovation and Formulation Evolution
Innovation in lamination adhesives is concentrated on three practical fronts: improving bonding performance on varied substrates, reducing or eliminating solvents and VOC-related handling burdens, and supporting end-of-life behavior such as recyclability and material recovery. Solvent-free and water-based systems have gained attention as converters seek to reduce emissions, simplify process controls, and align with brand owner sustainability commitments. At the same time, solvent-based and cold/hot seal adhesives continue to serve segments where speed, adhesion, and specific packaging formats create strong performance requirements.
Companies that have invested in differentiated portfolios are using these technical advances as competitive levers. For example, some suppliers have emphasized compostable or eco-conscious lamination adhesive formulations alongside solvent-free polyurethane options for flexible packaging. Others have built broad laminating adhesive brands covering solvent-based, water-based, and solvent-free products to address a wider range of converter needs. In addition, strategic acquisitions have expanded product reach; a notable transaction in late 2024 saw a leading specialty materials group complete a purchase of a flexible packaging laminating adhesives business, adding both solvent-based and solventless offerings to its portfolio. This type of move signals that scale, product breadth, and application knowledge are becoming central to sustained competitiveness.
Regulatory and Compliance Pressure
Regulatory developments are increasingly shaping formulation preferences and packaging design decisions. In the United States, multiple states have enacted packaging extended producer responsibility laws, and these frameworks are influencing how adhesives fit into recyclable packaging design. Adhesives play a meaningful role in recyclability outcomes, and their selection can support designs that are easier to process in recovery systems. For lamination adhesives, this creates a direct line between product chemistry and compliance strategy.
The regulatory conversation is also moving into industry events and standard-setting discussions, with upcoming conference programming highlighting the impact of regulation on the adhesives sector. As a result, suppliers and converters are paying closer attention to compatibility, separation behavior, and the broader claims environment around packaging sustainability. This shift is not merely a compliance issue; it is reshaping procurement criteria, because brand owners and converters increasingly favor systems that can demonstrate alignment with emerging recycling and responsibility requirements.
Demand-Side Shifts in Packaging End-Use Segments
Demand growth is concentrated across application areas where flexible packaging remains essential, particularly food packaging, which represents the largest segment of adhesive demand. Medical packaging also contributes a meaningful share of demand, driven by barrier requirements, hygiene considerations, and the need for reliable lamination performance in sensitive applications. Industrial packaging and other uses make up the remainder of the demand base, each with distinct performance thresholds and material pairings.
The common thread across these segments is a growing expectation that packaging performance and sustainability goals be addressed together. Food brands and retailers are increasingly concerned with both product protection and packaging end-of-life outcomes. Medical and industrial users prioritize reliability, but they are also exposed to broader procurement standards that evaluate environmental footprint and compliance. As these expectations rise, demand for lamination adhesives that can meet multiple objectives—adhesion, processability, and recyclability compatibility—tends to strengthen, supporting the broader market trajectory.
Supply Chain Cost Dynamics and Procurement Strategy
Cost volatility has emerged as a persistent structural factor. Raw material price movements, including those tied to oil-sensitive inputs, have contributed to higher production costs across lamination adhesives for flexible packaging. Producer price data for adhesive manufacturing has reflected this pressure, with index readings indicating a sustained elevation in cost levels as of mid-2026. For manufacturers and converters, this introduces a more complex planning environment where formulation costs, inventory positioning, and contract terms must account for fluctuating input prices.
In practice, cost pressure is pushing organizations to think beyond unit pricing. Buyers are weighing total cost of ownership, process efficiency, rework risk, and compatibility with recycling-oriented design. Suppliers, meanwhile, are adjusting portfolios and service models to help customers manage price variability without sacrificing performance. The interaction between cost volatility and performance requirements is likely to remain one of the most important commercial dynamics in the market during the forecast period.
Competitive Landscape and Strategic Positioning
The market’s moderate concentration and diverse product base create a competitive environment where several strategies can succeed. A subset of global specialty chemical and adhesives companies competes on portfolio breadth, brand recognition, and application support, while regional and mid-sized players compete on responsiveness, localized supply, and formulation adaptability.
Several incumbent players illustrate the range of strategic approaches in the market:
- H.B. Fuller Company has positioned itself around specific lamination adhesive offerings for flexible packaging, including compostable lamination adhesives and solvent-free polyurethane options. This focus highlights a strategy oriented toward sustainability-aligned formulations and targeted application performance.
- Henkel AG & Co. KGaA maintains a well-recognized laminating adhesive brand portfolio covering solvent-based, water-based, and solvent-free products. Its approach emphasizes broad chemistry coverage and a strong branding and distribution presence across multiple packaging application needs.
- Arkema Group has expanded its packaging adhesives footprint through the acquisition of a flexible packaging laminating adhesives business in late 2024. The transaction added solvent-based and solventless product capabilities, reinforcing a strategy centered on strengthening portfolio depth and market reach in flexible packaging.
- Bostik competes with packaging and lamination adhesives that include solvent-free and water-based solutions for flexible packaging, supporting converters seeking alternatives to solvent-intensive systems.
- 3M Company offers laminating adhesive products for flexible packaging applications, leveraging its broader materials and industrial portfolio to serve packaging converters and brand owners.
- DIC Corporation , COIM Group , Flint Group , Ashland Inc. , and Jowat each bring distinct regional, technical, or application advantages, typically competing on specialized formulations, converter relationships, and localized service capabilities.
- Brilliant Polymers Pvt. Ltd. participates from an emerging regional base and has showcased advanced laminating adhesive solutions for flexible packaging, including solvent-free and eco-conscious formulations. Industry activity such as its exhibit presence at Interpack 2026 reflects ongoing visibility-building by suppliers targeting sustainability-minded converters.
The competitive landscape is evolving along several axes. One is consolidation through acquisition, which widens product portfolios and can accelerate access to specific technologies or customer relationships. Another is segmentation by chemistry and application, where suppliers differentiate not just on price but on drying behavior, curing requirements, compatibility with substrate combinations, and alignment with recycling or sustainability goals. A third is regional dynamics, where local supply responsiveness and regulatory familiarity can be as important as global brand presence.
This combination of consolidation, differentiation, and regional specialization means the market is neither purely consolidated nor purely fragmented. Instead, it is becoming increasingly layered, with global portfolios competing alongside focused regional players that can adapt quickly to converter needs and local compliance expectations.
Worldwide Medicine Packaging Adhesive Market
Future Trends and Commercial Implications
Looking across the 2026–2032 horizon, three trends are likely to shape how value is created and captured in this market.
Convergence Around Recyclability-Ready Adhesive Systems
As extended producer responsibility laws expand and packaging design increasingly emphasizes recyclability, adhesives that support material separation and recovery will become more commercially relevant. This is likely to increase demand for formulations that balance lamination performance with compatibility in recycling streams, encouraging both product development and procurement shifts. The commercial opportunity lies in positioning adhesive solutions as part of the packaging system rather than as a standalone process input.
Accelerated Adoption of Solvent-Free and Lower-Impact Formulations
Solvent-free and water-based systems are expected to continue gaining traction where converters can accommodate changes in process conditions and where sustainability or emissions objectives are prioritized. At the same time, solvent-based and seal-type adhesives will remain important for applications that require specific performance characteristics. The commercial implication is that suppliers will increasingly need to offer choice, guidance, and transition support rather than relying on a single chemistry to meet broad demand.
Cost Volatility Driving Procurement and Portfolio Strategy
Raw material price pressure is likely to persist as a strategic variable, influencing both supplier pricing and buyer behavior. In response, organizations may place greater emphasis on formulation efficiency, supply continuity, and contractual flexibility. The market’s moderate concentration means that customers often have multiple sourcing options, which can increase negotiation leverage but also requires careful evaluation of performance, sustainability fit, and regional availability. Suppliers that can help customers manage cost variability without compromising downstream performance will be better positioned to retain and expand relationships.
These trends carry uncertainty. Regulatory timelines, recycling infrastructure maturity, and raw material price movements can all alter the pace of adoption for specific adhesive types. In addition, the performance trade-offs between chemistry families mean that product transitions are often application-specific rather than uniform across the market. Firms that treat recyclability, cost, and formulation flexibility as interconnected choices are more likely to navigate that uncertainty effectively.
Actions for Executives and Decision-Makers
The commercial direction of lamination adhesives for flexible packaging is being shaped by intersecting forces: sustainability and compliance expectations, formulation innovation, cost volatility, and a competitive landscape that rewards both portfolio breadth and focused application expertise. For decision-makers, the most useful response is to align adhesive strategy with broader packaging objectives rather than treating adhesives as a generic procurement line.
For manufacturers and converters, the priority is to evaluate adhesive portfolios against process requirements and recyclability considerations simultaneously. This includes assessing how different chemistry families perform on target substrates, how transitions to solvent-free or water-based systems affect line speed and curing, and how adhesive selection supports packaging end-of-life goals under evolving regulatory frameworks. Close coordination between procurement, engineering, and sustainability teams can reduce the risk of choosing an adhesive that performs well in one dimension but creates friction in another.
PW Consulting
For investors and corporate strategy teams, the attractive signals are not limited to overall market growth. The more strategically relevant question is which companies are building durable advantages through differentiated formulations, targeted acquisitions, and strong application support. Portfolio expansion through acquisition, visible participation in major industry venues, and clear positioning around compostable, solvent-free, or water-based solutions all point to how firms are competing for share in a market where performance and compliance increasingly intersect.
For purchasing and sourcing leaders, the practical emphasis should be on total value rather than headline price alone. Cost variability makes contract design, supply reliability, and formulation support increasingly important, especially when adhesive choice affects downstream recyclability, rework risk, or compliance exposure. A structured evaluation framework that includes performance, sustainability alignment, and regional supply resilience can help buyers navigate a market where multiple viable options often exist for the same application.
For organizations seeking a deeper, application-level understanding of demand distribution, regional dynamics, and formulation splits, the full research report provides more granular segmentation data and customized interpretive guidance. That level of detail can be particularly useful when selecting adhesive strategies for specific packaging formats, evaluating supplier fit, or modeling the commercial impact of regulatory and cost changes over the 2026–2032 forecast period.
Worldwide Bioadhesives Market
For detailed analysis of this topic, please visit the official page: Lamination Adhesives for Flexible Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com