

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
金属氧化物变阻器市场:6.2% CAGR如何重塑2026-2032年格局与战略机遇

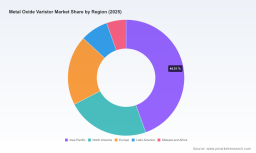
Strategic Trends and Commercial Opportunities in the Metal Oxide Varistor Market
The Metal Oxide Varistor (MOV) market has entered a phase of steady, compounding growth driven by the universal need for reliable surge protection across increasingly complex electronic ecosystems. Valued at approximately USD 1,105 million in 2020, the market expanded to around USD 1,482 million by 2025, reflecting a trajectory shaped by electrification, connectivity, and stricter safety standards. Projections indicate continued expansion through 2032, with revenues anticipated to cross the USD 2,250 million threshold. The compound annual growth rate of 6.2% observed across the forecast window suggests that demand will remain resilient, supported by broad-based adoption rather than reliance on a single cyclical sector. At the same time, market concentration remains notable, with the top three players capturing roughly 60% of revenue and the top five accounting for about 80%, signaling a landscape where scale, technical differentiation, and regulatory readiness create meaningful barriers to entry.
Closing the Growth Gap Between Core and Niche Segments
The market’s overall expansion masks a structural imbalance between high-volume application categories and more specialized use cases. Consumer electronics and automotive electronics continue to anchor demand, while industrial equipment, telecommunications, and energy systems contribute meaningful but less concentrated volumes. This uneven distribution creates both a growth engine and a vulnerability: when design wins in automotive or consumer platforms accelerate, the market benefits from multi-year volume commitments, but when those cycles soften, the burden shifts to industrial and infrastructure projects that move at slower procurement speeds. The strategic challenge is no longer discovering new demand, but ensuring that product portfolios and supply capabilities align with the cadence of each vertical’s adoption curve.
Leadership in this environment requires a portfolio approach that balances commodity-like disc configurations with engineered blocks, straps, and rings tailored to specific energy-handling and form-factor requirements. Companies that can standardize high-volume production while retaining the flexibility to adapt to higher-energy or space-constrained applications are better positioned to capture the upside when end-market momentum shifts.
Cost Volatility and the Margin Squeeze
Raw material dynamics have become a central pressure point. Fluctuations in zinc and related input costs introduce direct risk to pricing stability and margin management, particularly for manufacturers operating in highly competitive, specification-driven segments. Unlike differentiated semiconductor components, varistors often compete against functionally similar alternatives, which limits the ability to pass through cost increases without eroding customer relationships or design wins. The result is a market where procurement strategy and material sourcing are as commercially consequential as R&D investment.
Firms that build robust hedging frameworks, diversify supplier bases, and maintain transparent communication with customers about pricing mechanisms tend to fare better during commodity cycles. Equally important is the ability to offer value beyond unit price, such as certification support, thermal performance documentation, and lifecycle reliability data, which can create justified differentiation when pure cost competition intensifies.
Regulatory Alignment as a Commercial Gatekeeper
Compliance is increasingly a prerequisite for market access rather than a technical footnote. Environmental and safety expectations around lead-free and halogen-free formulations, along with region-specific certification regimes, shape design choices and approval timelines. For global suppliers, the burden is not only to meet standards but to demonstrate consistency across product lines in a way that reduces re-qualification effort for customers operating in multiple jurisdictions. This regulatory layer is reshaping the competitive field, favoring organizations that invest early in testing infrastructure and documentation discipline.
Key Drivers Reshaping the Metal Oxide Varistor Market
Technological Innovation in Surge Protection Form Factors
Innovation in MOV design is moving along two parallel tracks: higher energy-handling capability in compact footprints and improved surge resilience in surface-mount and edge-protection configurations. These developments matter because end-product miniaturization and higher system density increase the consequences of transient events. A varistor that can deliver equivalent or better clamping performance within tighter spatial constraints directly enables design engineers to protect sensitive microcomputers, power steering modules, solar inverters, and automotive control units without compromising layout efficiency.
Recent specification updates from established players illustrate this trajectory. Improvements to G-series metal oxide varistor parameters and operational refinements signal continued iteration toward tighter tolerances and better performance under repeated stress. At the same time, product catalog expansions emphasizing high-energy blocks for distribution and station arresters show that demand for robust surge protection is extending beyond consumer and automotive volumes into power infrastructure applications.
For businesses, the strategic implication is clear: technology leadership in this category is less about unveiling a single breakthrough and more about sustained iteration that tightens performance margins, supports certification pathways, and simplifies integration. Suppliers that can provide consistent parametric behavior across batches reduce the qualification burden for OEMs and become preferential partners in high-volume programs.
Policy and Regulatory Environments Tightening Design Requirements
Regulatory frameworks are converging on stricter material constraints and more rigorous validation expectations. Lead-free and halogen-free formulations are now baseline expectations for many automotive, industrial, and consumer programs, while regional certifications such as UL, VDE, and CQC influence the feasibility of entering specific markets. The commercial effect is twofold: compliance reduces the addressable market for suppliers that lag behind, and it raises switching costs for customers who have already validated specific product families against these standards.
The trend is visible in recent accreditation and certification activity. One major manufacturer obtained CNAS accreditation for its testing center and completed achievement evaluation for high-performance miniature surface-mount varistors, reinforcing its ability to support qualification work internally and shorten development cycles for customers. Separately, multiple product lines from leading firms are explicitly documented as compliant with lead-free and halogen-free expectations, aligning with RoHS-aligned procurement requirements. These moves are not merely compliance checkboxes; they are positioning statements that enable participation in programs where qualification lead time and documentation integrity are competitive differentiators.
The broader lesson is that regulatory readiness is becoming a market-access strategy. Companies that treat certification and testing as core capabilities rather than downstream administrative tasks can accelerate customer adoption, reduce rework, and support multi-region launches more efficiently.
Demand-Side Shifts in Automotive and Industrial Electronics
Demand is being reshaped by electrification, vehicle electronics proliferation, and industrial automation. Automotive platforms are incorporating more electronic control units, power electronics, and microcomputer supplies, all of which increase the need for transient protection across power steering, charging, and auxiliary systems. Industrial equipment is facing similar pressure as factories, instrumentation, and control systems become more connected and sensitive to voltage disturbances. Telecommunications and energy infrastructure add further demand, particularly where lightning arresters and high-voltage power systems require durable surge suppression.
This demand dispersion creates diversified revenue streams but also complicates forecasting. Automotive programs tend to lock in volume through long design-in cycles, while industrial and energy projects can be more episodic and dependent on capital expenditure timing. Firms that understand these cycles and align their production planning, packaging formats, and technical support accordingly can convert demand variability into a more predictable operating model.
From a commercial standpoint, the opportunity lies in matching product architecture to application physics. A surface-mount varistor optimized for automotive SMD applications has different value propositions than a high-energy disc engineered for lightning arresters. Suppliers that segment their engineering support and commercial messaging by application are better equipped to convert technical needs into repeatable design wins.
Supply Chain and Cost Structure Realignment
Supply chain considerations are moving from implicit background risk to an explicit boardroom topic. Raw material sensitivity, manufacturing concentration, and certification dependencies mean that single-source dependencies can quickly translate into program risk. At the same time, customer expectations for consistent availability and validated quality are rising, especially in automotive and industrial segments where component reliability is tightly linked to system warranty and safety exposure.
The response from mature participants has been to diversify sourcing, invest in testing infrastructure, and strengthen documentation of material compliance and performance repeatability. These actions help reduce exposure to commodity swings and improve resilience against regional disruptions. They also support pricing strategies that are less vulnerable to outright cost-based competition because they emphasize reliability, qualification support, and supply assurance.
For buyers and manufacturers alike, supply chain strategy is no longer a separate function from product strategy. The ability to guarantee traceable materials, stable parametric performance, and timely replenishment is part of the value proposition, particularly when surge protection components are embedded into systems with long service lives and high replacement costs.
Competitive Landscape and Winning Strategies
Established Leaders and Their Strategic Positioning
The market features a mix of global incumbents and regional specialists, each leveraging different strengths. TDK Electronics focuses on SIOV series metal oxide varistors for surge protection in automotive, industrial, and power electronics, with an emphasis on material compliance and technical refinement across NT, Standard, and G-series variants. Littelfuse emphasizes high-surge transient protection through AUMOV, UltraMOV, TMOV, and SM10 automotive SMD MOV series, targeting applications where repeated surge tolerance and automotive-grade reliability are critical. Bourns supports electronics protection with MOV radial leaded, IsoMOV, EdgMOV, and BVRA series, broadening its reach across board-level and edge-protection needs.
Worldwide Multilayer Varistor Market
In China, Songtian Electronics offers zinc oxide varistors in 6KV/3KA and high-energy series backed by UL, VDE, and CQC certifications, positioning around cost-effective compliance and broad certification coverage. Xi’an Tian Gong Electric (TGE) concentrates on high-performance MOV disks and blocks for lightning arresters and high-voltage power systems, aligning its portfolio with infrastructure-grade energy handling. Nippon Chemi-Con Corporation supplies metal oxide varistors for applications such as power steering, solar inverters, and automotive microcomputer supplies, tying its offering to specific system-level use cases. Complementing these are MDE Semiconductor with MOV series for high-energy transient protection, Thinking Electronic Industrial with varistors for surge protection applications, and Semec Technology Company Limited with varistors for electronic circuit protection, each contributing to a competitive field that spans commodity and engineered solutions.
Differentiation Levers That Matter
In a market with meaningful concentration, differentiation is rarely about a single feature. Winners typically combine several levers:
- Technical consistency, including stable clamping behavior, repeatable energy handling, and well-characterized thermal performance
- Certification breadth and testing capability that reduce customer qualification time and support multi-region launches
- Form-factor flexibility spanning discs, blocks, straps, and rings to fit diverse layouts and energy requirements
- Compliance with lead-free and halogen-free expectations to meet automotive, industrial, and consumer procurement standards
- Supply assurance and documentation discipline that mitigate disruption risk in long-lifecycle programs
These levers reinforce one another. A supplier that can demonstrate certified, environmentally compliant components with reliable batch-to-batch performance lowers risk for design engineers and purchasing teams alike, making it easier to secure and retain design wins.
Worldwide Transient Voltage Suppressors Market
Market Evolution: Consolidation, Segmentation, and New Entrants
The competitive field is evolving through a combination of consolidation among scaled players and segmentation by application and performance tier. High-volume consumer and automotive programs reward scale, qualification depth, and program management, while infrastructure and high-energy applications reward specialized engineering and field-proven reliability. This dual structure creates room for both market leaders and focused specialists, but the margin for undifferentiated commodity entrants is narrowing.
New entrants can still find pathways in niche energy levels, region-specific certifications, or cost-optimized configurations for non-automotive industrial use, but they must overcome the trust and validation threshold that established players have built over multiple qualification cycles. The more probable trajectory is continued sharpening of positions: incumbents expanding technical and compliance capabilities to protect high-value programs, and specialists pushing into applications where performance, certification, or regional relationships provide a credible edge.
For observers of the market, the key signal is that competitive advantage is increasingly linked to the ability to reduce total qualification and supply risk for customers rather than to demonstrate a single standout specification. That shift favors organizations that integrate product engineering, testing, compliance, and program support into a coherent commercial offering.
Forward Outlook: Trends and Commercial Implications for 2026–2032
Trend 1: Application-Embedded Protection as a Default Design Requirement
Surge protection is increasingly treated as a baseline design requirement rather than an optional safeguard, especially in automotive, industrial automation, and connected infrastructure. As systems become more sensitive and more interconnected, transient events carry higher consequences for reliability, warranty exposure, and operational downtime. This trend supports continued volume growth across core applications and opens incremental opportunities in adjacent categories where protection has historically been under-specified.
The commercial implication is that suppliers should expect more explicit specification activity earlier in the design cycle. Components that are easy to integrate, well-documented, and certified across relevant standards will have an advantage in earning early design consideration, which often translates into longer program lifecycles.
Trend 2: Higher-Energy Blocks and Infrastructure-Linked Demand Gains Importance
While discs and surface-mount devices remain essential for board-level protection, high-energy blocks for lightning arresters and high-voltage power systems are gaining visibility as grid resilience and infrastructure hardening receive greater attention. Recent catalog activity emphasizing energy blocks for distribution and station arresters reflects this broadening of relevance. The growth of solar inverters, renewable integration, and industrial power systems adds further impetus, linking MOV demand to energy transition and infrastructure modernization themes.
This trend creates a differentiated commercial lane. High-energy applications often involve longer evaluation cycles, stricter field reliability expectations, and more demanding thermal and surge conditions. Suppliers that can demonstrate robust performance in these conditions, supported by credible testing and certification, can build defensible positions even in a concentrated market.
Trend 3: Compliance and Testing Capability Become Strategic Assets
Over the next three to five years, the competitive importance of testing infrastructure, certification coverage, and material compliance documentation is likely to increase. As qualification requirements become more consistent across regions and programs, the ability to internally validate performance, maintain accredited testing capacity, and deliver compliant material data will reduce customer friction and accelerate adoption. This is particularly true in sectors where design changes are costly and re-qualification cycles are long.
The upside for capable suppliers is not just volume growth but stickier customer relationships. Once a component family is validated against regional certifications and embedded into a system design, switching typically requires compelling justification. That dynamic rewards organizations that invest early in compliance and testing as part of their product strategy.
Risks and Uncertainties to Monitor
Several uncertainties could shape the pace and distribution of growth. Raw material cost volatility remains a persistent risk to margin stability and pricing predictability. Regulatory expectations may continue to evolve, particularly around material composition and environmental compliance, which could raise the bar for product refreshes and documentation. Demand timing in industrial and energy segments can be uneven, tied to capital expenditure cycles and infrastructure budgets rather than consumer purchasing patterns. Finally, competition from alternative surge protection approaches or substitute components could pressure specific segments, especially where form-factor or cost constraints dominate.
These risks do not negate the growth outlook, but they argue for disciplined portfolio planning. Suppliers and buyers alike should monitor commodity trends, certification updates, and application-level demand signals rather than relying on aggregate market growth alone to guide decisions.
Actionable Recommendations for Decision Makers
For Manufacturers and Product Strategists
Align product portfolios to application physics rather than treating the market as a single volume pool. Maintain a core of high-volume disc and surface-mount solutions while investing in engineered blocks, straps, and rings that serve higher-energy or space-constrained applications. Treat compliance and testing as strategic capabilities: accredited testing capacity, broad certification coverage, and documented lead-free and halogen-free formulations can shorten customer qualification cycles and support multi-region programs. Build pricing and sourcing strategies that reduce exposure to raw material volatility, and ensure that value messaging goes beyond unit price to include qualification support, reliability documentation, and supply assurance.
For Investors and Investors Evaluating Exposure
The market’s growth profile is credible, but value capture is uneven. Favor participants with differentiated technical capabilities, credible certification and testing infrastructure, and exposure to application segments with stronger design-in momentum such as automotive electronics and industrial equipment. Pay attention to how companies manage commodity sensitivity and whether they have the portfolio breadth to shift emphasis as demand cycles move between consumer, automotive, and infrastructure applications. In concentrated markets, scale and qualification depth often translate into better commercial resilience, but specialist positions can be attractive where they serve high-energy or region-specific needs with clear barriers to imitation.
For Procurement and Engineering Teams Sourcing Surge Protection
Prioritize total qualification risk and long-term supply reliability alongside unit cost. Evaluate suppliers on certification breadth, material compliance documentation, batch-to-batch consistency, and the ability to support design-in with technical data that reduces validation effort. Where programs span multiple regions or long service lives, choose components and suppliers that can demonstrate repeatable performance and transparent compliance across standards. Consider building dual-sourcing or qualification pathways for critical applications, especially where raw material sensitivity or single-region dependencies could introduce disruption risk.
Closing Perspective
The Metal Oxide Varistor market is moving through a period where growth is supported by broad demand, but competitive advantage is increasingly determined by technical consistency, regulatory readiness, and supply resilience. The combination of steady top-line expansion, application dispersion, material cost sensitivity, and deeper compliance expectations creates a landscape in which the winners are those that reduce customer risk across the full lifecycle of a design, not just at the point of purchase. For organizations operating in or adjacent to this market, the most valuable next step is to connect these trends to specific application roadmaps, qualification timelines, and sourcing strategies with detailed, segment-level data. Comprehensive research that maps regional revenue splits, application breakouts, and company-level product positioning can turn these strategic observations into concrete decisions, and readers seeking that granularity can explore the full PW Consulting report for deeper segmentation, forecasting detail, and tailored recommendations.
PW Consulting
For detailed analysis of this topic, please visit the official page: Metal Oxide Varistor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com