

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Poly Aluminium Chloride Market: 6.8% CAGR, Asia and Water Treatment Shift the Landscape

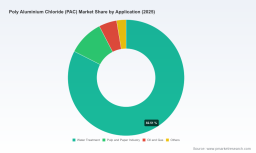
Poly Aluminium Chloride Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global market for Poly Aluminium Chloride (PAC) has matured into a strategically significant segment of the industrial water treatment and process chemicals landscape. Over the historical period from 2020 to 2025, the market demonstrated consistent expansion, with revenue climbing from approximately 1.30 billion USD to 1.80 billion USD. This trajectory reflects a compound annual growth rate of roughly 6.8 percent when projected through 2032, positioning the segment to reach an estimated 2.83 billion USD by the end of the forecast window. The growth is not merely a function of broader economic recovery; it is anchored in structural shifts around water security, regulatory tightening on industrial effluents, and evolving supply chain dynamics that reward manufacturers who can balance cost efficiency with product consistency.
For executives and investors, the headline numbers tell only part of the story. The underlying market architecture is shaped by regional demand imbalances, formulation preferences across liquid and solid formats, and a competitive field that remains moderately fragmented despite the presence of several globally active producers. Understanding how these forces interact is essential for positioning capital, capacity, and sourcing strategies in a market where operational discipline and compliance readiness increasingly separate winners from followers.
Market Status and Core Challenges
The current state of the PAC market is defined by steady demand pull, particularly from municipal and industrial water treatment applications, coupled with a supply environment that has grown more nuanced in recent years. Liquid formulations continue to hold the largest share by revenue, reflecting their ease of dosing, compatibility with automated treatment systems, and preference in large-scale municipal and continuous industrial operations. Solid formats, including powder and granular variants, remain important for storage flexibility, transport efficiency, and regions where logistics constraints or intermittent dosing patterns favor dry handling. The product mix is therefore not a simple commodity story; it is a function of end-use engineering requirements, regional infrastructure maturity, and the operational preferences of water utilities and industrial plant managers.
At the same time, the market faces several structural challenges that demand strategic attention:
- Raw material volatility and margin pressure. PAC production economics are closely tied to alumina-based inputs and chlor-alkali derivatives, and price movements in these upstream segments have periodically compressed margins. Throughout the first half of 2025, firm water treatment demand combined with tighter supply conditions pushed PAC prices higher, illustrating how quickly cost structures can shift when demand resilience meets constrained availability. Manufacturers with limited pricing power or inflexible procurement contracts face disproportionate exposure, while those with integrated sourcing, regional production footprints, or long-term customer agreements can better absorb swings.
- Regulatory and quality compliance as a market gate. In drinking water applications especially, product acceptance is heavily dependent on conformance with recognized standards and certification regimes. The expectation that PAC products align with the specifications described in the American Water Works Association Standard B408-18 and meet the criteria established in NSF/ANSI 60 for drinking water chemicals has become a practical requirement for market access in many regions. Compliance is not merely a technical checkbox; it shapes procurement decisions, tender eligibility, and the speed at which new capacity can be commercialized. This creates a barrier that favors established producers with validated quality systems and disciplined documentation practices.
- Capacity utilization and regional mismatch. Demand growth is uneven across geographies, and supply has not always kept pace in the locations where it is most needed. In some high-growth markets, logistics costs, local registration requirements, and the time lag between announced investments and operational readiness can create temporary imbalances. For buyers, this translates into variability in availability and lead times. For producers, it raises the question of where to deploy capital for maximum utilization and return, particularly when demand signals are strong but local infrastructure or regulatory timelines introduce execution risk.
These challenges are not isolated; they intersect. A pricing environment shaped by raw material tightness magnifies the importance of certification-led differentiation, because buyers who need guaranteed compliance are often willing to pay a premium for reliability. Likewise, regional supply gaps can be addressed not only by building new capacity but by improving formulation consistency, logistics planning, and application support that reduce the total cost of ownership for the customer.
Key Drivers of Market Change
The expansion of the PAC market is being propelled by a combination of technological, regulatory, demand-side, and supply chain factors. Each driver reinforces the others, and together they shape the strategic choices available to producers, formulators, and downstream users.
Worldwide Poly Ferric Chloride (PFC) Market
Technological Innovation and Product Performance
Innovation in PAC is less about entirely new chemistries and more about precision, consistency, and application-specific performance. Advanced production processes emphasize control over basicity, aluminum content, and particle size distribution, which directly influence floc formation, dosing efficiency, and residual aluminum levels in treated water. For municipal and industrial users, these parameters translate into tangible operational benefits: more predictable coagulation, reduced sludge volumes in certain conditions, and better integration with existing treatment trains. Producers that can deliver tightly controlled grades, supported by robust analytical documentation, are increasingly positioned as solutions partners rather than commodity suppliers. This shift is especially visible in segments where water quality variability or stringent discharge limits require customized treatment approaches rather than one-size-fits-all dosing.
PW Consulting
Policy and Regulatory Environment
Regulatory frameworks continue to be a powerful force shaping both demand and market access. stricter water quality standards, industrial effluent limits, and municipal procurement requirements are expanding the addressable market for effective coagulants while simultaneously raising the bar for product qualification. In drinking water applications, conformance with recognized specifications and certifications has become a practical prerequisite for inclusion in tenders and supply contracts. This regulatory backdrop benefits manufacturers that have invested in quality systems, testing infrastructure, and transparent product documentation, while it raises the entry threshold for smaller or less specialized players. At the same time, regulation is not uniformly applied across regions, which creates both complexity and opportunity: markets with evolving standards often see accelerated adoption of proven chemistries as utilities seek reliable, compliant solutions.
Demand-Side Shifts in Water and Industrial Usage
Demand for PAC is closely linked to the broader imperative of water management across municipal and industrial sectors. Urbanization, expanding industrial activity, and increasing attention to water reuse are driving sustained need for effective clarification and coagulation chemicals. In the pulp and paper sector, PAC is used for process efficiency and effluent management, where consistent product performance can reduce variability in mill operations. In oil and gas applications, PAC supports water treatment steps associated with extraction and processing, where reliable solids removal and compatibility with operational conditions are critical. Beyond these traditional end uses, a wider set of industrial and municipal applications contributes to baseline demand. The common thread is a move toward treatment solutions that are not only effective but also predictable, easy to dose, and supported by technical service that helps customers optimize consumption and minimize downstream issues.
Supply Chain and Cost Structure Evolution
The cost structure of PAC production is influenced by input availability, energy costs, logistics, and the geographic distribution of manufacturing capacity. Recent market signals point to a period in which firm demand and tighter supply conditions contributed to upward price movement during the first half of 2025. This environment underscores the importance of supply chain resilience: producers with diversified sourcing, regional production nodes, and efficient inventory planning are better placed to maintain service levels and pricing stability. For customers, the implication is that supplier selection increasingly involves evaluating not just unit price but also reliability, certification readiness, and the ability to support demand fluctuations without compromising quality. Over time, the market is likely to reward participants who can align capacity deployment with demand concentration while maintaining disciplined cost management.
Competitive Landscape and Leading Strategies
The competitive field in PAC includes a mix of global specialty chemical producers and regionally important manufacturers, each pursuing distinct positioning strategies. Rather than competing solely on price, leading players are differentiating through product reliability, certification portfolios, application expertise, and the ability to serve both municipal and industrial customer bases across multiple geographies.
Several companies illustrate the strategic directions shaping the market. Kemira has emphasized its PAX polyaluminium chloride offerings in both dry and liquid grades, manufactured at multiple global sites for municipal and industrial water treatment. This multi-site footprint supports service continuity and regional responsiveness, while the focus on a defined product family helps build customer familiarity and operational consistency. The company’s recent investment of close to 20 million Euros in its Tarragona, Spain site to expand its drinking water treatment portfolio with a new ACH production line reflects a strategy of aligning capacity additions with demand concentration and compliance-driven market access. Such investments signal that leading producers view regulatory readiness and regional availability as competitive advantages, not just operational details.
USALCO has built a strong position around its DelPAC polyaluminum chloride solutions, with products certified to recognized drinking water and wastewater standards for municipal and industrial clarification. By emphasizing certification and application-specific support, USALCO positions its offerings as suitable for sensitive water treatment uses where documentation and quality assurance carry significant weight. This approach illustrates a broader competitive dynamic: in markets where procurement decisions are influenced by compliance, service reliability, and risk reduction, certification-led differentiation can be as important as price.
Feralco Group supplies polyaluminium chloride solutions for drinking and wastewater treatment across Europe, highlighting the importance of regional specialization and service networks in mature markets. In Europe, where water infrastructure is well developed and regulatory expectations are high, competitive success often depends on consistent supply, technical support, and the ability to integrate with customer operations. Regional players that can combine product reliability with localized service can maintain strong positions even in the presence of larger global competitors.
In India, Gujarat Alkalies and Chemicals Limited (GACL) illustrates the role of regional capacity expansion in shaping supply dynamics. GACL produces both liquid and powder PAC grades at its complexes and has moved to operationalize new powder capacity, including the dispatch of an initial consignment from its Coelho Complex in early 2025. With substantial liquid and powder production capability across its facilities, GACL’s strategy reflects the growing importance of domestic and regional supply in markets where demand growth, localization expectations, and logistics economics create strong incentives for in-region production. The expansion of capacity under recognized product standards also points to the increasing alignment between scale, quality, and market access.
GEO Specialty Chemicals rounds out the picture as a producer focused on polyaluminium chloride for water treatment applications, reinforcing the continued presence of specialized manufacturers that serve specific end-use requirements. Together, these companies show that the market is not dominated by a single model of competition. Instead, it accommodates global players with broad portfolios, regional specialists with strong local service, and production-focused firms that leverage scale and standards to secure position.
Polymeric Aluminum Ferric Sulfate Market
The market concentration remains moderate, with the top three firms holding roughly a quarter of revenue and the top five accounting for less than half. This fragmentation leaves room for both consolidation and continued specialization. The likely evolution is not a swift shakeout but a gradual differentiation in which certified quality, application support, regional availability, and supply reliability become the principal battlegrounds. New entrants will face meaningful hurdles in markets where certification and customer qualification processes are rigorous, but opportunities remain in regions or segments where demand is growing faster than established supply and where localized production or tailored formulations can create value.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape the PAC market and create distinct commercial opportunities. These trends are grounded in the current demand trajectory, regulatory direction, and the way leading producers are investing and positioning themselves.
Trend 1: Compliance-Driven Demand and Certification as Competitive Currency
As water quality expectations and industrial discharge requirements continue to tighten in many markets, PAC products that can demonstrate conformance with recognized specifications will capture a growing share of procurement budgets. This creates an opportunity for manufacturers to build durable customer relationships around documented quality, test support, and tender readiness. Commercially, the implication is that investment in quality systems, certification maintenance, and transparent product data can translate into pricing resilience and longer contract cycles. For buyers, it means that supplier qualification should increasingly emphasize verified compliance and consistency rather than price alone.
Trend 2: Regional Capacity Alignment and Supply Chain Localization
Demand growth is not uniform, and the most attractive opportunities will arise where capacity deployment matches local demand intensity and logistics realities. Producers that align new capacity with high-growth regions, or that strengthen regional supply through distributed production and efficient inventory planning, can reduce lead-time risk and improve service levels. For investors and executives, this suggests that capacity announcements should be evaluated not only on scale but on location, utilization prospects, and the regulatory and logistics context of the host market. There is also an opportunity for suppliers who can offer flexible formats and reliable delivery to customers whose operations depend on steady material availability.
Trend 3: Application Support and Total Cost Optimization
As competition intensifies and customers become more sophisticated, the value proposition is shifting toward total cost of ownership rather than unit price. PAC users benefit when suppliers provide dosing guidance, performance data under local water conditions, and support that helps reduce overuse, minimize sludge handling costs, or improve process stability. Producers that invest in technical service, application testing, and customer education can differentiate themselves in a market where many products appear chemically similar but perform differently in practice. This trend creates commercial opportunity for companies that can pair consistent product quality with meaningful operational support, especially in segments where treatment outcomes directly affect downstream costs.
These trends also carry risks and uncertainties. Raw material cost volatility, energy price swings, and logistical disruptions can undermine margin plans and service reliability. Regulatory expectations may evolve at different speeds across regions, creating complexity for producers that operate across multiple jurisdictions. In addition, demand growth in some segments may be tempered by substitution pressures, alternative treatment approaches, or economic cycles that affect industrial activity and municipal capital spending. Participants should therefore build flexibility into sourcing, pricing, and capacity planning, and avoid assuming that current demand strength will persist without interruption.
Strategic Guidance for Decision Makers
For manufacturers, the priority is to strengthen the foundations that convert product availability into commercial advantage. This means investing in quality consistency, certification readiness, and application support while aligning capacity deployment with demand intensity and regional service needs. Where pricing pressure exists, differentiation through documentation, reliability, and technical service can protect margins better than competing on price alone. At the same time, procurement and production planning should account for raw material volatility and logistics risk, with sourcing strategies that reduce exposure to sudden cost swings.
For investors, the market offers exposure to a segment with steady structural demand, but returns will depend on the quality of execution rather than headline growth alone. The most attractive opportunities are likely to be found where capacity additions are supported by credible demand signals, where certification and compliance create entry barriers that protect incumbentpositioning, and where producers demonstrate disciplined cost management and service capability. Evaluating potential investments should therefore include scrutiny of product qualification status, regional demand concentration, supply chain resilience, and the ability to serve both municipal and industrial customers without overreliance on any single application.
For procurement and sourcing leaders, the practical implication is to broaden evaluation criteria beyond unit cost. Supplier selection should weigh certification conformance, delivery reliability, formulation consistency, and the quality of technical support, especially where treatment performance affects downstream operations or regulatory compliance. Multi-supplier strategies, format flexibility, and long-term agreements with clear quality expectations can reduce risk in a market where availability and compliance are increasingly intertwined. Building a supplier qualification process that accounts for documentation, testing, and service responsiveness will help protect operations against variability in both price and supply.
The PAC market is moving toward a phase in which growth is real but increasingly selective. Revenue expansion will continue to be supported by water treatment demand and regulatory-driven adoption, but competitive outcomes will depend on how well companies manage quality, compliance, regional supply, and customer value. Decision makers who treat PAC as a performance-enabled service input rather than a standalone commodity will be better positioned to navigate pricing volatility, secure reliable supply, and capture the opportunities created by tightening standards and evolving treatment requirements. For those seeking a deeper view of segment-level dynamics, regional demand patterns, and company-specific positioning, the full research report provides the detailed data and customized framework needed to translate these strategic trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Poly Aluminium Chloride (PAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com