

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Intimate Underwear Market 2026: Why 4.85% CAGR Masks Real Growth Drivers

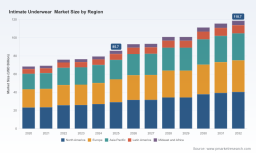
Beyond Comfort: Strategic Shifts Reshaping the Intimate Underwear Market Through 2032
Market Landscape: Growth Trajectory and Structural Headwinds
The global intimate underwear market has entered a phase of steady, compounding expansion. Valued at approximately $68.4 billion in 2020, the sector reached $85.7 billion by 2025, and forward projections indicate a climb toward $118.7 billion by 2032. This translates to a compound annual growth rate of 4.85 percent across the 2026–2032 forecast horizon. The trajectory reflects more than cyclical demand recovery; it signals a structural recalibration of how consumers value foundational apparel, how brands engineer product portfolios, and how supply chains respond to tightening regulatory and sustainability expectations.
Despite the favorable top-line momentum, the industry is navigating a set of intersecting challenges that will separate scalable operators from those trapped in legacy cost structures. Three shifts warrant immediate attention from executives and investors evaluating long-term positioning.
First, the category is experiencing a pronounced value migration from traditional multi-ply apparel architectures toward engineered comfort, seamless construction, and health-adjacent fabric claims. Consumers are no longer purchasing underwear solely for coverage; they are buying daily wear experiences that align with wellness, mobility, and sensory comfort. Brands that continue to compete primarily on volume and price are seeing margin compression as premiumization raises consumer expectations while private-label alternatives erode the mid-tier.
Second, regulatory scrutiny around chemical safety in close-to-skin textiles is accelerating. New testing thresholds and verification mechanisms are raising compliance costs and shortening the window for material substitution. Manufacturers that treat certification as a back-office function are increasingly exposed to sourcing delays, revalidation expenses, and reputational risk. The regulatory environment is shifting from a periodic audit mindset to a continuous compliance discipline.
PW Consulting
Third, the competitive field is fragmenting along performance and positioning lines. A handful of global players hold meaningful share, but concentration remains moderate, which leaves room for specialized entrants, regional champions, and retailer-owned brands to capture niche demand. The result is a market where scale alone no longer guarantees advantage; differentiation in fabric engineering, fit logic, and brand narrative is becoming the primary lever for durable share gains.
Core Drivers Transforming the Category
Technology and Material Innovation as the New Battleground
Innovation in intimate apparel has moved beyond aesthetic styling into material science and garment architecture. The most consequential advances are occurring in microfiber blends, moisture-management textiles, wireless and seamless construction, and graded compression for shapewear. These innovations are not simply feature additions; they are reshaping cost-to-serve, return rates, and consumer retention. Fabrics that improve breathability, reduce friction, and maintain shape through repeated wear cycles directly influence repurchase behavior in a category where comfort is a recurring, not one-time, purchase decision.
Recent exhibition activity underscores how quickly the ecosystem is iterating. At the China (Shenzhen) International Brand Underwear Fair in March 2026, the full intimate apparel value chain gathered to showcase new products, technologies, and applications across brands, buyers, and OEM suppliers. Events of this scale matter because they reveal where capital and engineering attention are flowing. The emphasis on broader ecosystem participation suggests that innovation is no longer confined to branded product development; it is extending into contract manufacturing capabilities, material sourcing partnerships, and process efficiency. For companies evaluating suppliers or building own-brand lines, this points to a market where technical competency at the factory level increasingly determines downstream product quality and time-to-market.
Regulatory Tightening Around Chemical Safety
Regulatory pressure is becoming a meaningful driver of product reformulation and vendor qualification. Effective June 1, 2026, new OEKO-TEX standards introduce tighter limit values and enhanced verification mechanisms for harmful substances in textile certifications. In parallel, bisphenol limits for intimate apparel are being reduced from 1,000 mg/kg to 200 mg/kg following a three-month transition period, with additional attention on BPA limits in women’s intimate underwear and lingerie. These changes are not marginal adjustments; they alter the risk calculus for material selection and supplier oversight.
For decision-makers, the implication is straightforward: chemical compliance is moving from a documentation exercise to a strategic sourcing constraint. Brands that rely on fragmented supplier networks or inconsistent testing protocols will face higher rework risk and longer validation cycles. Conversely, organizations that embed compliance into material selection, use standardized certification frameworks, and maintain visibility into chemical inputs across tiers can convert regulation into a competitive moat. In a category where products are worn directly against the skin for extended periods, safety credibility is becoming part of the value proposition, not just a legal requirement.
Demand-Side Shifts in Consumer Behavior
Consumer expectations are evolving along three reinforcing axes: comfort-first design, inclusive sizing and fit, and greater transparency around materials and production practices. The comfort-first shift is especially pronounced in everyday intimate apparel, where repeat purchases depend on perceived wear quality rather than occasional indulgence. This is driving demand for softer hand-feel fabrics, tagless and seamless designs, and styles that perform across varied daily activities. At the same time, inclusive fit is no longer a peripheral consideration; it is becoming a baseline expectation, which places pressure on sizing architecture, pattern engineering, and inventory planning.
Transparency expectations are also rising, particularly around fiber sourcing, chemical safety, and durability claims. Consumers are increasingly willing to pay for products that communicate clear benefits without overstatement, but they are equally quick to penalize brands that appear vague or inconsistent. This environment favors companies that can articulate a coherent product story grounded in tangible attributes such as fabric composition, construction method, and care performance. Marketing that leans on vague premium positioning is losing traction against specifications that consumers can feel and verify through use.
Supply Chain and Cost Structure Pressures
Cost structures in intimate apparel are being reshaped by raw material volatility, compliance overhead, and the need for faster response to regional demand patterns. Fabric and trims input costs remain sensitive to geopolitical and macroeconomic fluctuations, while labor and logistics costs continue to pressure traditional offshore production models. At the same time, the shift toward higher-performance materials increases reliance on specialized yarns and finishing processes, which can narrow the supplier base and raise switching costs.
These dynamics are encouraging a more deliberate approach to supply chain design. Some manufacturers are consolidating production relationships to secure consistent quality and faster turnaround, while others are diversifying across regions to balance cost, capacity, and risk. Retail and brand buyers are also becoming more exacting about lead-time reliability and certificate traceability. The practical outcome is that cost competitiveness is increasingly tied to supplier governance, quality consistency, and material yield rather than purely to unit labor arbitrage. Companies that treat sourcing as a strategic capability are better positioned to protect margins without sacrificing product integrity.
Competitive Landscape: Positioning, Differentiation, and Evolution
The market features a diverse set of players spanning mass-market basics, premium and luxury positioning, fabric-technology specialists, and private-label suppliers. Several global and regional companies illustrate how strategic positioning is being operationalized in intimate apparel. Hanes Brands continues to emphasize everyday comfort through collections such as its Ultimate ComfortSoft women’s underwear, built around soft fabrics and practical silhouette options for routine wear. L Brands, through Aerie and Victoria’s Secret, integrates comfort with fashion-forward styling, using strong brand platforms to connect intimate apparel with broader lifestyle positioning. Fast Retailing’s UNIQLO approach highlights innovative fabric technologies designed for daily use, reinforcing the idea that functional material performance can anchor a high-volume basic category.
Men's Underwear Market
Wacoal represents the premium comfort and support segment with an emphasis on advanced engineering for fit and support, while Triumph International has built a recognizable position around seamless, wireless designs using high-performance materials. Aimer reflects a Japanese design-led model that prioritizes fit, style, and fabric quality, appealing to consumers who view intimate apparel as an everyday style and comfort decision. American Eagle Outfitters’ Aerie collection expands the comfort-and-sustainability conversation into retail environments with strong youth and young-adult reach. Marks & Spencer continues to leverage cotton and premium material choices across women’s and men’s lines, using trust and consistency to support a broad base of everyday purchases. PVH, through Calvin Klein and Tommy Hilfiger, connects intimate apparel to brand-image-led demand, showing how design identity can support premiumization in basics.
Beyond these larger franchises, a long tail of specialists and private-label players shapes the market’s flexibility. Gunze illustrates high-performance everyday underwear built on advanced knitting technologies, while Embrygroup and Bare Necessities serve broader retail demand through private-label and wholesale models. Hanky Panky, Lise Charmel, Wolf Lingerie, Cosmo Lady, Tinsino, and Your Sun demonstrate how specific positioning—whether luxury lace, French luxury craftsmanship, or specialized women’s collections—can sustain differentiated demand. Jockey International remains associated with durable, soft-fabric basics across men’s and women’s lines. Debenhams rounds out the retail landscape with in-house intimate apparel offerings.
Reading across these profiles reveals several strategic patterns. First, leading players are increasingly pairing brand identity with material and construction claims rather than relying on styling alone. Whether the emphasis is comfort, support, seamlessness, or luxury finish, durable differentiation is tied to product attributes that consumers can experience directly. Second, the presence of strong private-label and OEM capabilities indicates that scale manufacturers and contract producers are gaining influence over category direction, not just execution. This creates opportunities for retailers seeking own-brand differentiation and for brands seeking specialized production partners. Third, the market’s moderate concentration suggests room for continued fragmentation in niche segments even as larger players consolidate volume in core basics. The more likely trajectory is not a single dominant winner but a layered landscape where value pools are allocated by performance tier, price point, and channel strategy.
Forward Outlook: Trends and Commercial Implications
Looking toward the next three to five years, three trends are likely to shape how value is created and captured in intimate underwear.
Worldwide Sports Lingerie Market
The first trend is the continued elevation of fabric engineering as a core differentiator. As consumers become more educated about material performance, the market will increasingly reward products that deliver measurable comfort, fit stability, and durability. This creates opportunity for brands and suppliers that can translate textile innovation into repeatable product platforms rather than one-off seasonal releases. The commercial upside lies in lower return rates, stronger repeat purchase behavior, and clearer brand equity around performance. The risk is that innovation claims become harder to substantiate, raising the bar for credible communication and quality control.
The second trend is regulatory and safety assurance becoming a competitive variable rather than a purely defensive cost. As certification requirements tighten and verification mechanisms become more rigorous, companies with integrated compliance processes will gain speed and predictability, while those with weaker supplier visibility will face disruption. The opportunity is to use safety and material transparency as part of brand trust, especially in women’s intimate apparel where closeness-to-skin exposure heightens consumer sensitivity. The uncertainty lies in the pace of further regulatory tightening and the potential for divergent standards across regions, which can complicate global product rollouts.
The third trend is channel and portfolio realignment around everyday comfort, inclusive fit, and targeted premiumization. The core growth will likely continue to come from products that serve daily wear needs with improved sensory and functional attributes, while premium and luxury segments will remain important but more selective. Retailers and brands that align assortment planning with clearly defined use cases—routine comfort, support-oriented wear, style-plus-comfort, and specialty luxury—will be better equipped to manage inventory risk and margin mix. The danger is portfolio drift, where brands try to compete across too many positioning tiers without distinct product logic, leading to internal cannibalization and diluted consumer perception.
Strategic Actions for Decision-Makers
For manufacturers and material suppliers, the priority is to strengthen fabric and construction competency as a defensible asset. That means investing in repeatable product platforms, standardizing quality and compliance processes, and building supplier relationships that provide visibility into chemical inputs and material traceability. Companies that can demonstrate consistent performance and credible safety assurance will be better positioned to win branded and private-label business alike. It also means paying closer attention to fit architecture and sizing consistency, since these factors directly affect satisfaction and repeat purchase in a category where small comfort differences compound over time.
For investors and corporate strategists, the key is to distinguish between volume-driven exposure and genuinely differentiated positioning. Moderate market concentration and a broad supplier base create opportunities, but not all share gains are equally durable. Businesses with clear product logic, credible innovation claims, and robust compliance capability are better situated to protect margins through regulatory and cost pressure. Portfolio evaluation should therefore place weight on material competency, repeat-purchase dynamics, and the ability to communicate product benefits in specific rather than generic terms. In a market growing steadily but not explosively, relative positioning and execution quality will matter more than broad category tailwinds.
For retail buyers and brand leaders, the strategic question is how to balance everyday basics with differentiated tiers without losing assortment clarity. That involves aligning inventory planning with clearly segmented demand, using fit and comfort as primary assortment drivers, and selecting suppliers that can support both volume reliability and technical performance. Transparency around materials and safety can be used to reinforce trust, but it must be backed by operational discipline. The most resilient approach is to treat intimate apparel not as a low-involvement commodity category but as a daily-use product where fabric, fit, and credibility determine long-term loyalty.
For leaders who need to move quickly with segment-specific sizing, regional demand patterns, material compliance roadmaps, and competitor positioning detail, the full research report provides deeper segmentation data and customized recommendations that go beyond the structural overview presented here.
For detailed analysis of this topic, please visit the official page: Intimate Underwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com