

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bipolar Forceps Market: Why 4.56% CAGR and $43.1M Size Reshape Strategy

Navigating the Bipolar Forceps Market: Strategic Trends and Commercial Opportunities in a Consolidating Landscape
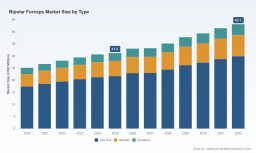
The bipolar forceps market has matured into a stable, value-driven segment within the broader electrosurgical instrument space. Recent market sizing indicates a global footprint approaching $31.2 million in the base year, with steady expansion projected through the early 2030s. The trajectory reflects a compound annual growth rate that positions the segment as a reliable, low-volatility opportunity for medical device manufacturers, surgical facility operators, and strategic investors. Growth is not explosive, but it is structurally reinforced by procedural volume increases, technological refinement, and a shifting cost calculus that favors precision, durability, and waste reduction. Understanding where value is created, where margins are pressured, and how leading players are positioning themselves requires moving beyond headline figures and examining the underlying mechanics of adoption, procurement, and competitive differentiation.
Bone Cutting Forcep Market
Market Status and Core Challenges
The segment reflects a market that has reached a point of equilibrium between clinical utility and economic scrutiny. Demand is broadly distributed across surgical specialties, with general surgical applications capturing the largest share of procedural usage, while gynecological interventions, cardiac procedures, and neurosurgical workflows collectively account for meaningful downstream demand. Product architecture remains anchored around three functional components: jaw tips, handles, and insulation materials. Jaw tips dominate the value pool due to their direct impact on tissue interaction, coagulation precision, and thermal management. Handles and insulation, while smaller in absolute contribution, are critical to ergonomics, safety, and repeat-use viability. Geographically, the market is led by well-established healthcare infrastructure regions, followed by Europe and a steadily expanding Asia Pacific footprint. Smaller regional contributions from Latin America and the Middle East and Africa reflect ongoing procurement constraints, variable reimbursement environments, and slower adoption of advanced electrosurgical tooling in lower-volume facilities.
The market structure is moderately concentrated. The top three participants command roughly four-tenths of total revenue, while the top five approach two-thirds. This concentration suggests that scale, distribution reach, and clinical reputation remain meaningful barriers, but it also leaves considerable room for specialized players to differentiate through material science, single-use innovation, or niche surgical applications. The presence of multiple mid-tier and regional manufacturers indicates that the segment is not impermeable to new entrants, particularly those that can solve specific pain points around cost, sterilization burden, or thermal spread.
Several structural challenges are reshaping how manufacturers, hospitals, and suppliers think about this market. First, the reusable-to-disposable decision continues to be a strategic fault line. Reusable bipolar forceps require stringent sterilization cycles and maintenance protocols. Each sterilization process can cost up to $6 per cycle, adding 15–18% to hospital operating budgets annually. This recurring cost pressure is pushing procurement teams to weigh asset longevity against workflow efficiency, infection control preferences, and total cost of ownership. Second, thermal management remains a clinical and commercial priority. Even with bipolar technology’s inherent advantages over monopolar alternatives, lateral thermal spread and tissue adherence still influence surgeon satisfaction, complication profiles, and instrument selection. Third, the market is experiencing procurement consolidation. Group purchasing organizations and integrated health systems are increasingly standardizing instrument portfolios, which compresses pricing flexibility and rewards suppliers that can demonstrate consistent performance, reliable supply, and clear economic justification. Together, these forces create a market where clinical performance alone is no longer sufficient; economic durability and operational fit are equally decisive.
Key Drivers of Market Change
Technological innovation remains the most visible catalyst in the segment. Recent product launches show a clear emphasis on irrigation capacity, non-stick surfaces, and refined tip geometry. For example, Aesculap’s October 2025 introduction of irrigating specialty non-stick disposable bipolar forceps, featuring 49% higher irrigation output, illustrates how incremental engineering improvements are being used to expand portfolios that already span hundreds of configurations. This direction matters because enhanced irrigation reduces char buildup, improves visualization, and supports cleaner dissection in fluid-rich surgical fields. Non-stick coatings and mixed matrix materials similarly address a long-standing frustration: instrument fouling that interrupts procedures, compromises sealing consistency, and increases cleanup or replacement frequency. The broader trend is toward instruments that are not merely conductive, but actively supportive of surgical workflow under demanding conditions.
PW Consulting
Policy and regulatory dynamics are shaping the pace and shape of adoption. Electrosurgical instruments operate within regulatory frameworks that emphasize biocompatibility, electrical safety, sterilization validation, and, for single-use devices, material integrity and disposal compliance. As health systems face heightened scrutiny around surgical site infection, reusable instrument reprocessing standards, and cost containment, regulatory expectations indirectly reinforce demand for reliable, validated, and traceable product lines. In parallel, reimbursement environments in several regions are incentivizing procedural efficiency and shorter recovery pathways. This does not dictate device selection outright, but it raises the importance of instruments that help surgeons work faster, reduce thermal complications, and support minimally invasive approaches that align with favorable reimbursement logic.
Bipolar Laparoscopic Forceps Market
Demand-side behavior is shifting as surgical preferences and institutional priorities evolve. Surgeons increasingly favor tools that reduce hand fatigue, improve tactile responsiveness, and minimize the need for instrument exchanges. Ergonomic handle design and insulated tip configurations are no longer optional enhancements; they are becoming baseline expectations, particularly in microsurgery, neurosurgery, and laparoscopic applications where precision is paramount. On the institutional side, procurement leaders are placing greater weight on total cost of ownership rather than unit price alone. The recurring expense of sterilization, instrument repair, and replacement cycles is pushing facilities to reconsider disposable options in high-throughput settings, while still preserving reusable instruments for specialized, lower-volume procedures where durability and perceived clinical familiarity retain value. This bifurcation is creating distinct demand pools with different purchasing logic.
Cost structure and supply chain considerations are adding another layer of pressure and opportunity. The sterilization burden described earlier is only one part of a broader economic equation. Manufacturing consistency, tip coating quality, material sourcing, and packaging reliability all influence both clinical performance and commercial resilience. Suppliers that can maintain stable production pipelines, control coating uniformity, and reduce variability in disposable formats gain an advantage in tenders and standardized procurement programs. At the same time, currency exposure, logistics complexity, and regional manufacturing footprints are becoming more relevant as cross-border procurement expands. Companies that can balance quality control with cost discipline are better positioned to protect margins in a market where pricing competition is intensifying in specific applications and geographies.
Competitive Landscape and Leading Strategies
The competitive field blends large multinational platforms with specialized manufacturers and regional suppliers, each pursuing different value propositions. Aesculap stands out for breadth, offering more than 300 bipolar forceps across reusable and disposable formats, including non-stick and irrigating options for neurosurgery and general procedures. Its recent push into higher-output irrigating disposables signals a strategy built on portfolio depth, clinical variety, and incremental performance upgrades. Medtronic contributes a different kind of strength: sensor-integrated and precision-control models designed for electrosurgery, ablation, and surgical applications where controlled energy delivery matters. This reflects a broader platform approach in which bipolar forceps are part of a larger ecosystem of energy-based and instrumented surgical tools. B. Braun Melsungen AG emphasizes ergonomics and thermal management through non-stick insulated forceps that aim to reduce thermal spread and lateral tissue damage. That patient-safety and tissue-protection framing is a differentiated narrative in a segment where thermal control is a recurring clinical concern.
Other players are carving out positions around specific surgical contexts or design philosophies. CONMED focuses on laparoscopic and general surgery with insulated and non-insulated tip configurations, aligning with the procedural demand that represents the largest end-use pool. Stryker produces non-stick bipolar forceps for neurosurgery and vessel sealing, offering reusable and single-use options that bridge clinical precision with workflow flexibility. KLS Martin Group and Integra LifeSciences both emphasize neurosurgical and microsurgical applications, with ergonomic handles, insulated tips, and reusable/disposable configurations tailored to high-precision workflows. Kirwan Surgical Products has built its identity around high-performance non-stick forceps using mixed matrix material and a disposable Liberty line for microsurgery, an example of material-led differentiation in a crowded field. Stingray Surgical Products maintains a more classic microsurgical emphasis with multiple handle and tip styles, including Potts Smith, Semkin, and Adson configurations, appealing to surgeons who value familiar form factors and procedural specificity.
A notable geographic diversification is emerging from Asian manufacturers. Beijing Taktvoll Technology produces non-stick bipolar bayonet and Maryland-style forceps for laparoscopic and endoscopic procedures, while Hangzhou Boer Medical Instrument supplies disposable laparoscopic bipolar coagulation forceps with Maryland and fenestrated tips for general and gynecological use. Diamond Surgical, based in India, manufactures bipolar forceps for neurosurgery and laparoscopic applications that meet international standards. These companies illustrate a broader pattern: regional manufacturers are not merely offering lower-cost alternatives, but increasingly targeting specific procedural needs, disposable formats, and compliance expectations that make them relevant in procurement discussions beyond price alone. Their presence expands the competitive perimeter and gives buyers more options for balancing cost, application fit, and supply continuity.
The market is evolving along several structural lines. Consolidation is visible at the top, where scale players leverage distribution networks, cross-selling into broader surgical portfolios, and platform-based value propositions. Differentiation is happening in the middle and specialized tiers, where material science, irrigation performance, ergonomic design, and single-use convenience create defensible niches. New entry remains plausible, especially for companies that can address sterilization economics, reduce thermal spread, or align disposable designs with high-volume procedural workflows. The most successful strategies tend to combine clinical credibility with economic logic: instruments that surgeons trust, procurement teams can justify, and supply chains can sustain.
Forward-Looking Trends for the Next 3–5 Years
One likely trend is the continued rebalancing between reusable and disposable bipolar forceps, driven less by ideology than by workload economics. High-throughput surgical environments will increasingly evaluate disposable options not as a convenience premium, but as a way to manage sterilization cost, scheduling predictability, and infection-control consistency. Reusable instruments will remain relevant in specialized, lower-frequency procedures and in settings where asset longevity and surgeon familiarity outweigh recurring reprocessing costs. The market is therefore expected to segment operationally, with different procurement patterns emerging by facility type, procedure mix, and regional cost structures. For manufacturers, this implies that product portfolios must be designed with both pathways in mind, and that value messaging must speak to total cost of ownership as much as clinical performance.
A second trend is the incremental but meaningful elevation of performance specifications around irrigation, non-stick behavior, and thermal control. As surgeons accumulate experience with higher-output irrigation and advanced coating materials, expectations will rise. Instruments that reduce charring, maintain tip clarity, and limit lateral thermal effects will become more favored in procedure types where precision and visualization are closely linked to outcomes and workflow efficiency. This creates an opportunity for companies that can reliably engineer and scale these features without compromising durability or cost. It also raises the stakes for suppliers whose products lag in these attributes, particularly as procurement teams gain access to more comparable options across multinational and regional manufacturers.
A third trend is the gradual tightening of procurement standards and the growing importance of supply reliability. Group purchasing organizations, integrated delivery networks, and hospital chains are likely to continue standardizing instrument selections, which favors suppliers with consistent quality, predictable lead times, and clear documentation. In this environment, competitive advantage will increasingly depend on manufacturing discipline, packaging integrity, and the ability to support standardized adoption across multiple facilities. At the same time, regional manufacturers that can demonstrate international compliance, application-specific fit, and competitive total cost will continue to gain traction, especially in markets where import dependency, lead-time risk, or price sensitivity constrain purchasing options. The principal uncertainty in this outlook lies in reimbursement shifts, sterilization policy evolution, and the pace at which disposable adoption accelerates in diverse healthcare settings. If sterilization economics worsen or infection-control expectations tighten, disposable demand could strengthen faster than current baselines suggest. If procurement pressure intensifies without corresponding clinical differentiation, price competition could compress margins more sharply than anticipated.
Actionable Recommendations for Decision Makers
For manufacturers, the strategic priority is to align product portfolios with the economic and clinical realities shaping procurement decisions. This means treating non-stick performance, irrigation capacity, ergonomics, and thermal control as commercial essentials rather than feature add-ons. Companies should also prepare for a dual-track demand environment by offering clearly differentiated reusable and disposable lines, each with a credible value proposition tied to procedure type, volume, and total cost of ownership. Supply consistency and specification reliability will matter as much as innovation, particularly as standardized procurement programs reward predictability. Manufacturers that can demonstrate repeatable quality, transparent cost logic, and application-specific fit will be better positioned to defend share and expand into procurement cycles that are otherwise difficult to penetrate.
For investors, the opportunity lies in identifying where differentiation is defensible and where consolidation is likely to intensify. The segment’s moderate concentration leaves room for specialized players with strong material science, clear application focus, or compelling disposable economics, but it also suggests that scale advantages in distribution, platform integration, and procurement relationships will continue to matter. Investment scrutiny should extend beyond unit growth to examine sterilization economics, disposable adoption rates, reimbursement exposure, and the durability of a company’s clinical narrative. Providers that are expanding beyond price competition into performance, workflow, and safety arguments are generally better insulated from margin erosion than those competing primarily on cost. Monitoring regional manufacturers with credible compliance profiles and targeted application fit is also worthwhile, as they may represent either partnership opportunities or competitive pressures depending on the market being served.
For procurement leaders and hospital administrators, the key is to evaluate bipolar forceps decisions through a total-cost and workflow lens rather than a unit-price lens alone. Sterilization costs, repair frequency, instrument exchange rates, and procedural throughput should be incorporated into evaluations alongside clinical feedback from surgeons. Where disposable instruments reduce reprocessing burden, improve scheduling predictability, or lower thermal-related interruptions, they may justify adoption even at higher per-unit cost. Where reusable instruments maintain durability and surgeon preference in lower-volume or highly specialized procedures, they can remain economically rational. Standardization efforts should be paired with performance benchmarking so that portfolio simplification does not inadvertently sacrifice clinical preference or procedural efficiency. In practice, the most resilient procurement strategies are those that match instrument format to procedure economics, maintain reliable supply, and preserve enough flexibility to accommodate both high-throughput and specialized surgical needs.
The bipolar forceps market is not defined by dramatic disruption, but by a steady accumulation of clinical refinements, economic pressures, and procurement discipline that collectively reshape where value is captured. Companies and investors that understand the interplay between sterilization economics, thermal performance, ergonomic demand, and regional supply dynamics will be better equipped to navigate the next phase of growth. For decision makers seeking deeper segmentation, device-level comparisons, procurement scenario modeling, and customized strategic recommendations, the full research report provides a more granular view of the forces shaping this segment and the actions most likely to create durable advantage.
For detailed analysis of this topic, please visit the official page: Bipolar Forceps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com